Turning Application Friction Into Adoption
Six Credit Products. One Clearer Path Through Checkout.
- My Role
- Led a six-week redesign of six U.S. and U.K. PayPal credit applications, creating a flexible shared framework that cut Pay in 4 from three steps to one—doubling completion (2.08×) and lifting portfolio-wide conversion from 51% to 79%.
Why PayPal credit applications needed redesign
A credit card takes seconds. Applying for PayPal credit interrupted the purchase every time. The project began with one question: how much of that friction was actually necessary?
The Scope
The assignment looked like six separate redesigns.
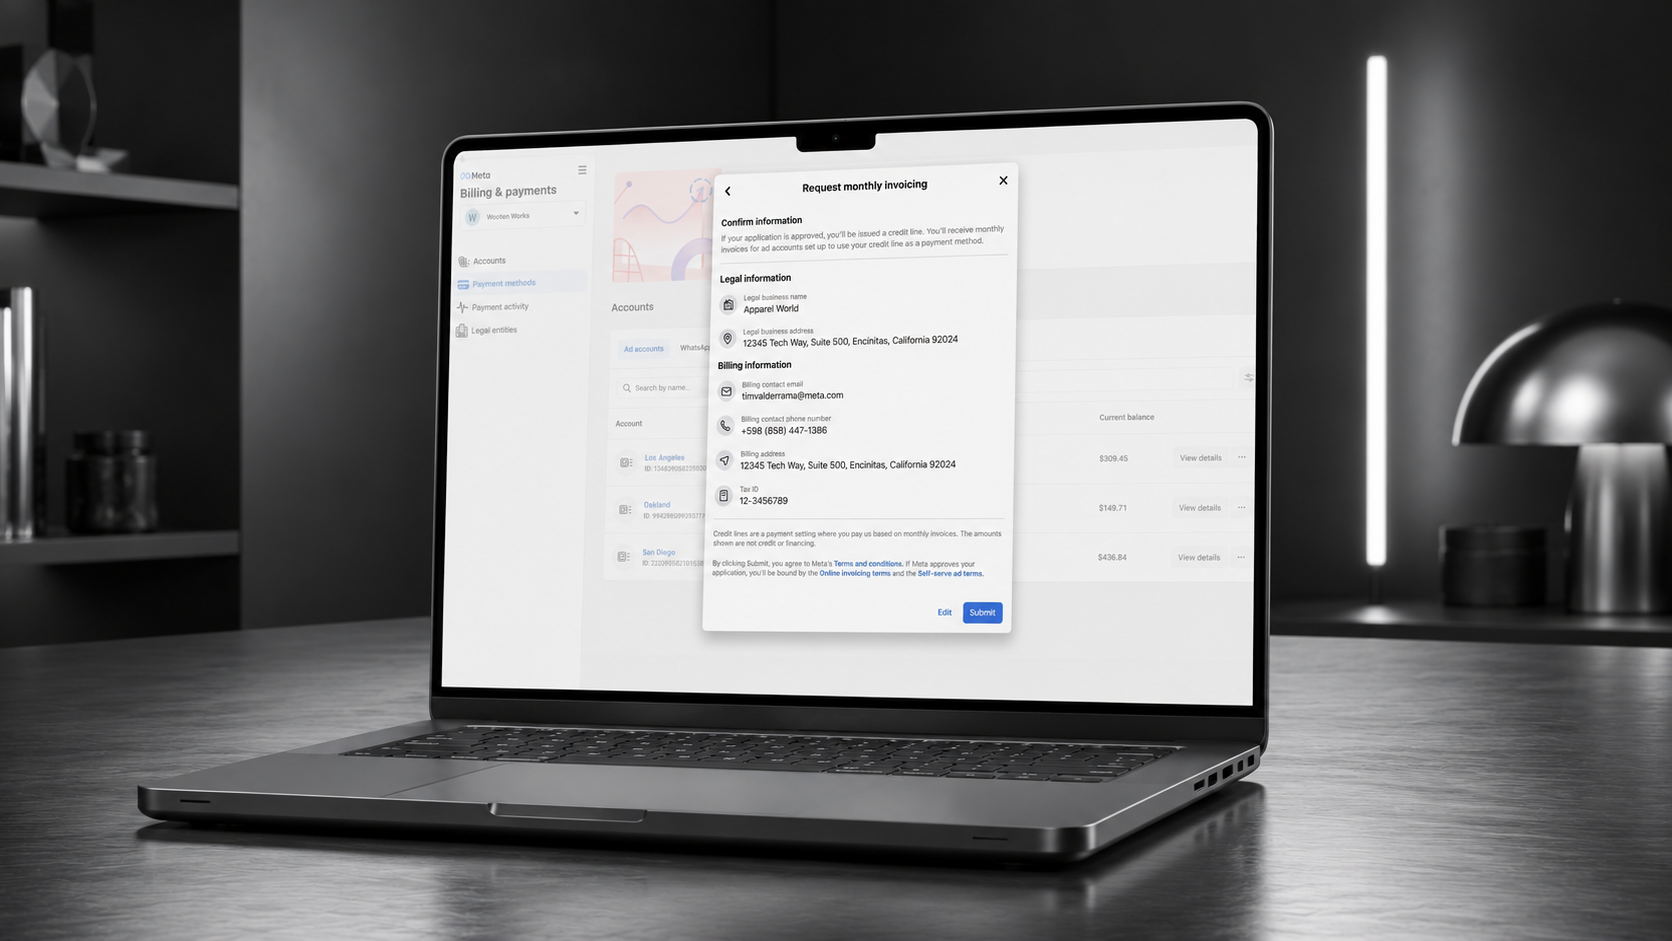
Six products had evolved across two markets, each with its own funnel, success metrics, and regulatory constraints. Side-by-side mapping exposed one shared problem: repeated checkout interruption.
- Credit products
- 6
- Markets
- 2
- Checkout framework
- 1
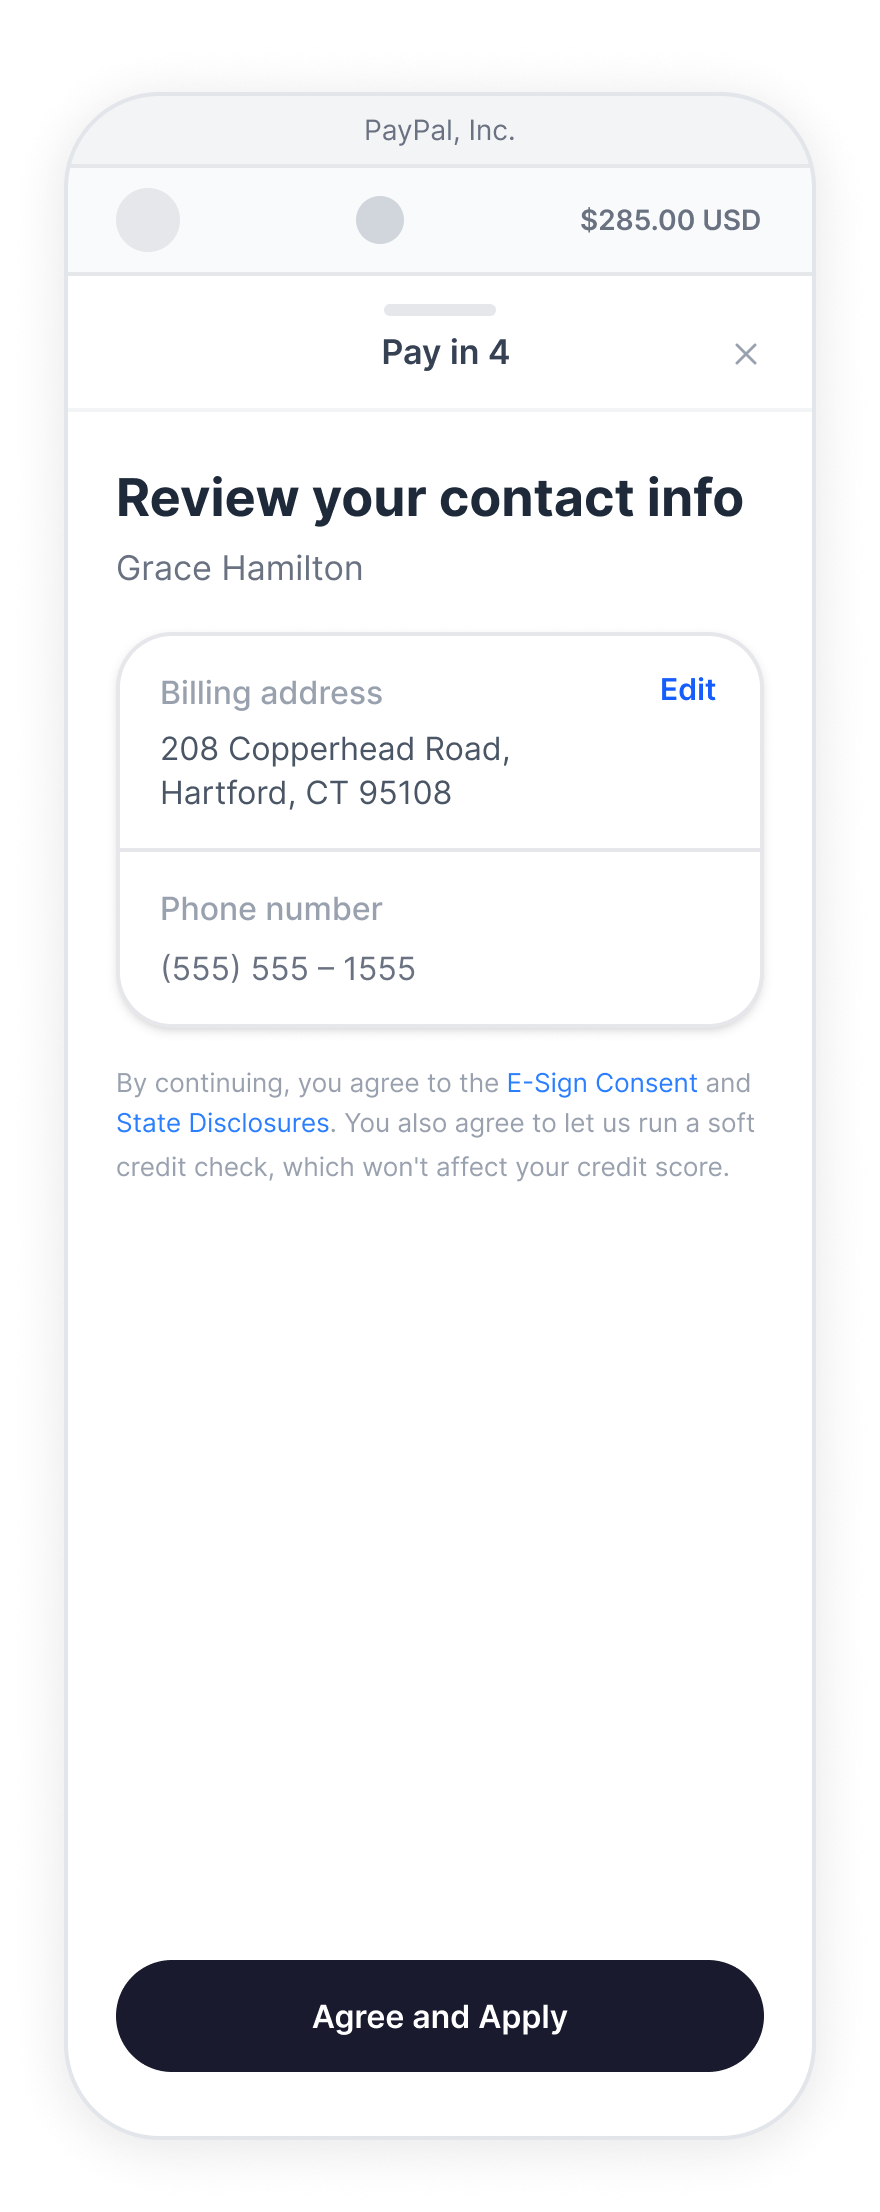
Pay in 4
United States
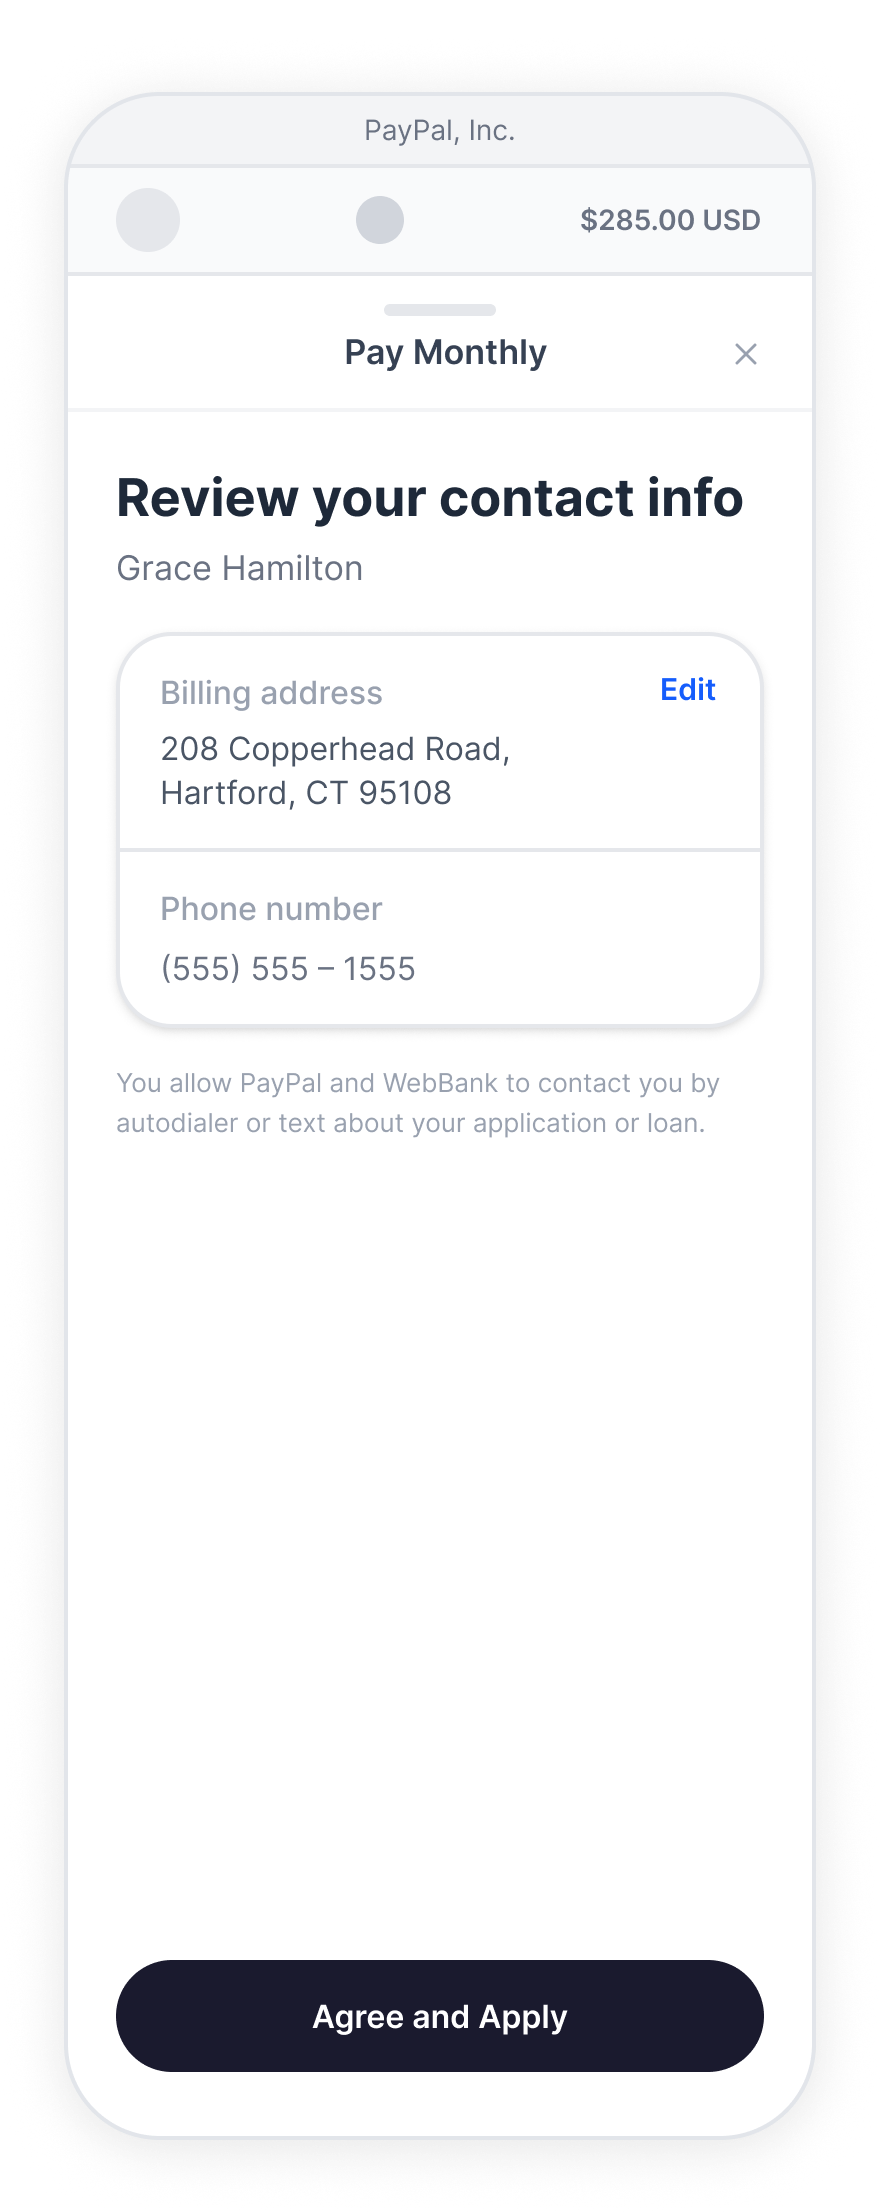
Pay Monthly
United States
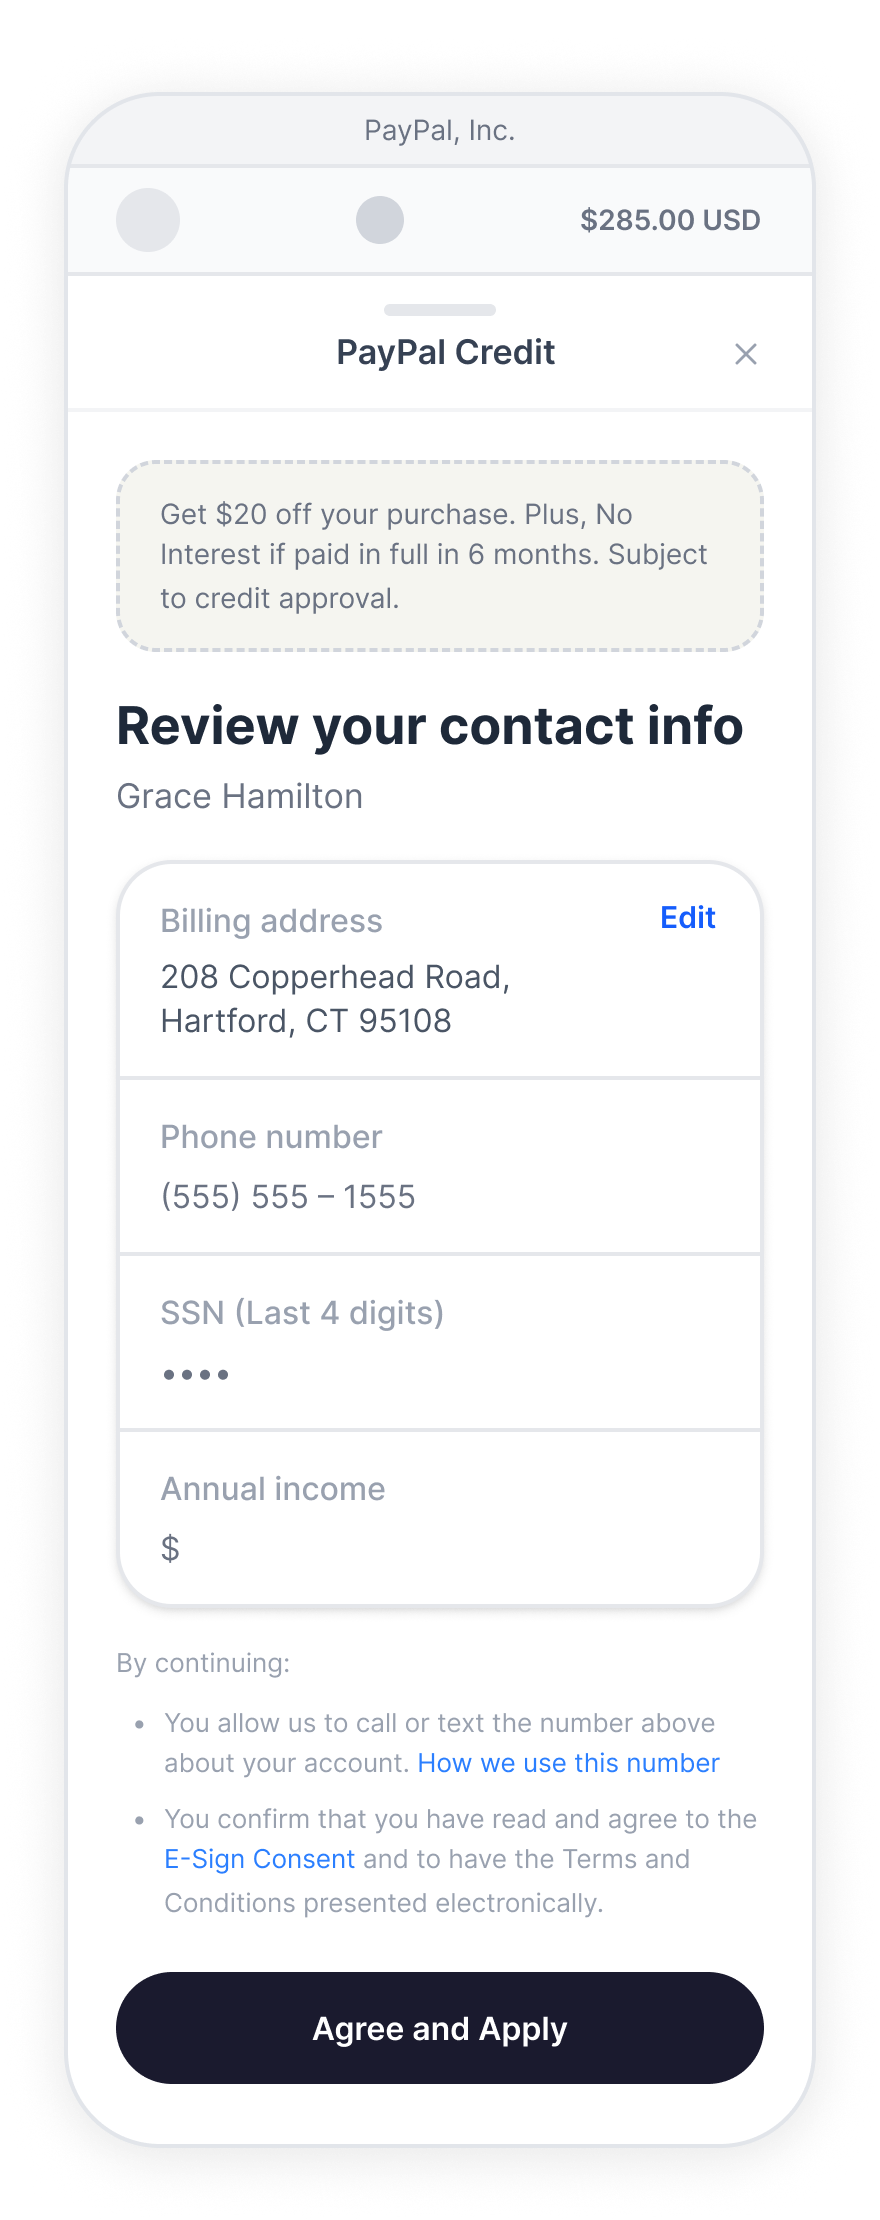
PayPal Credit
United States
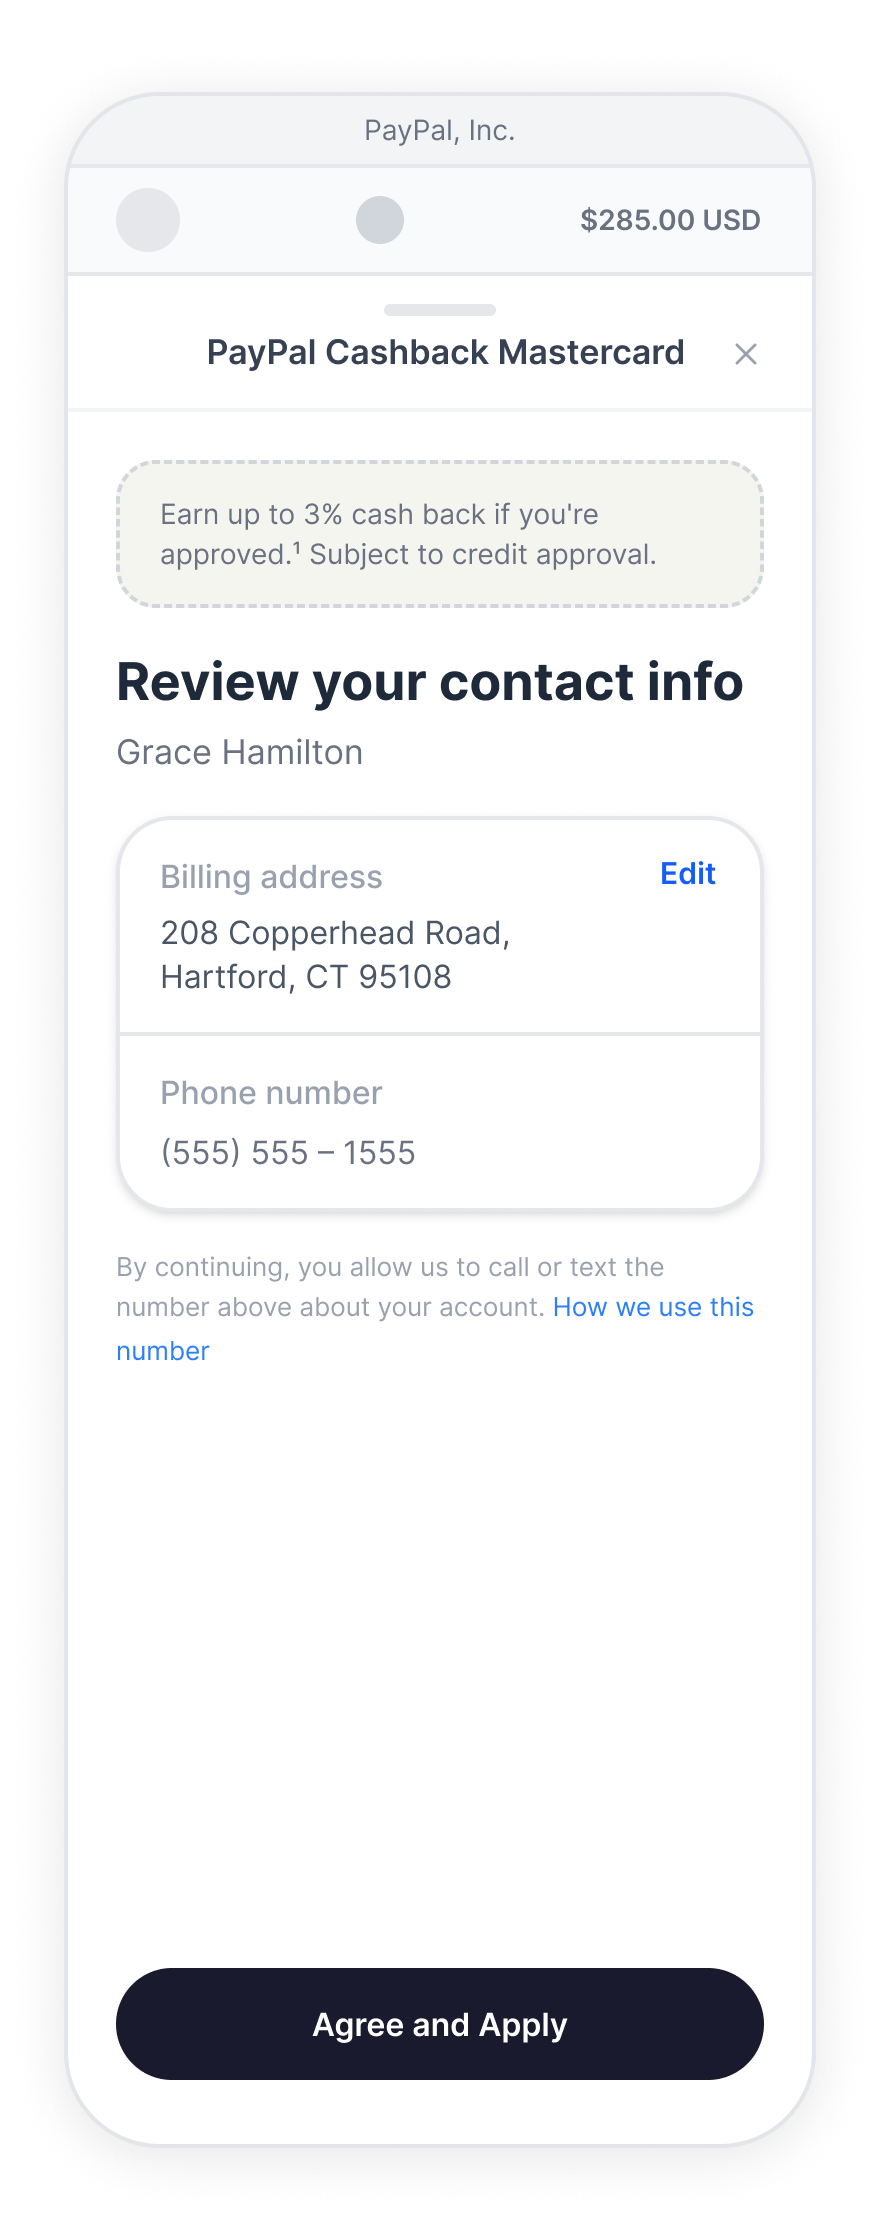
PayPal Mastercard
United States
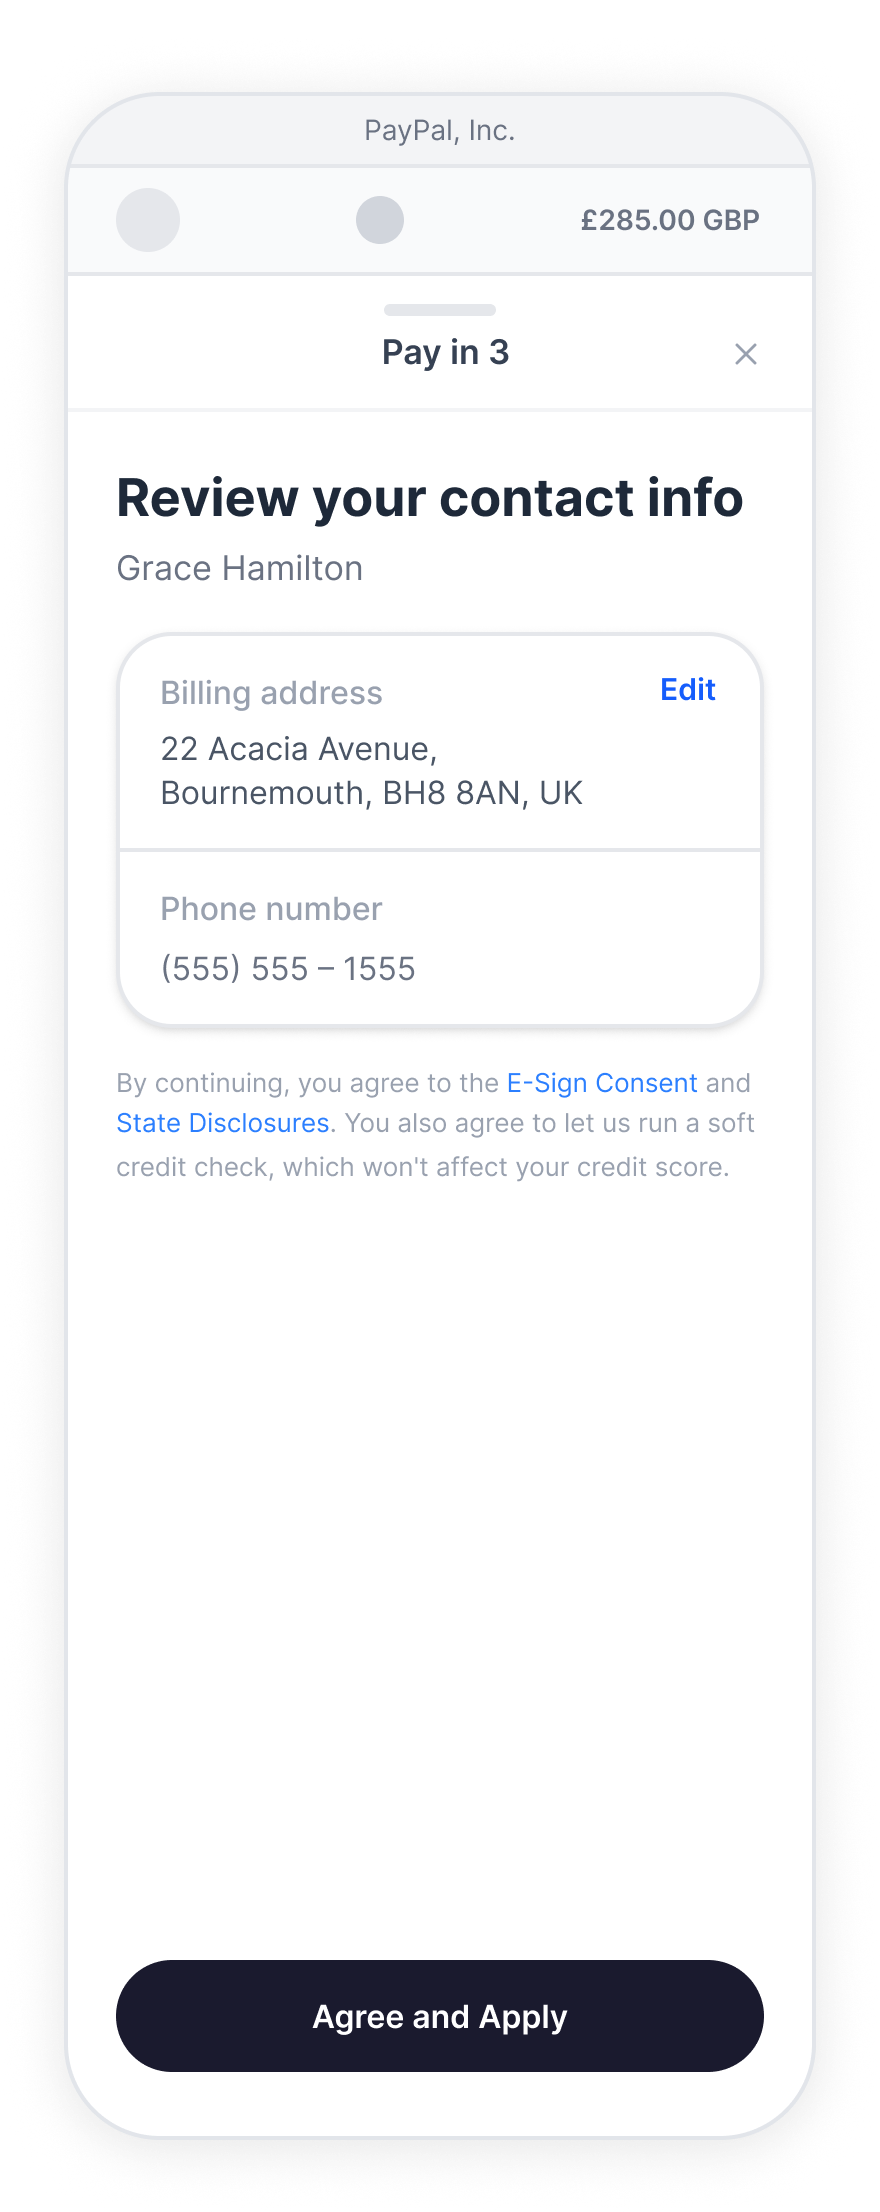
Pay in 3
United Kingdom
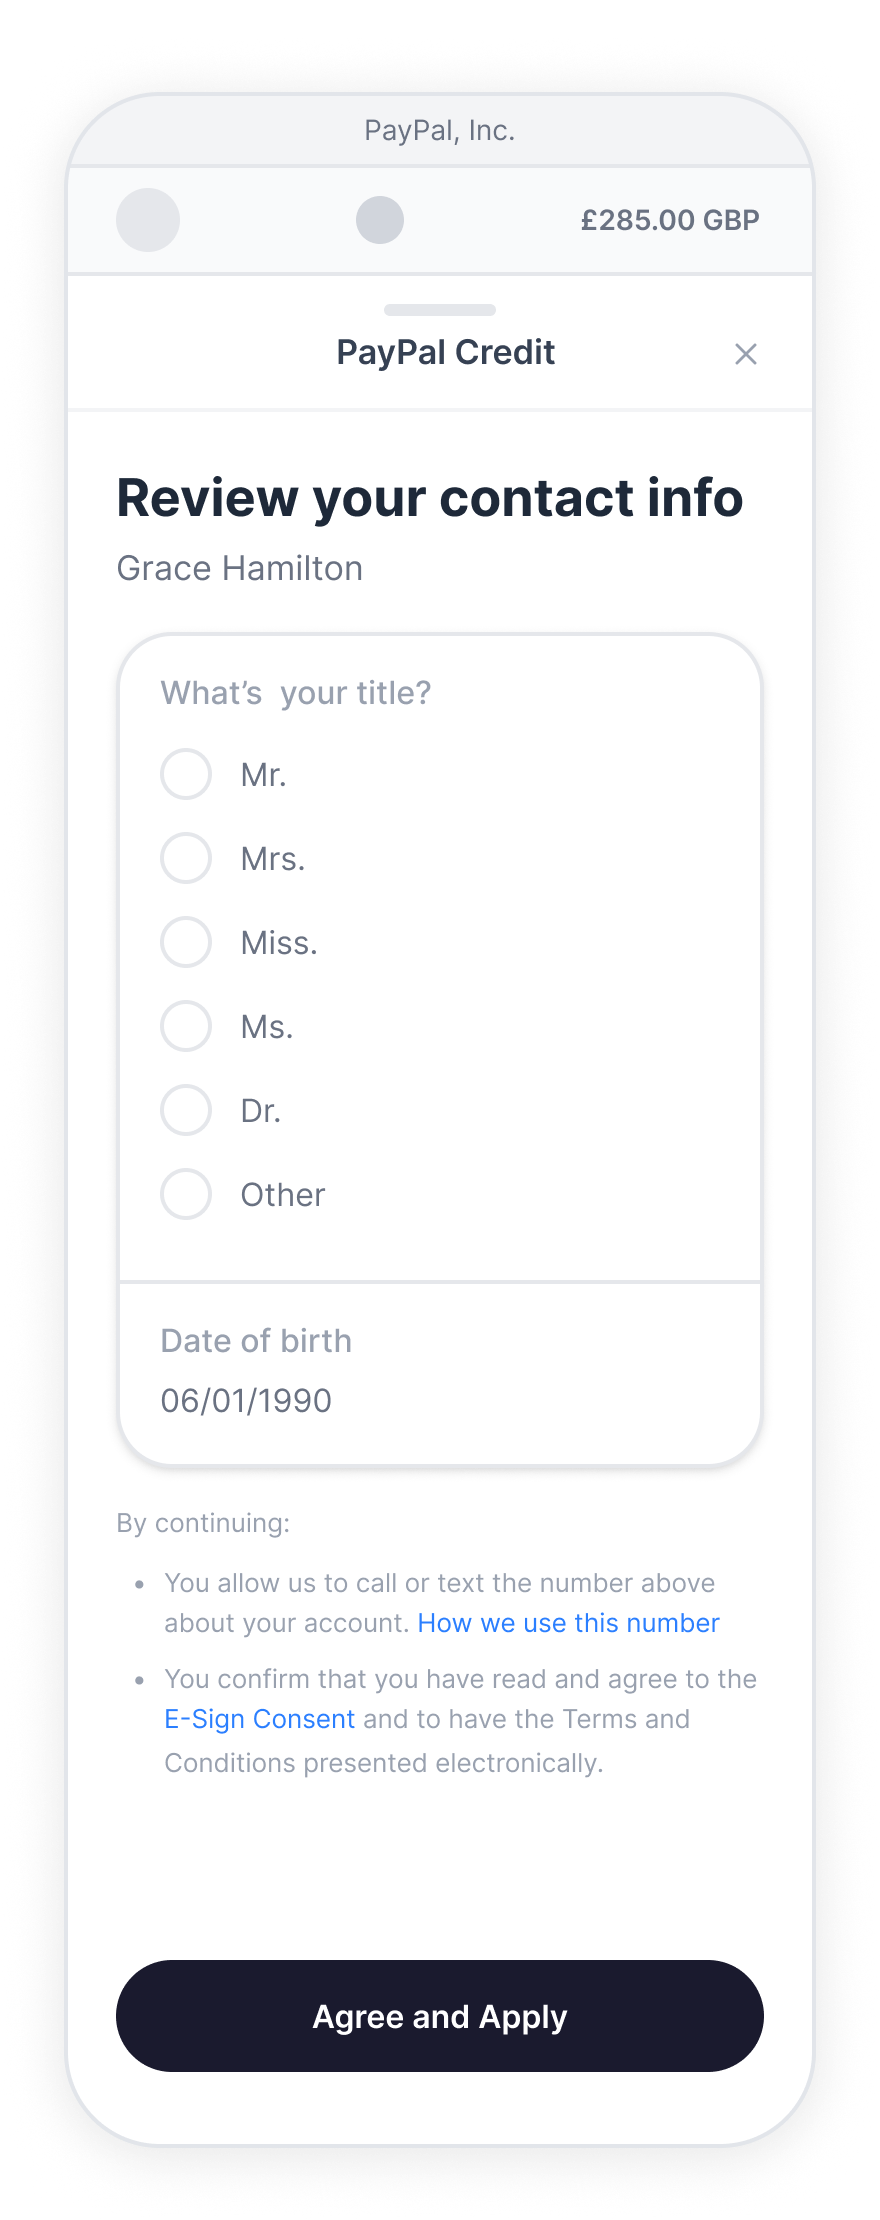
PayPal Credit
United Kingdom
Different products. Different constraints. The same interruption.
Deep Dive
Pay in 4 made the problem impossible to ignore.
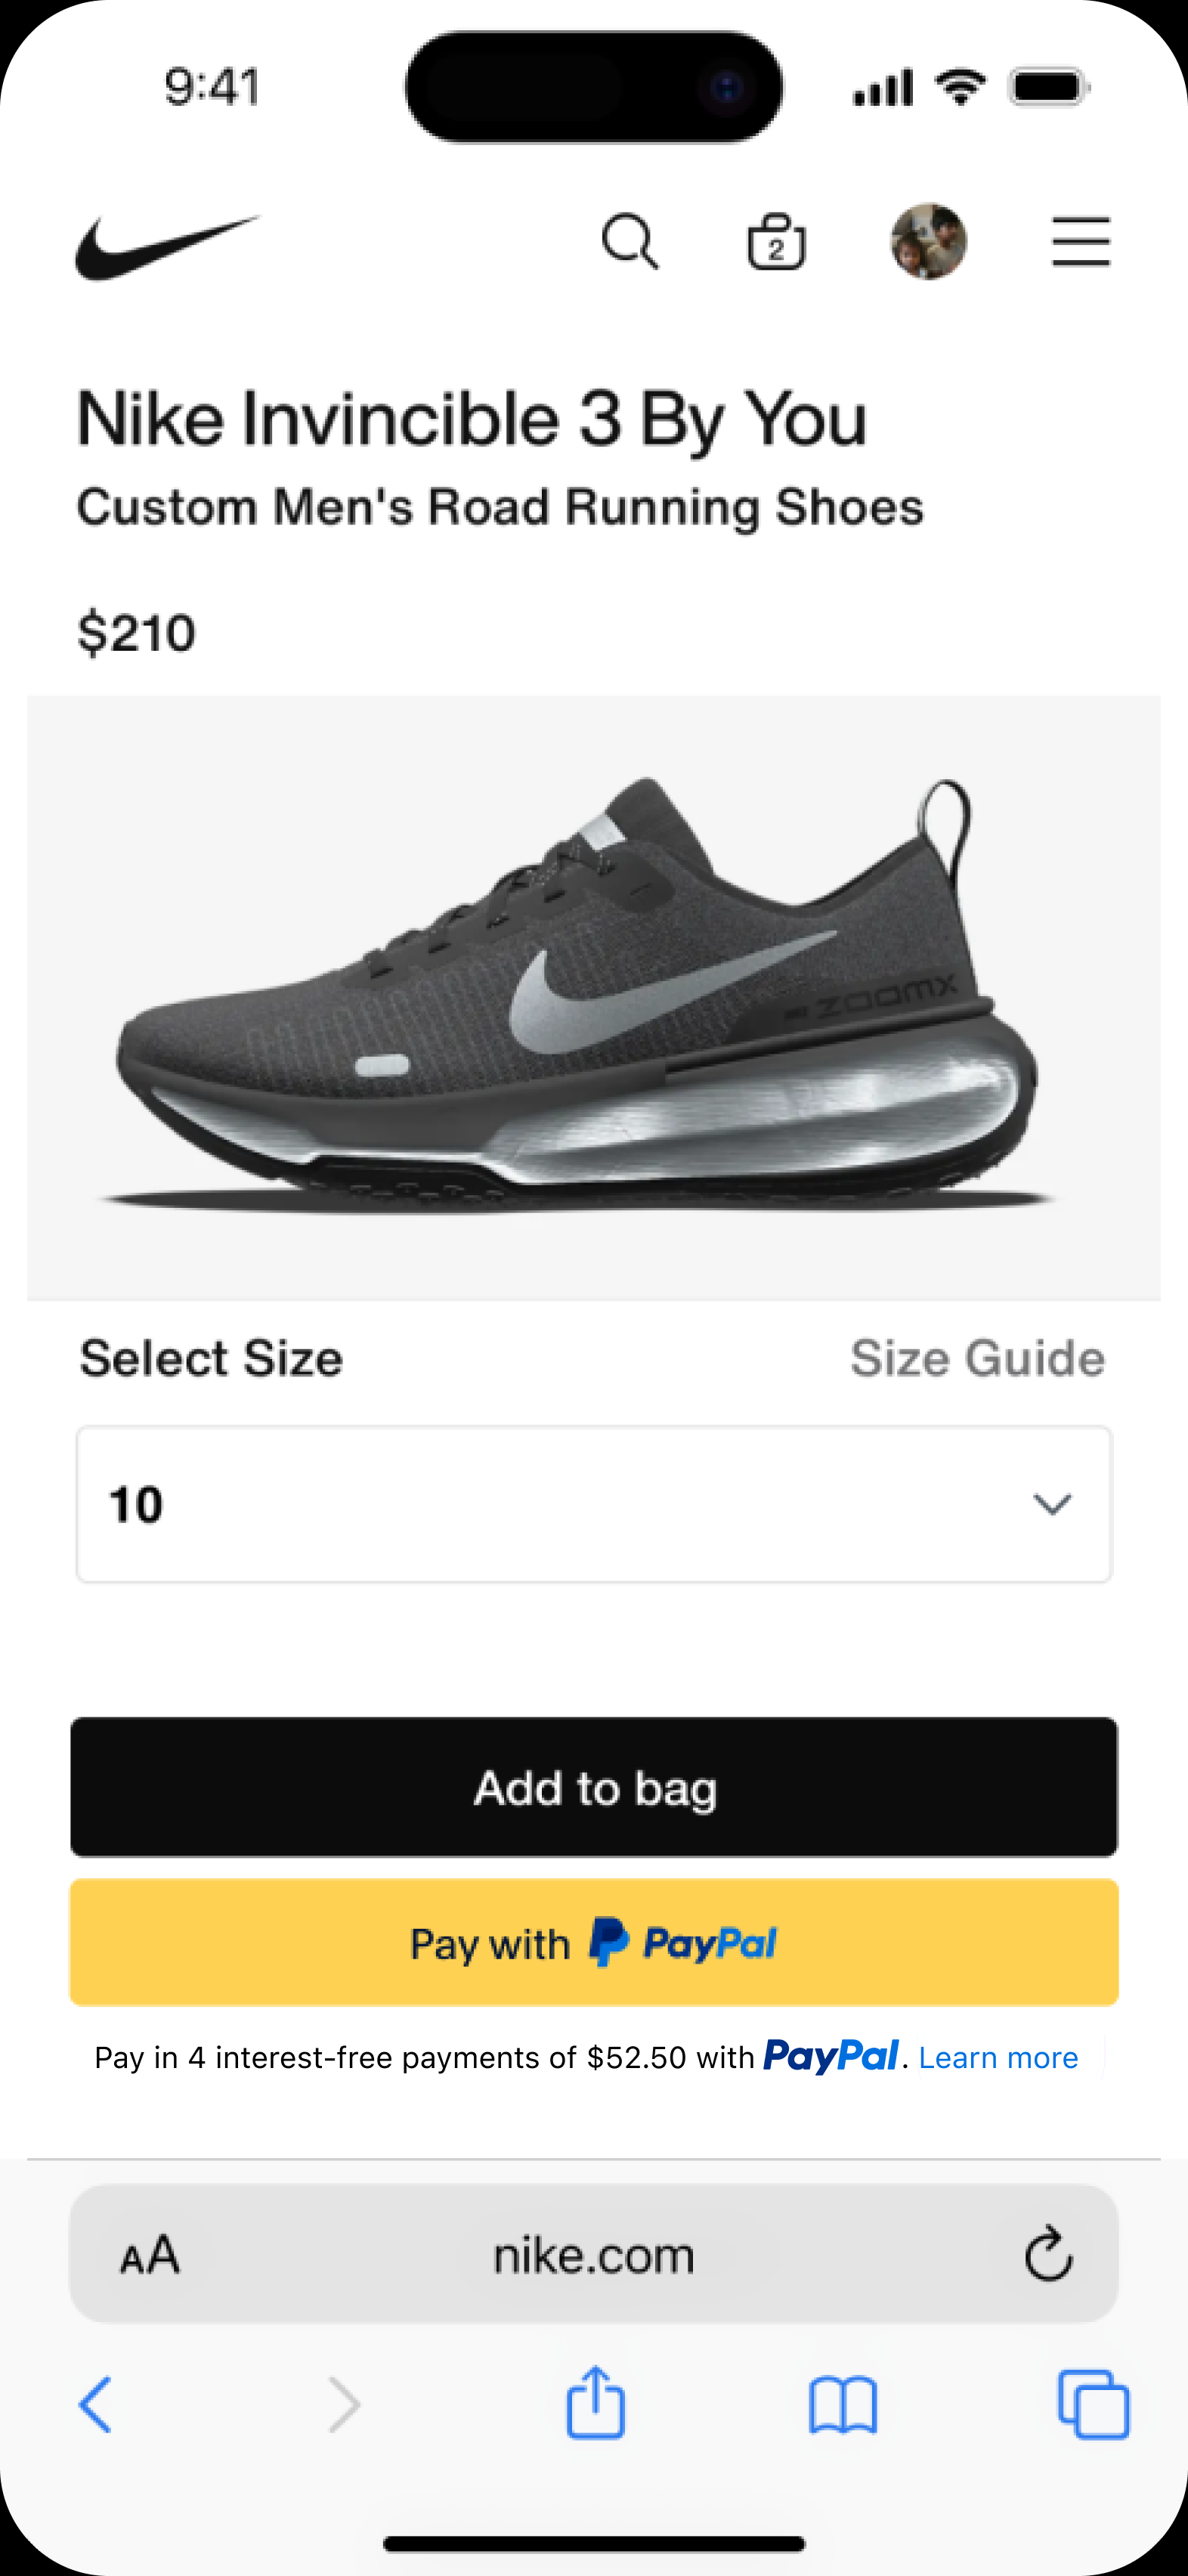
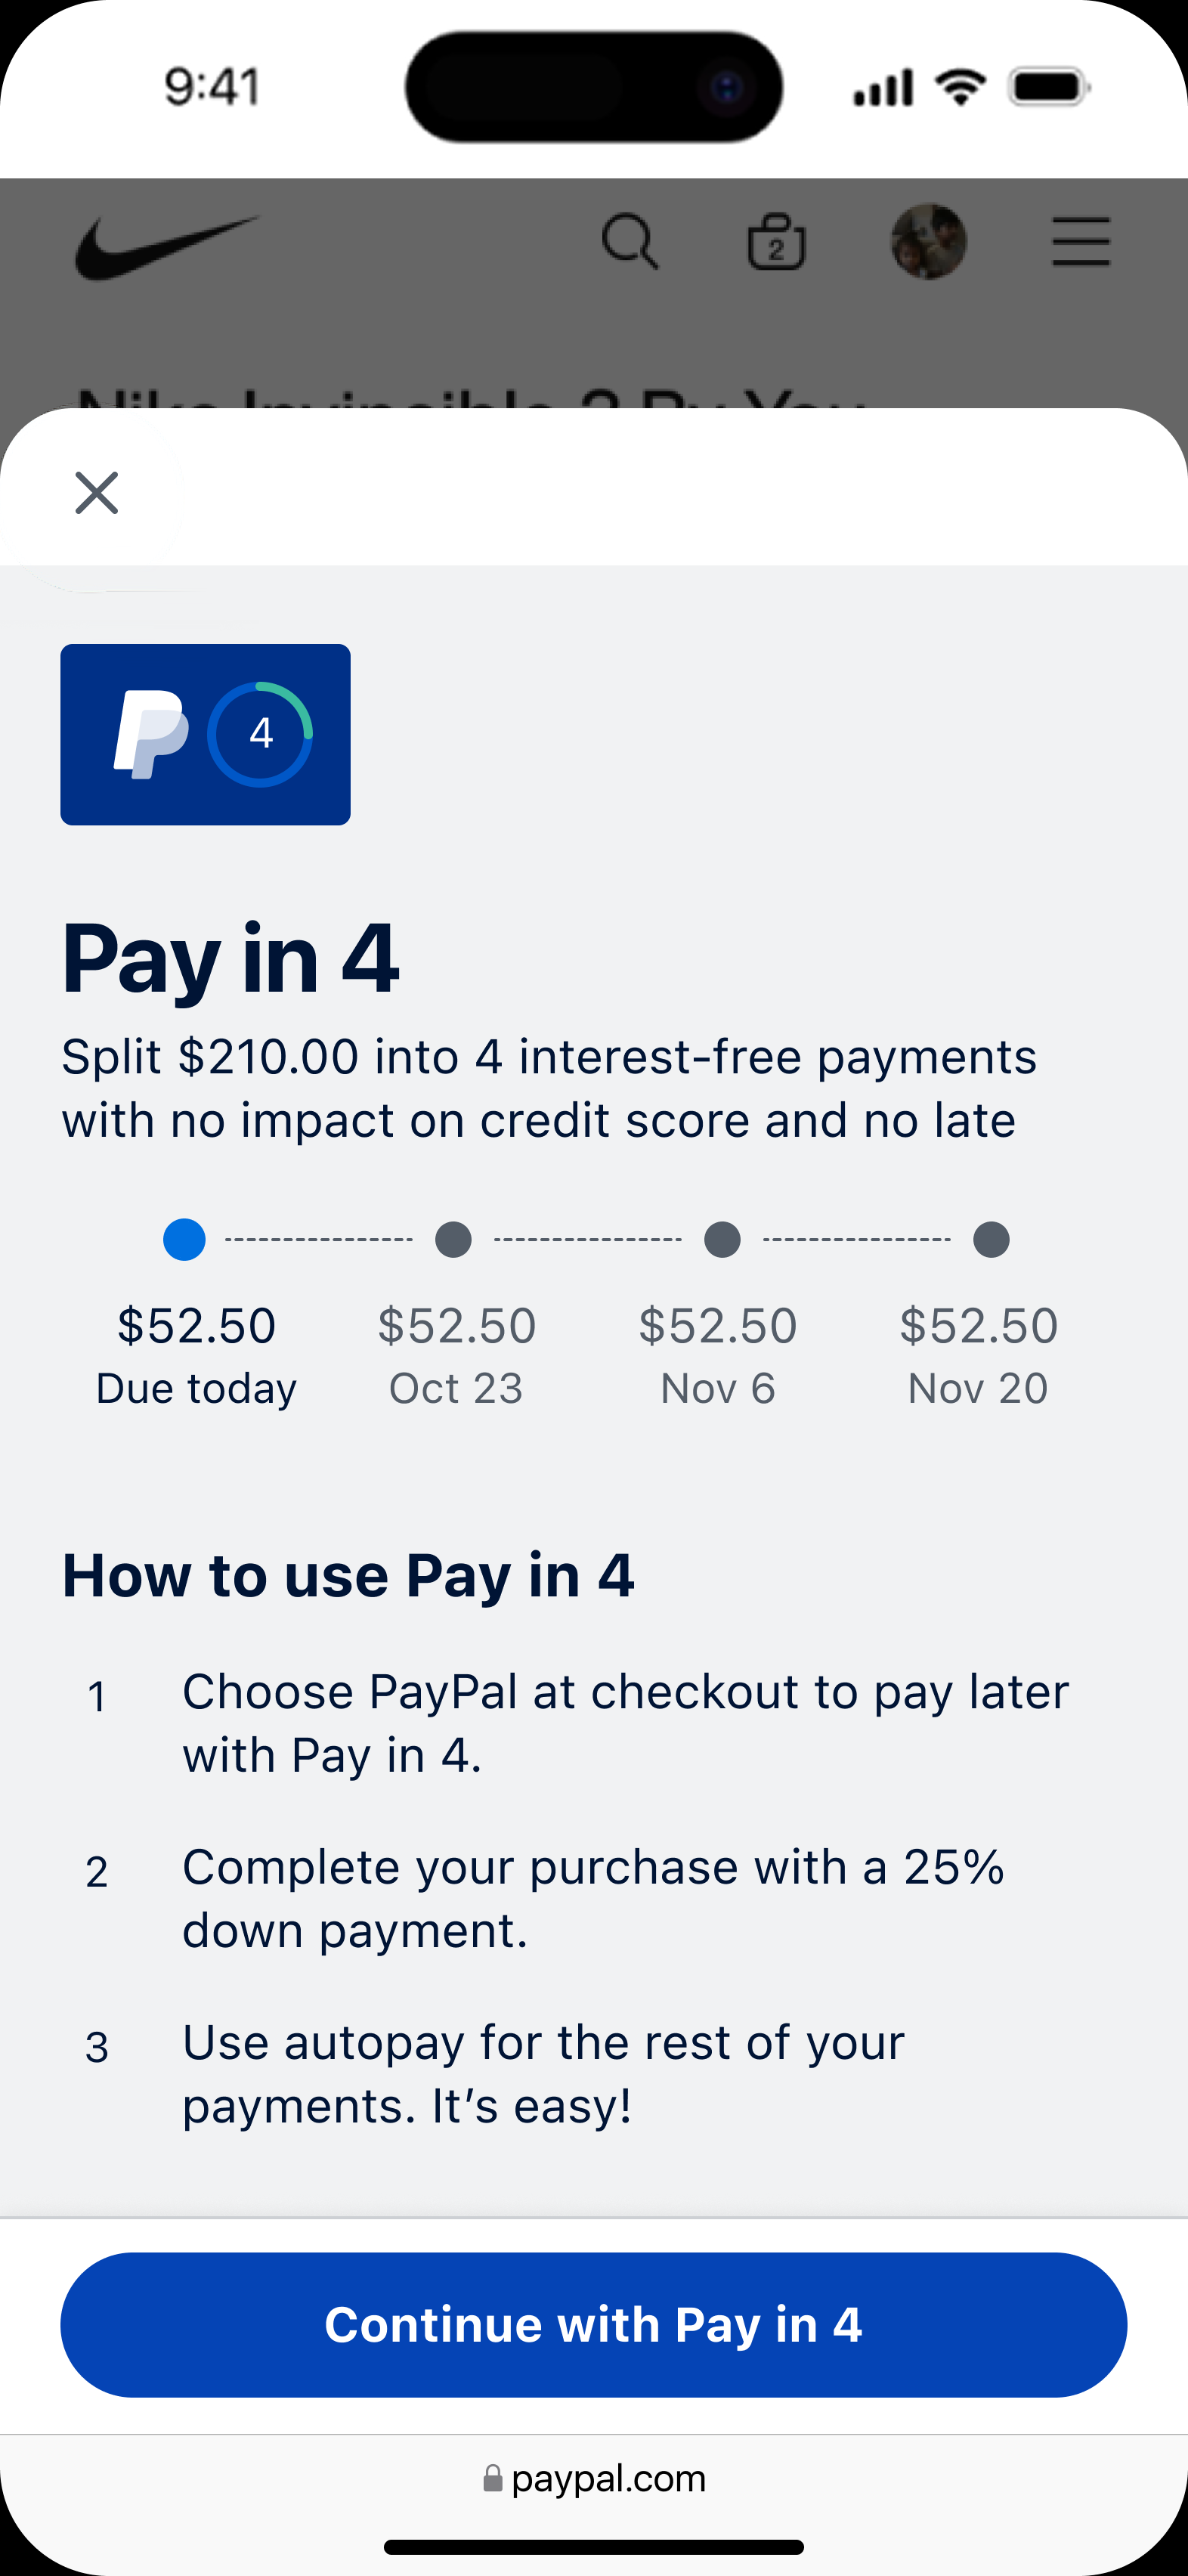
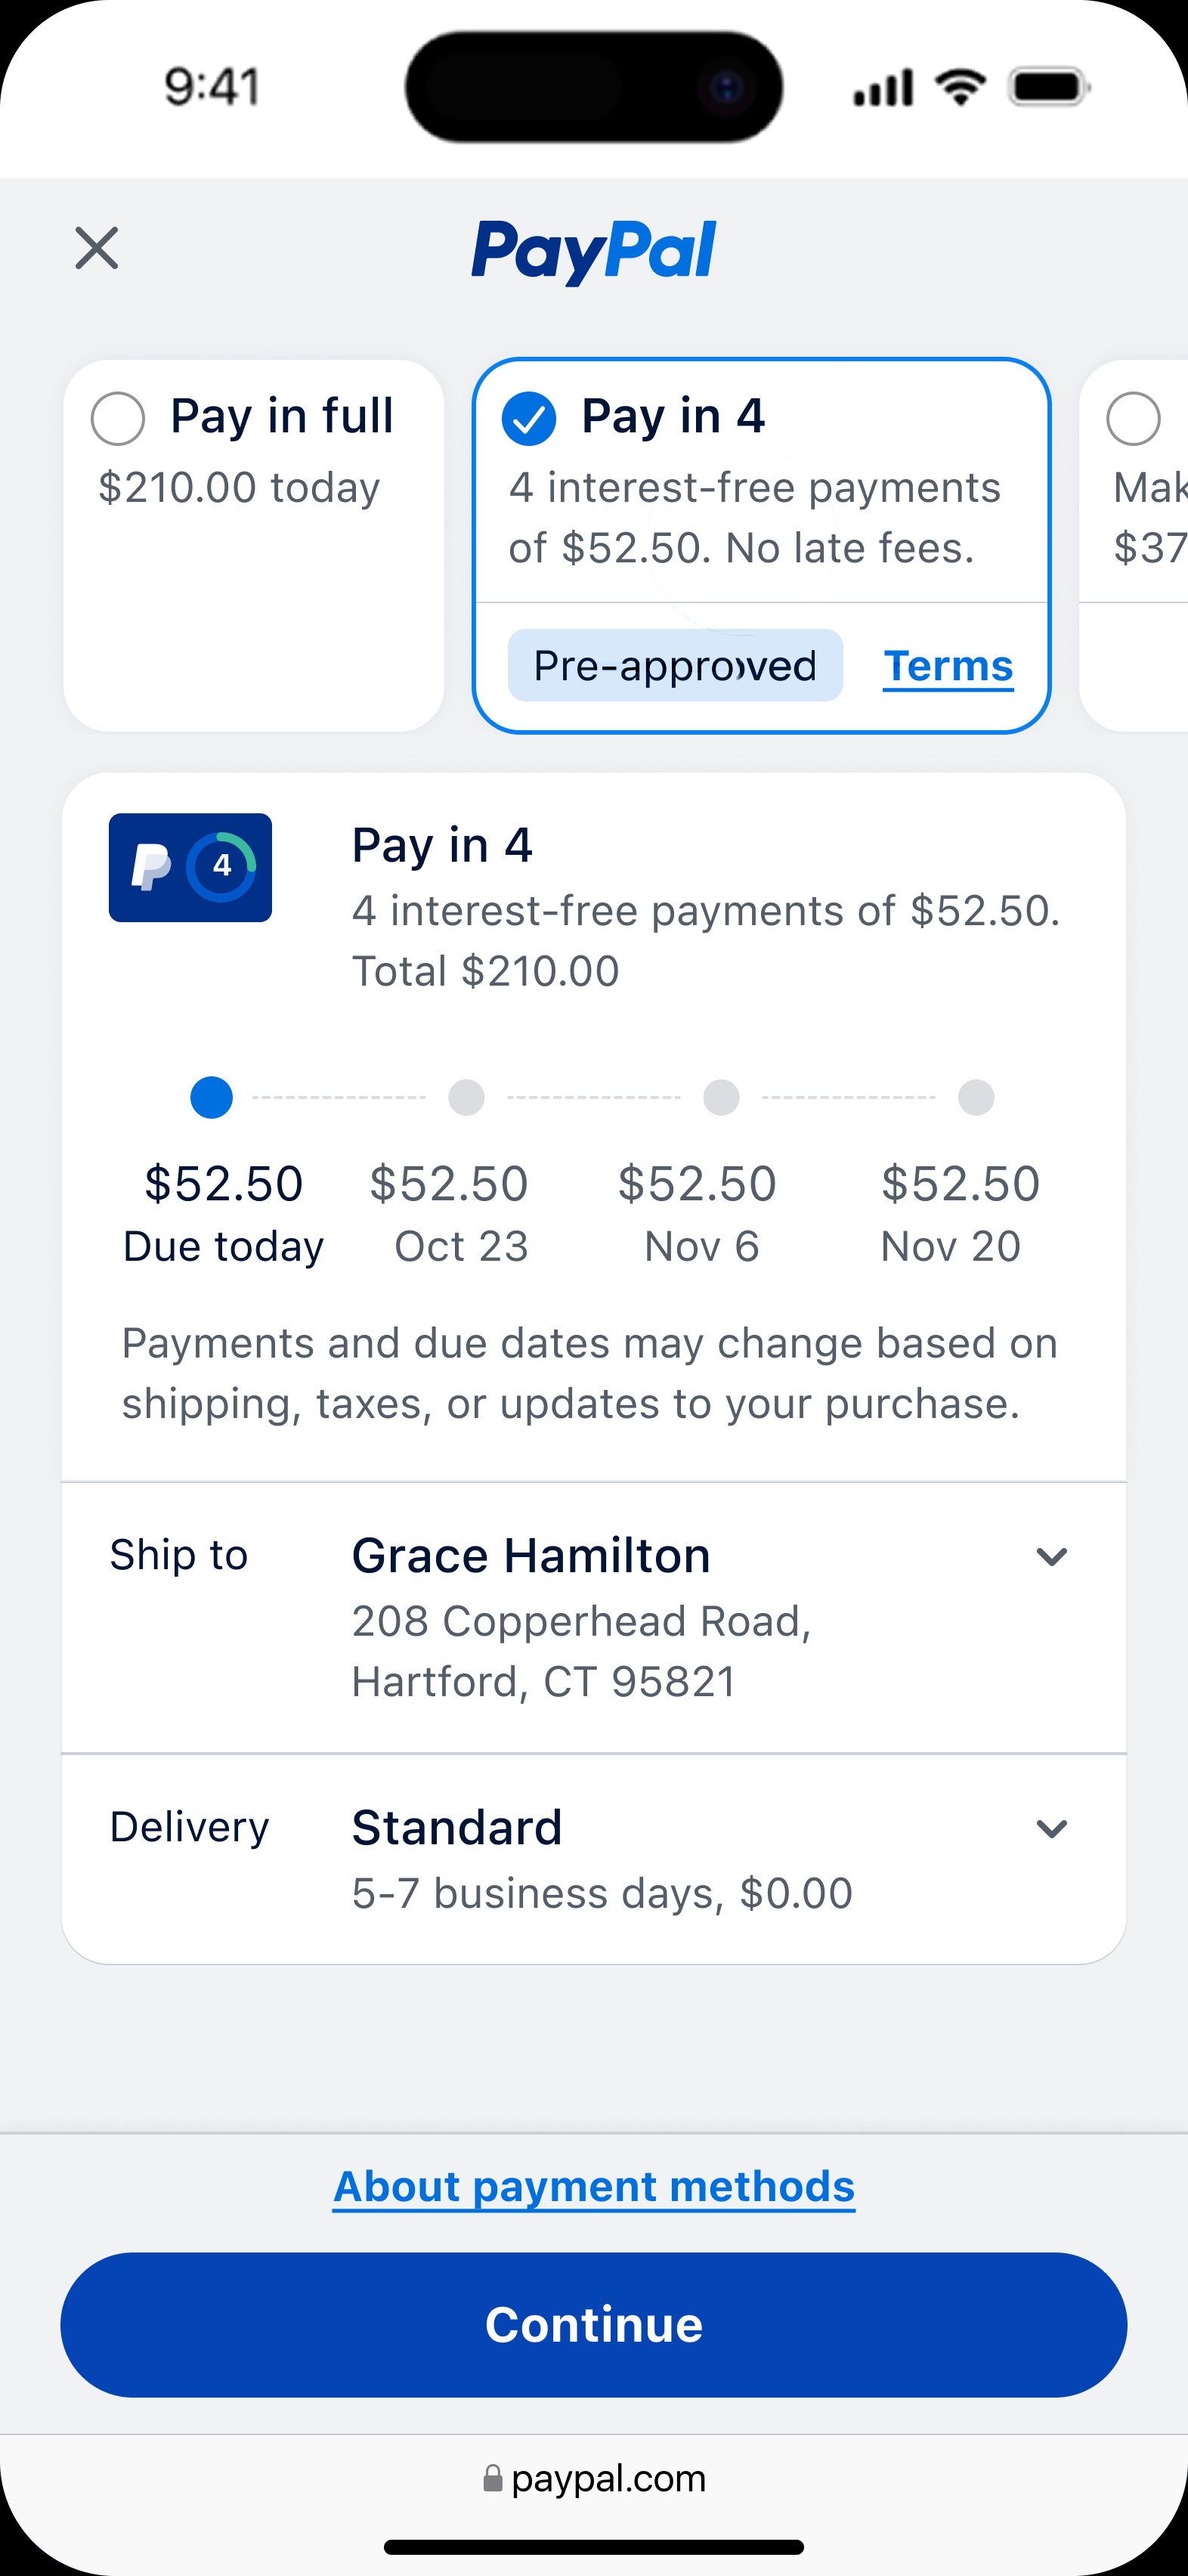
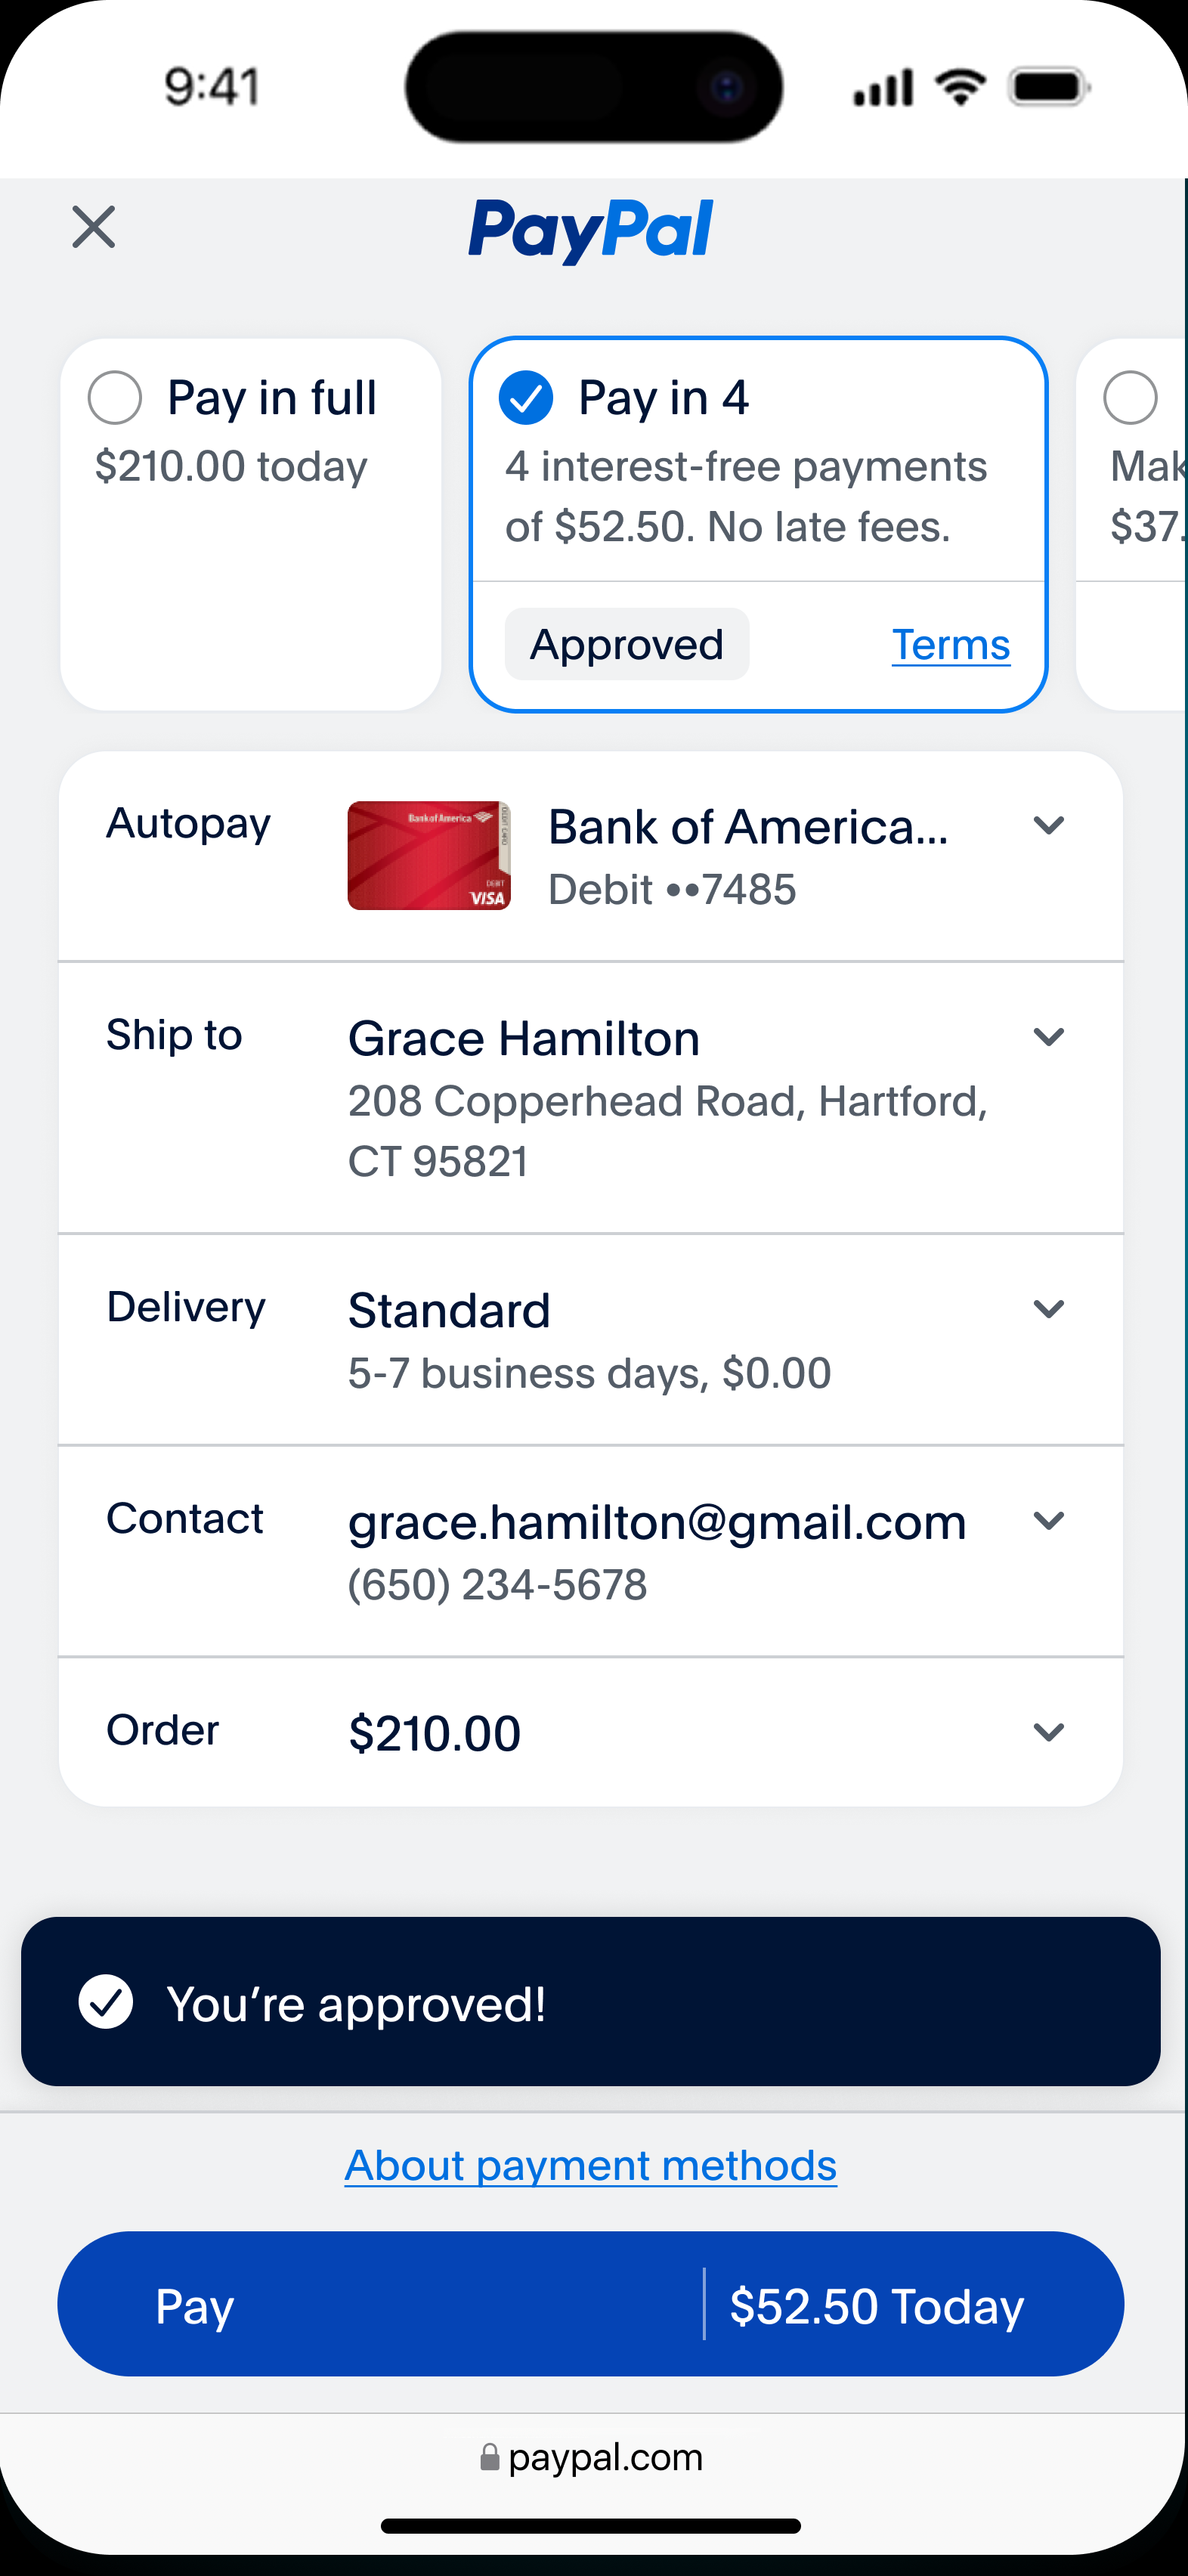
Pay in 4 made the shared problem clearest: three application steps separated product choice from purchase completion.
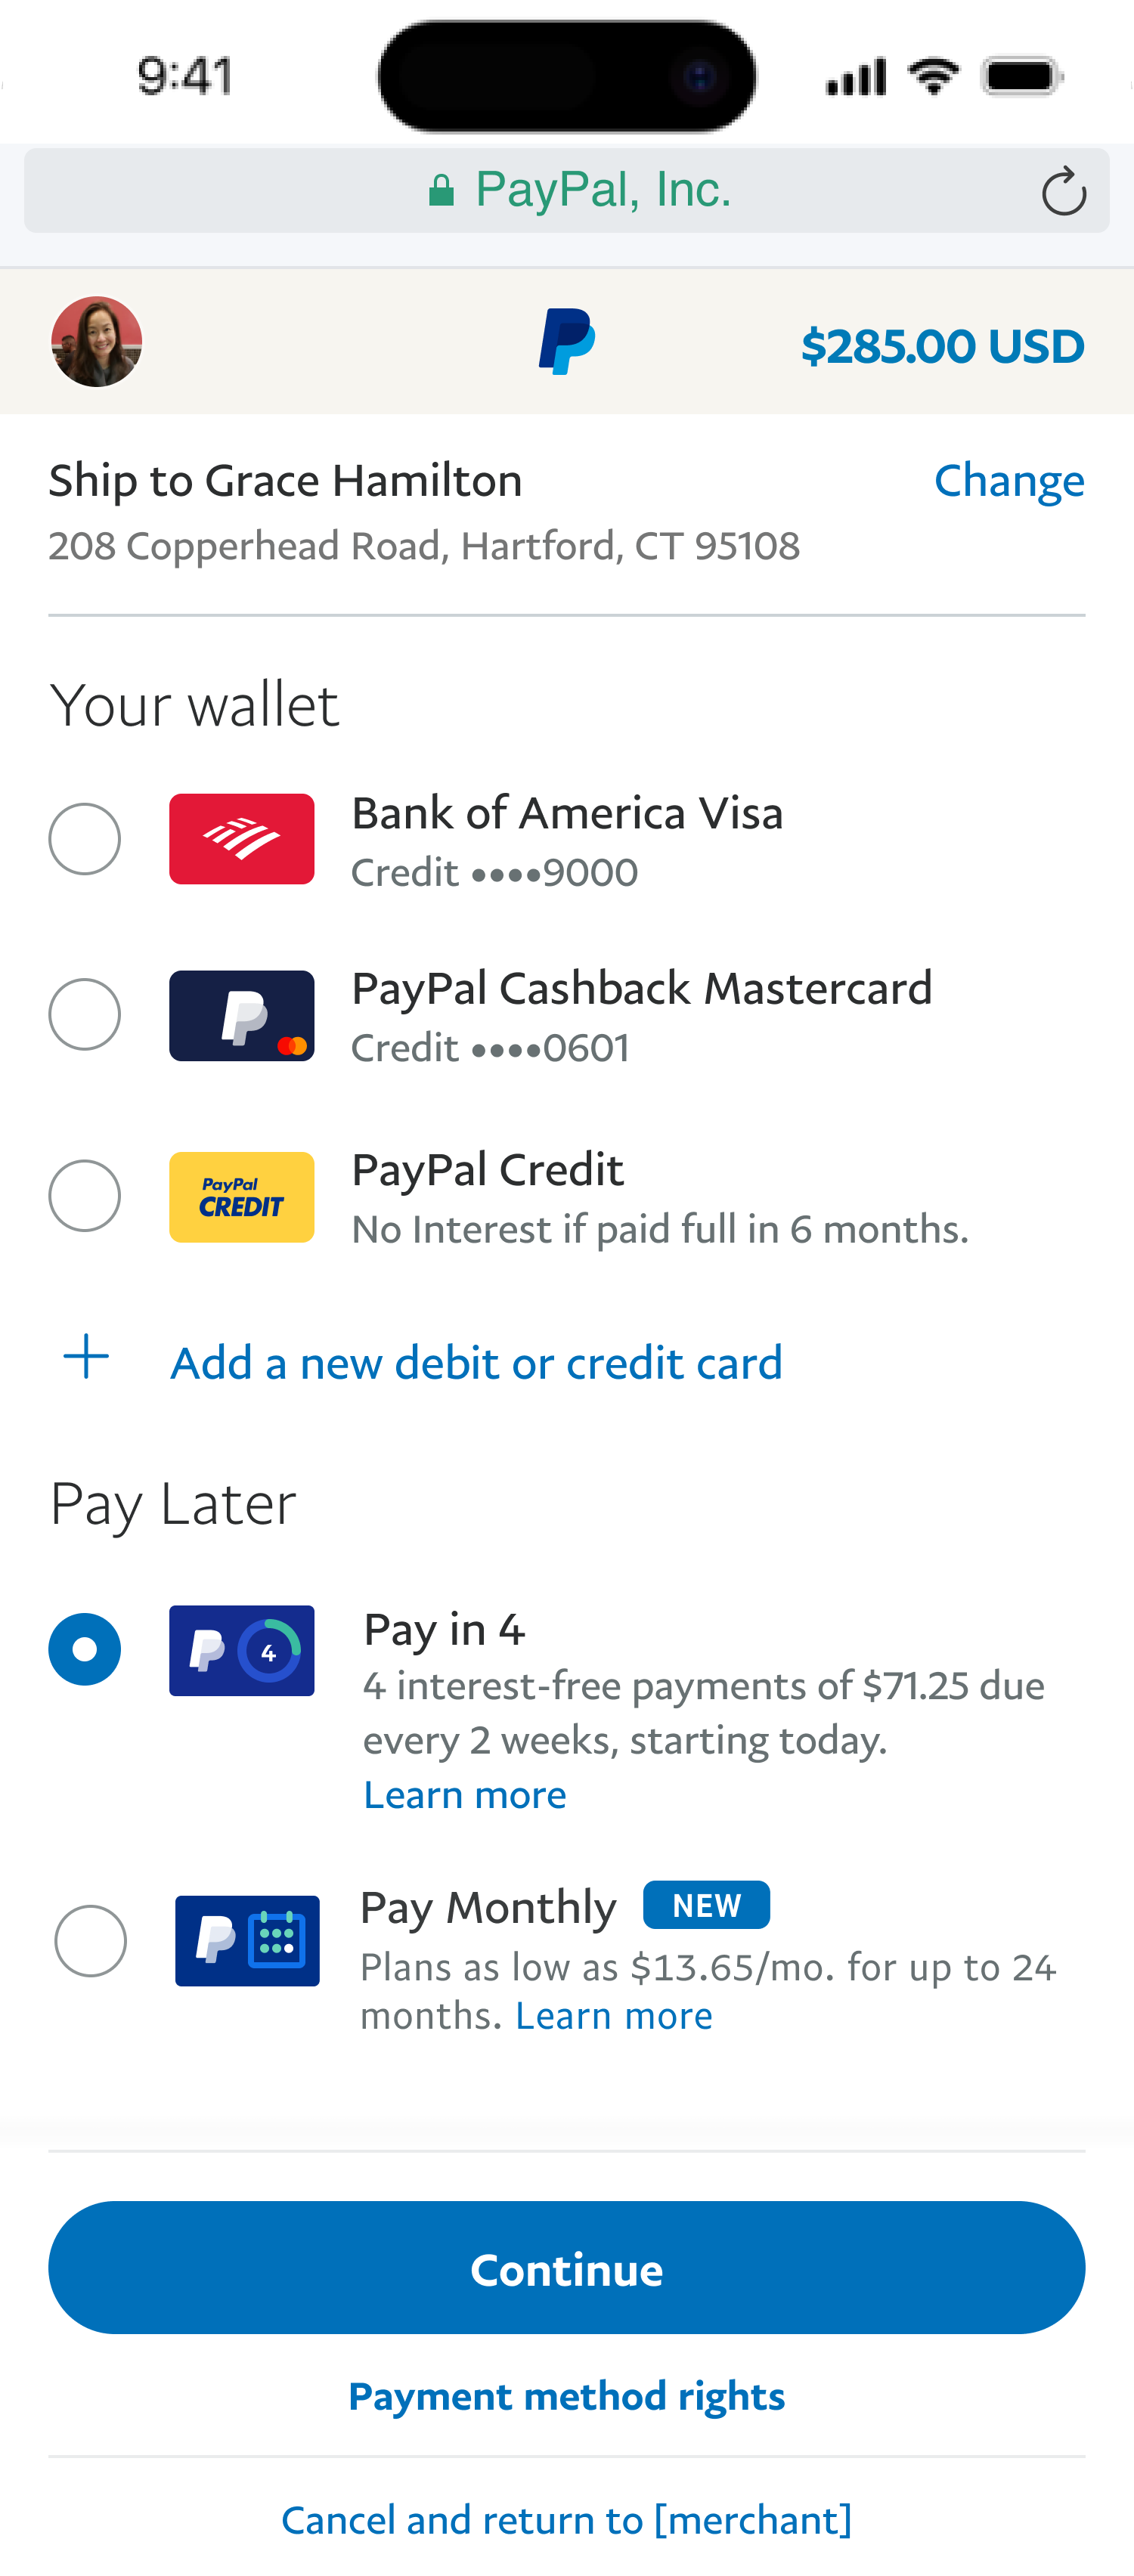
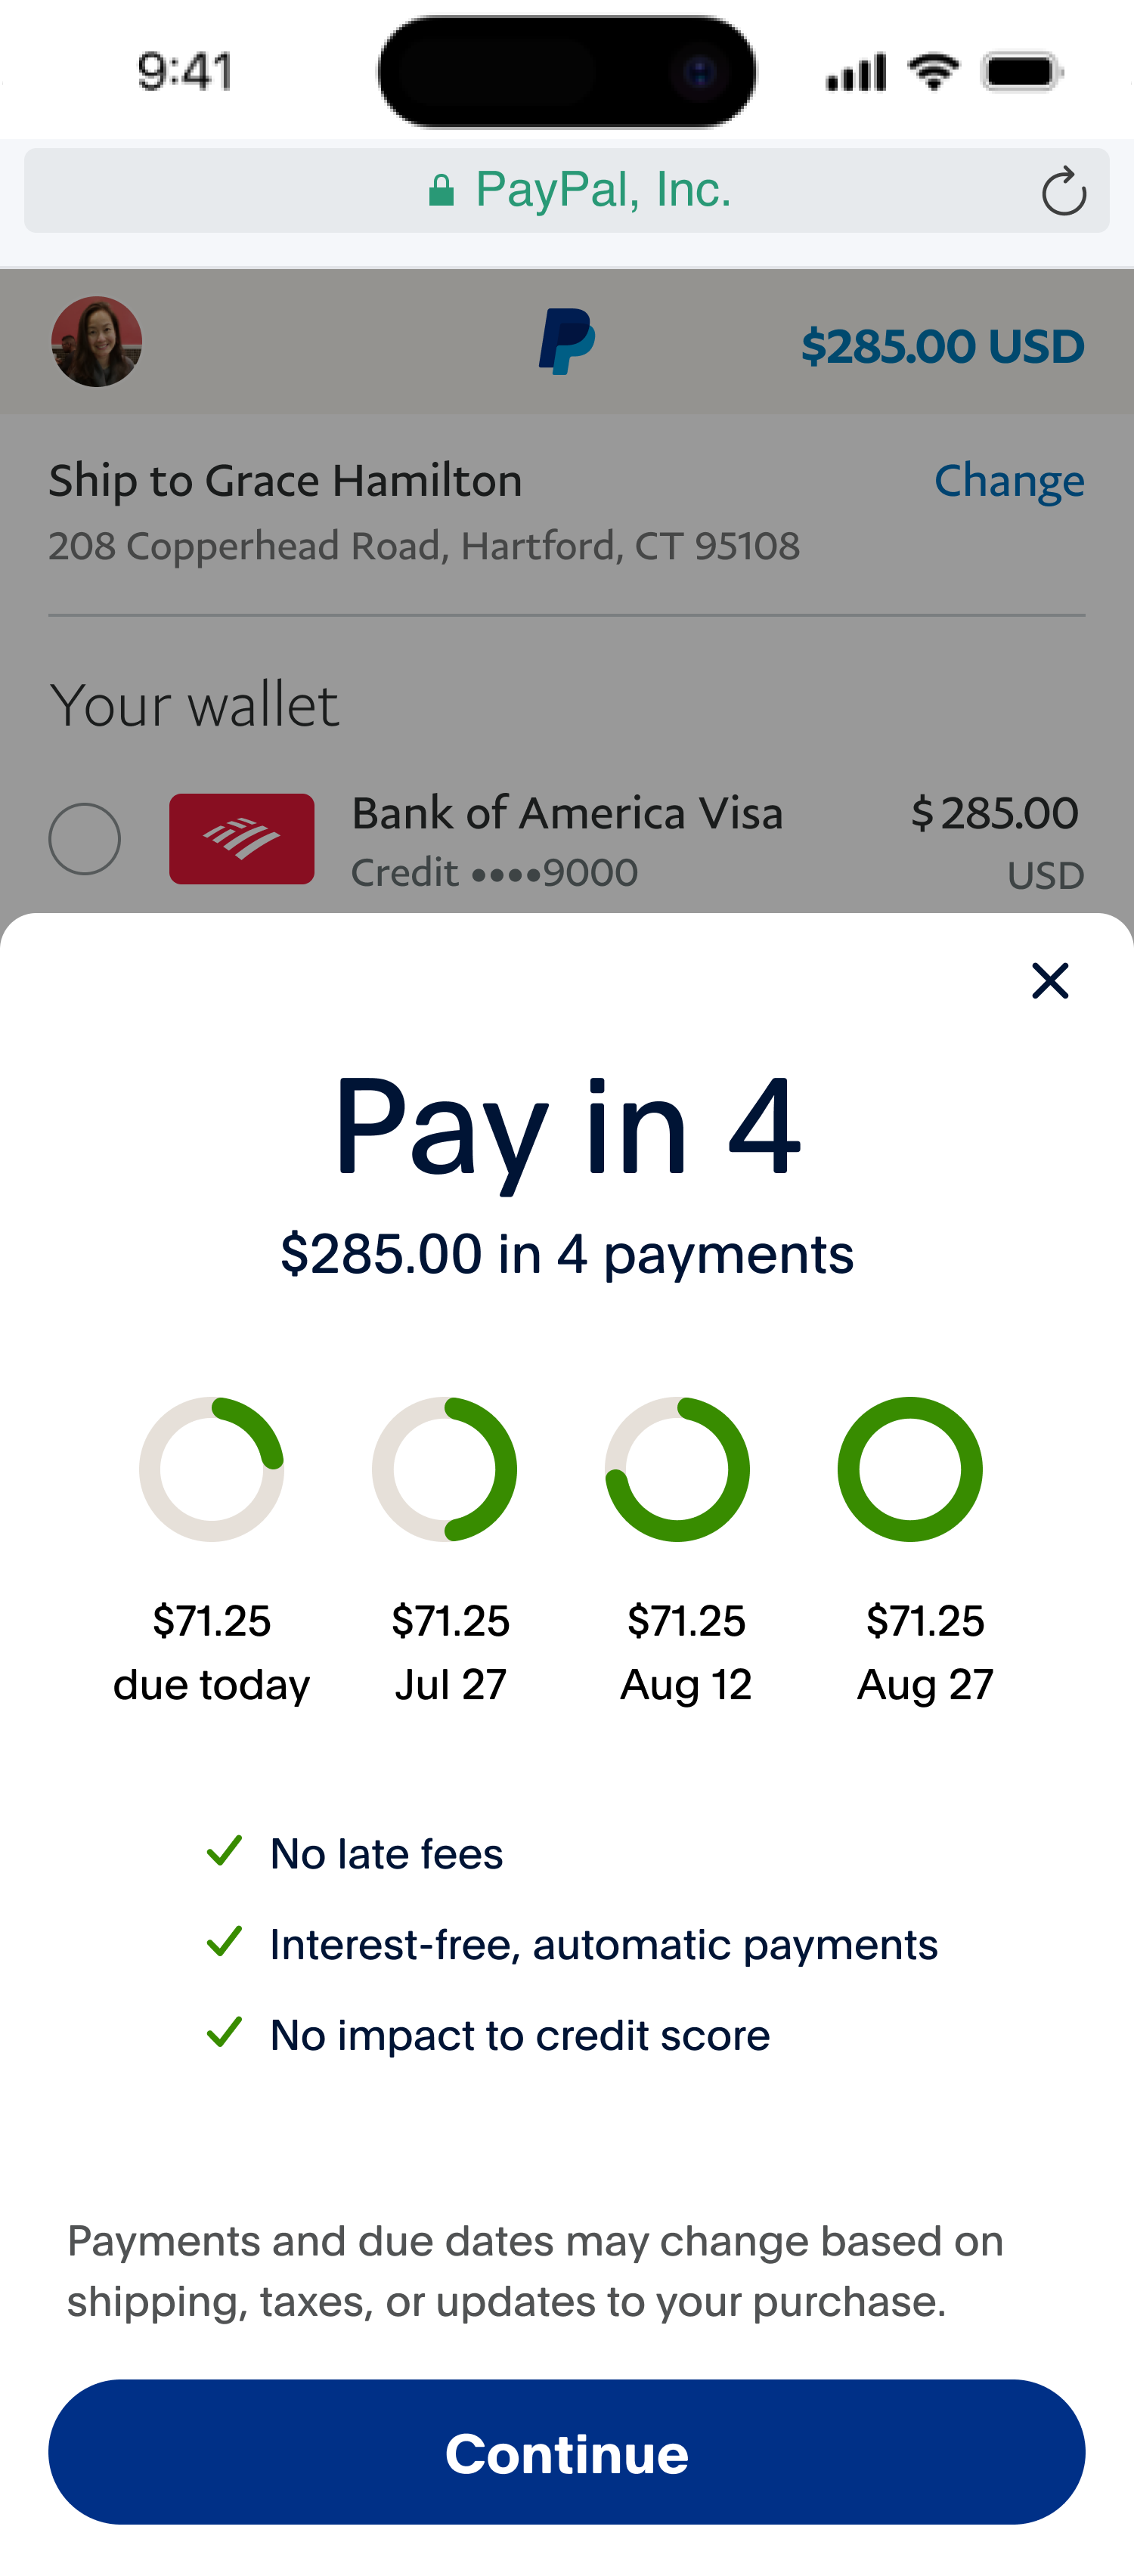
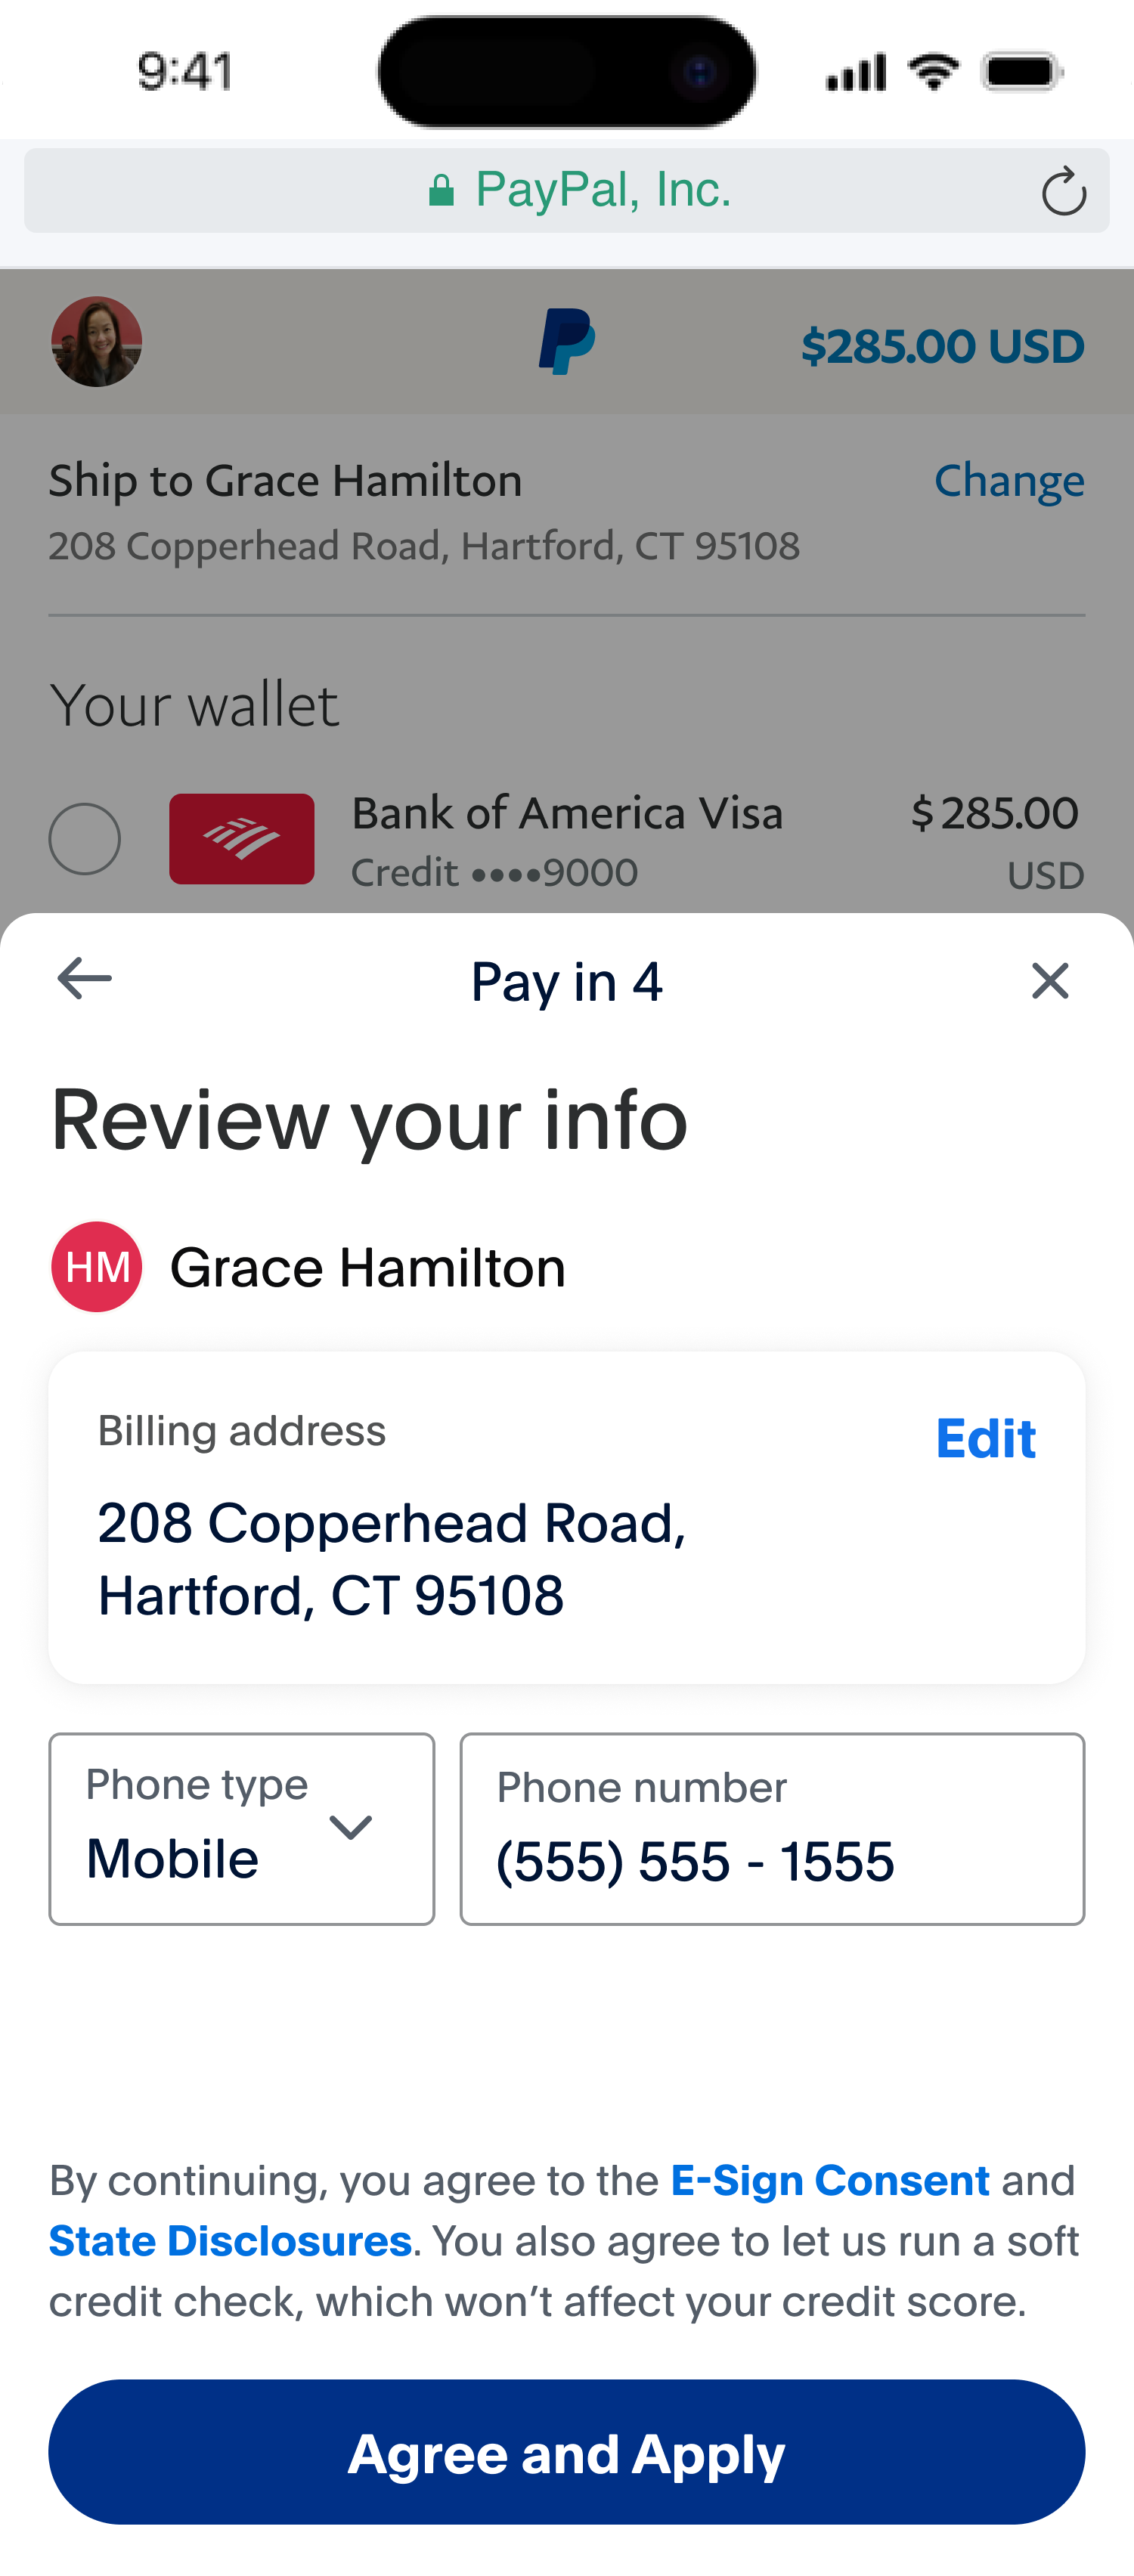
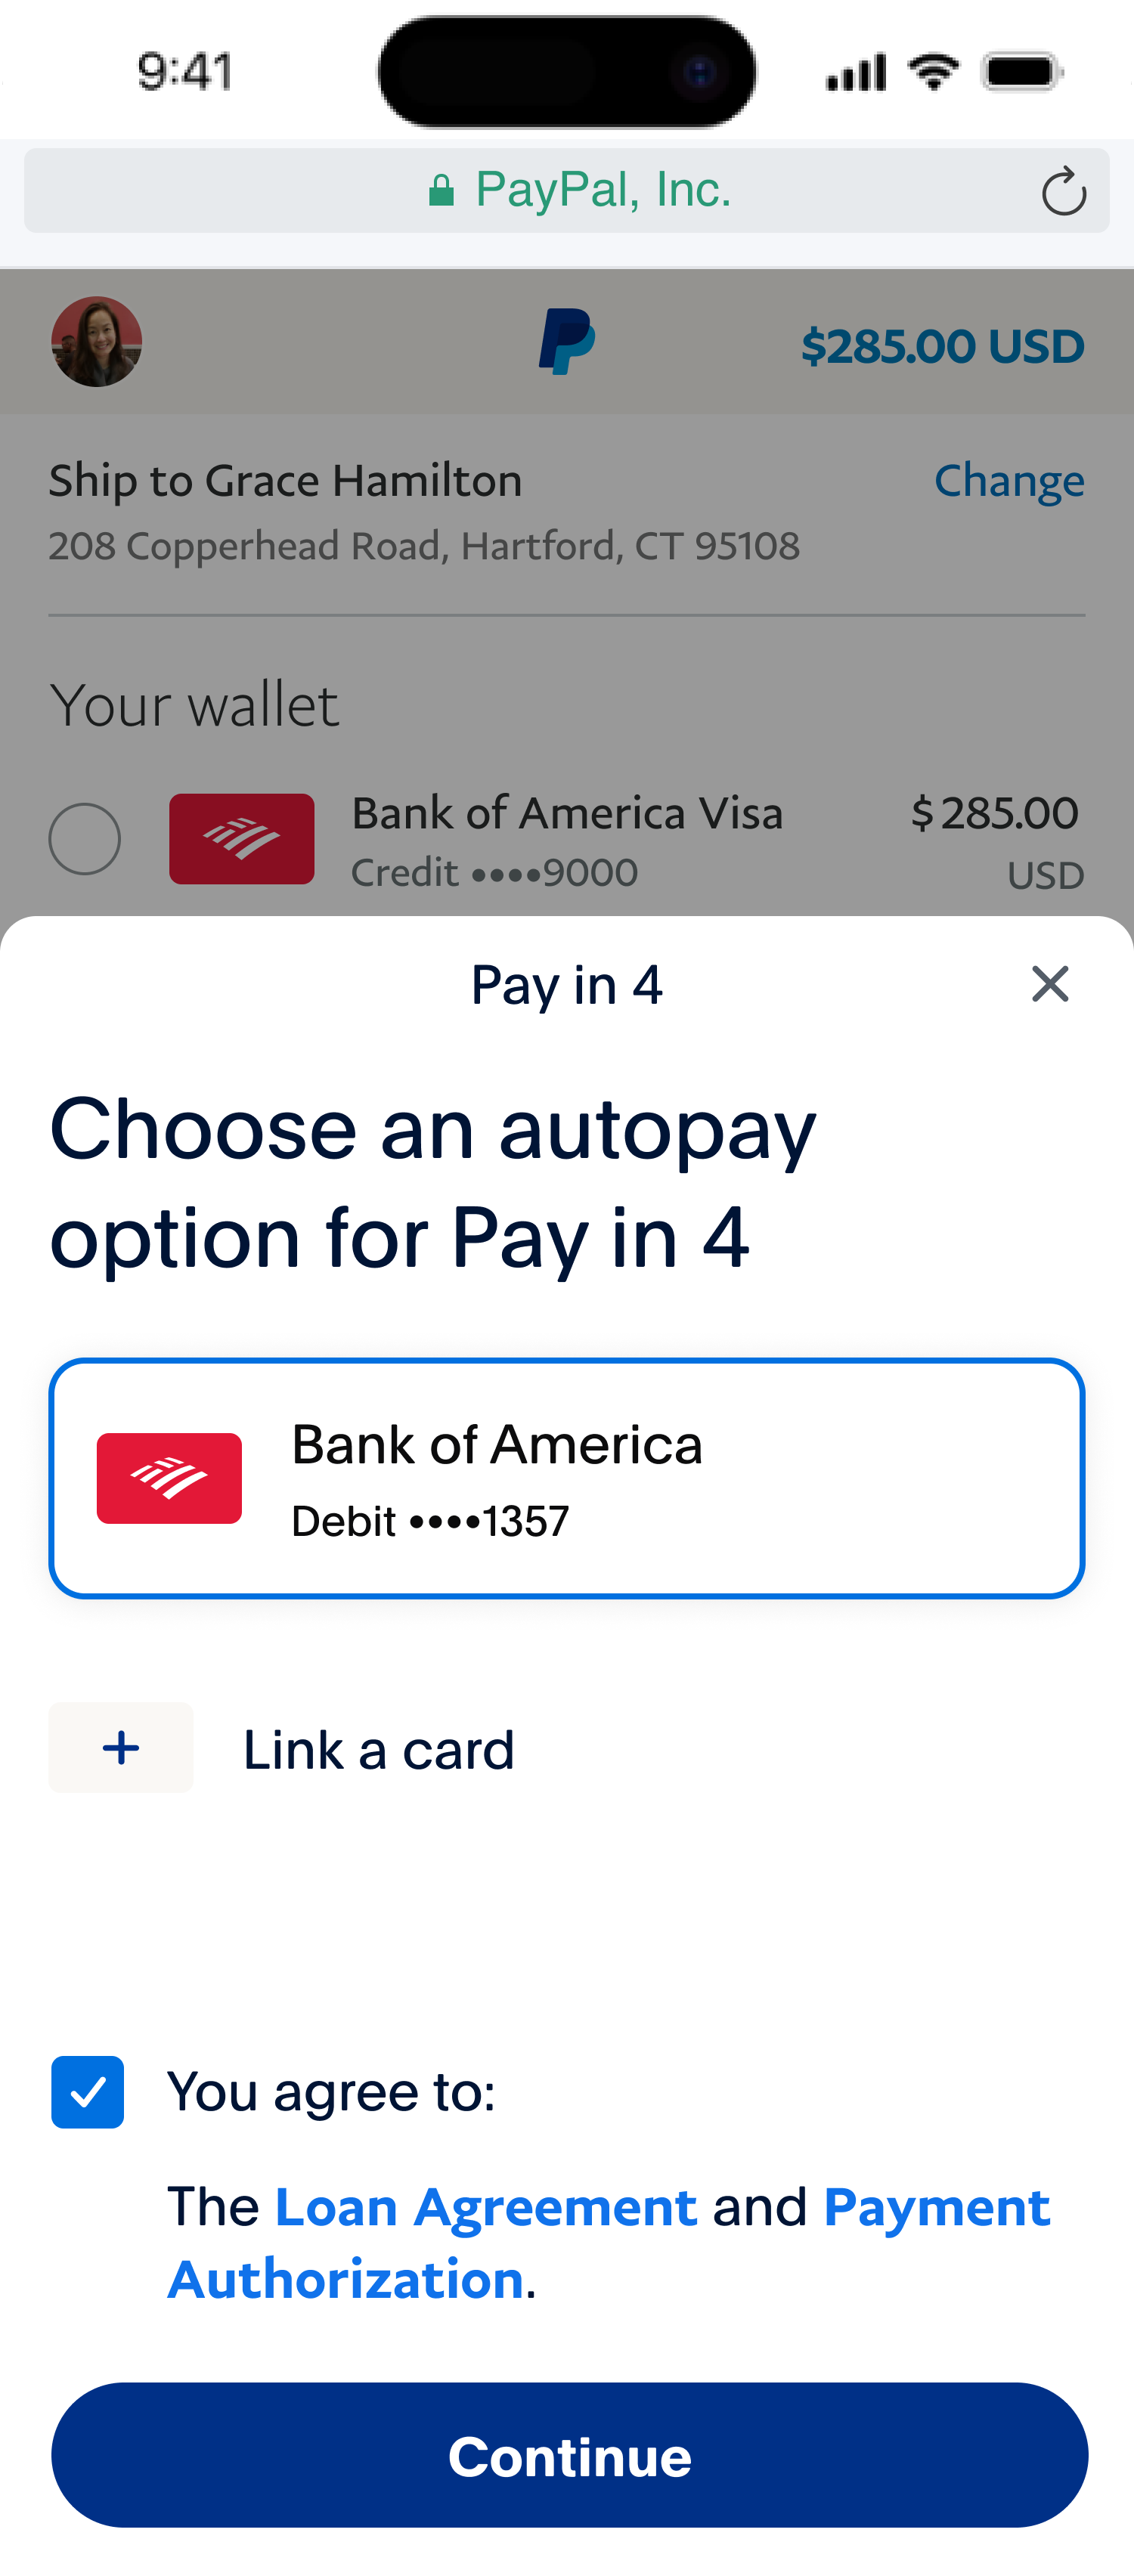
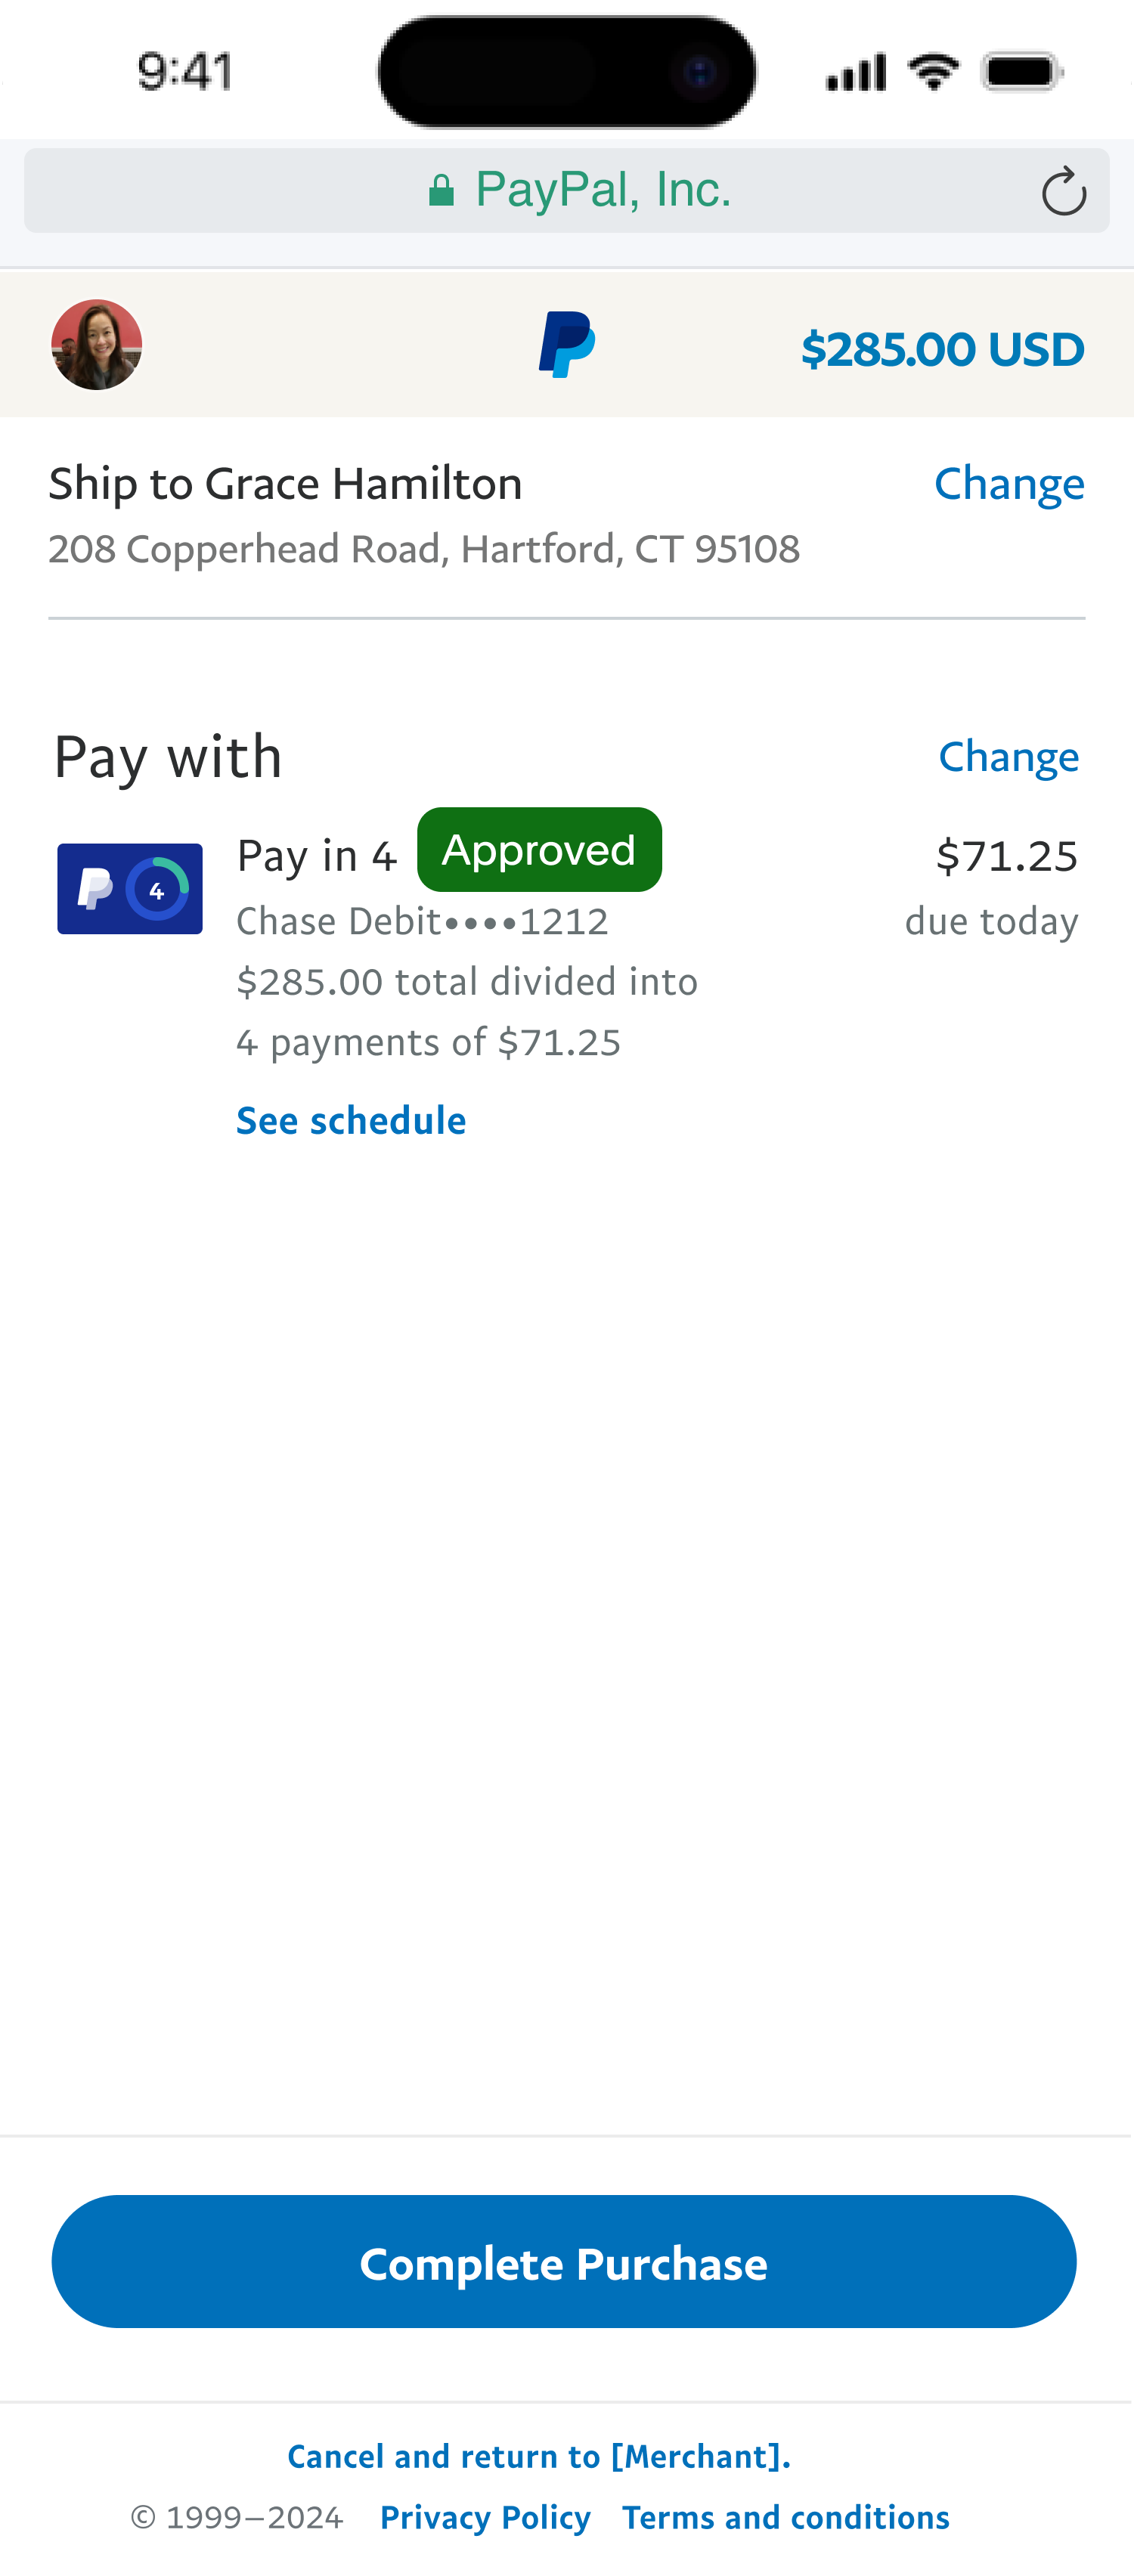
One page brought the decision back into focus.
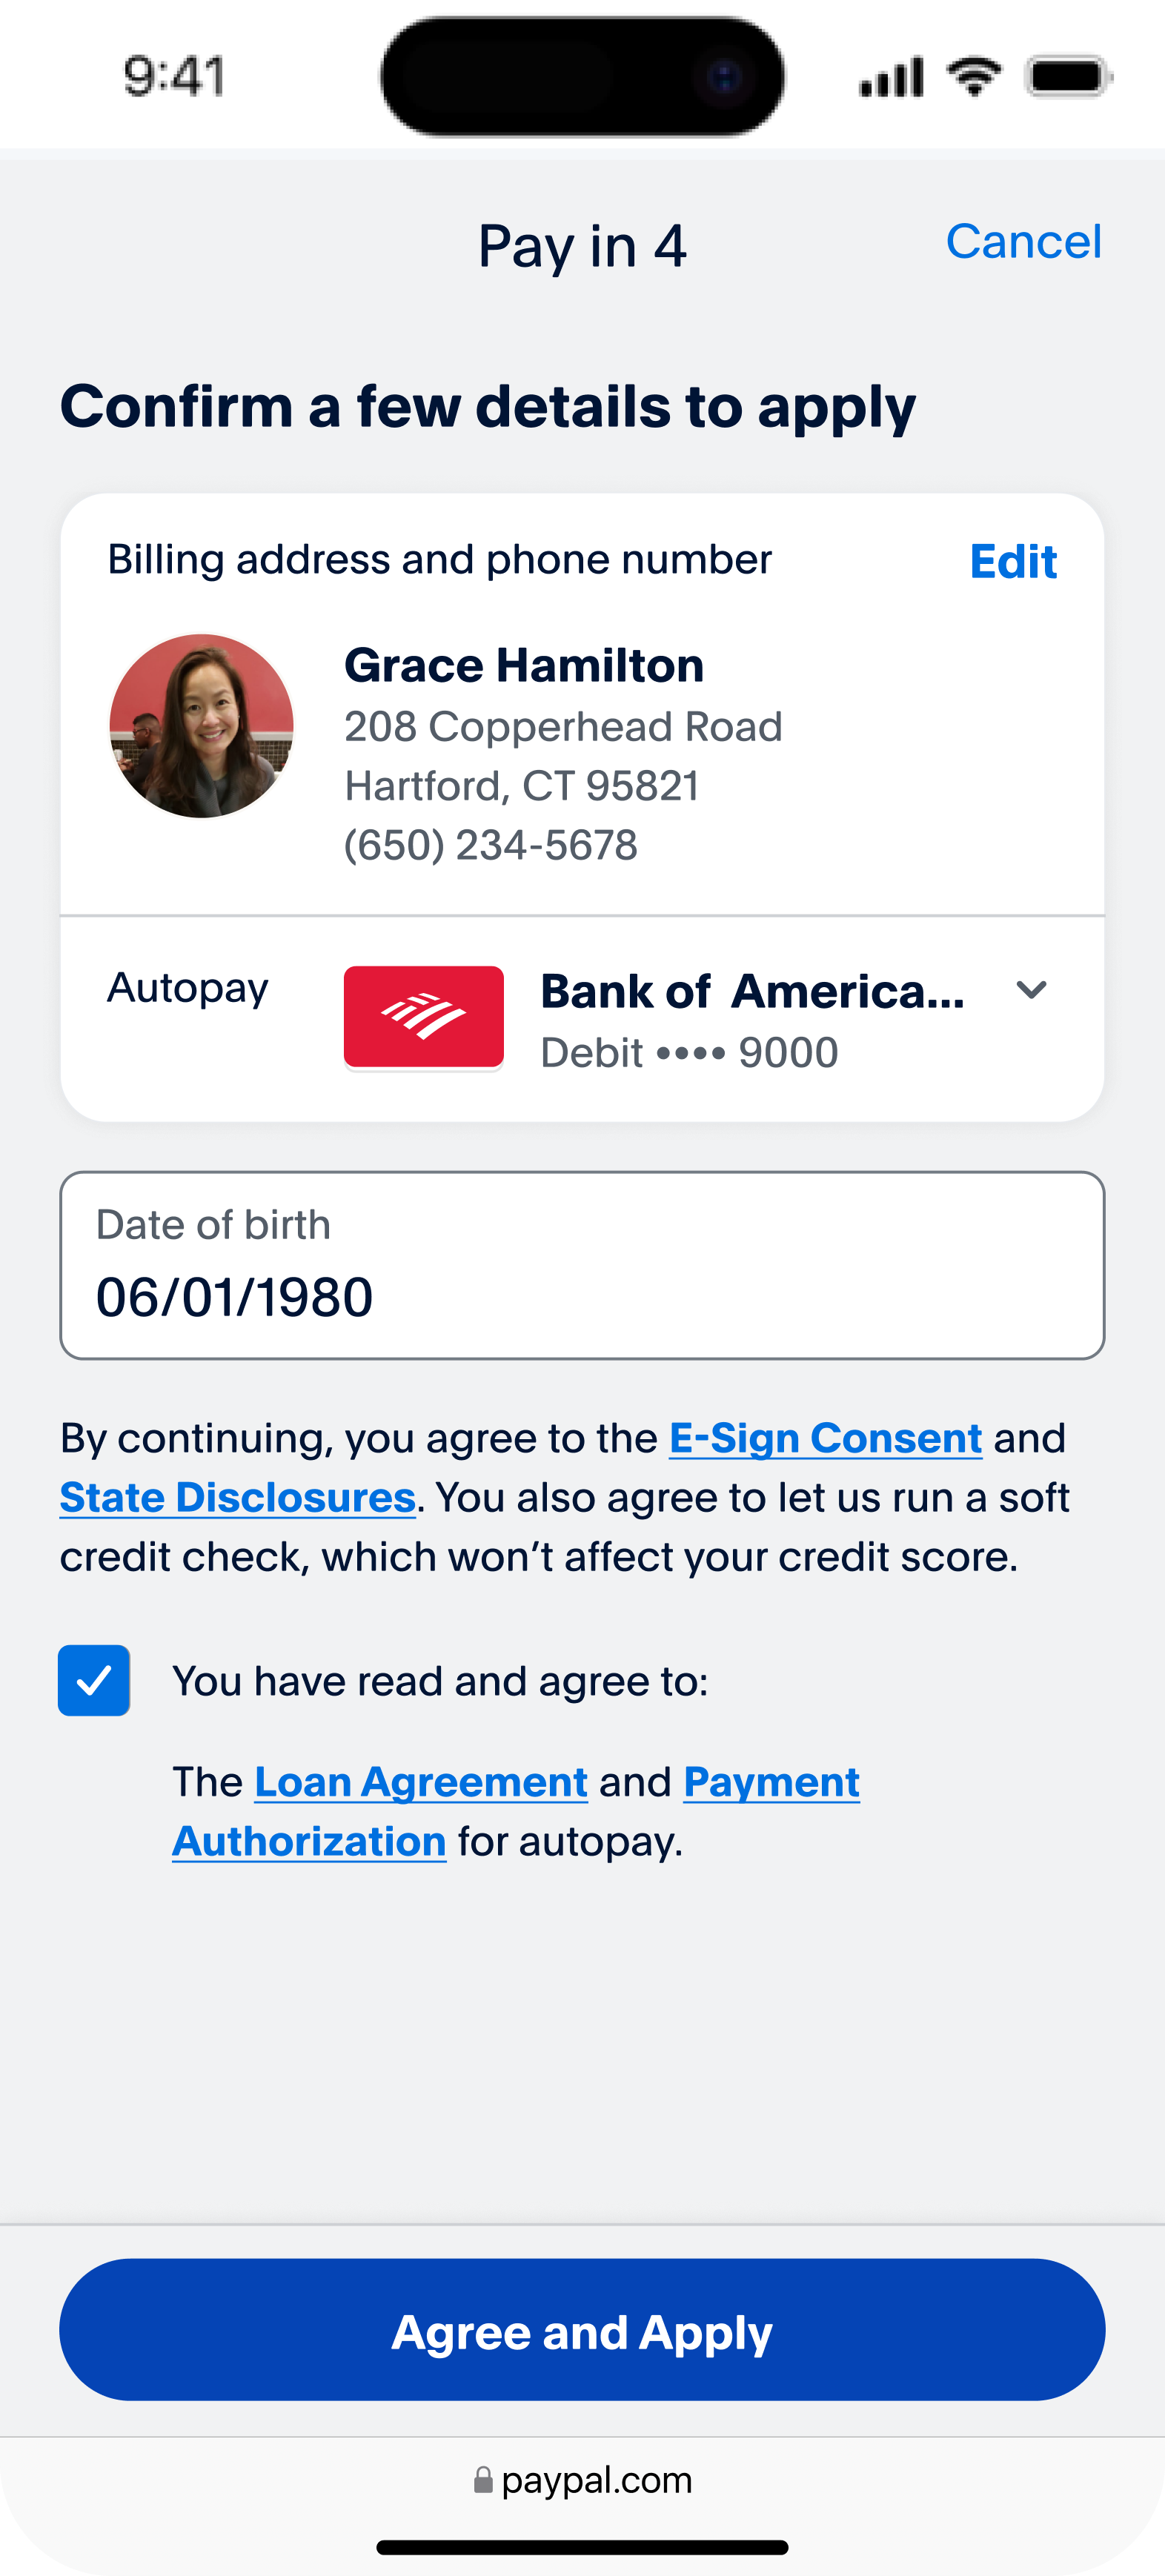
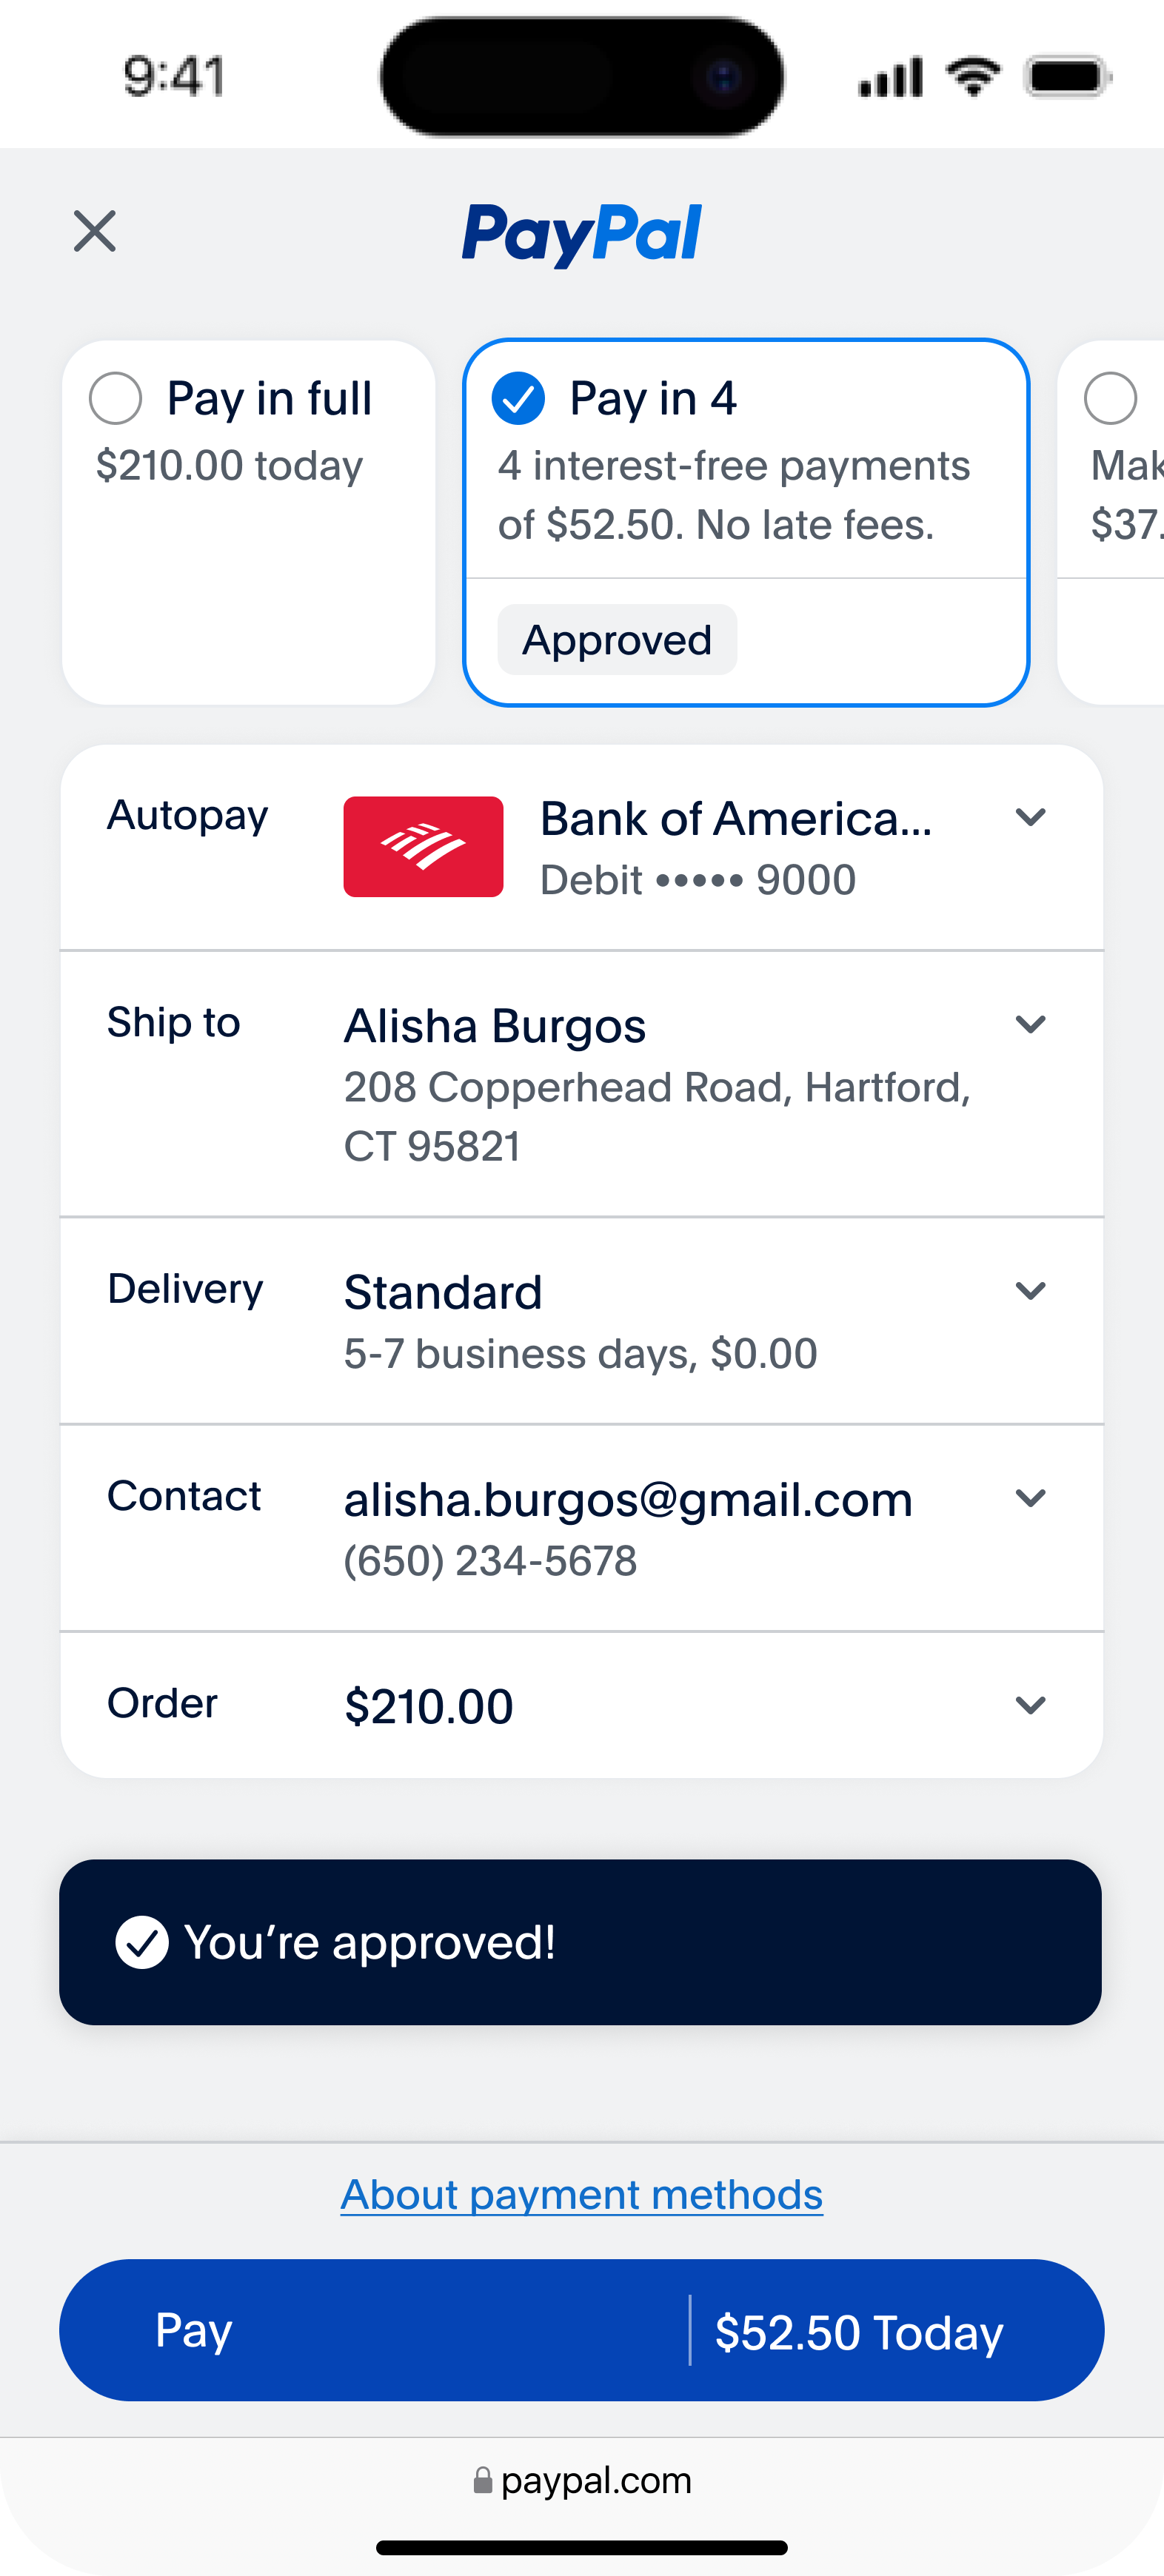
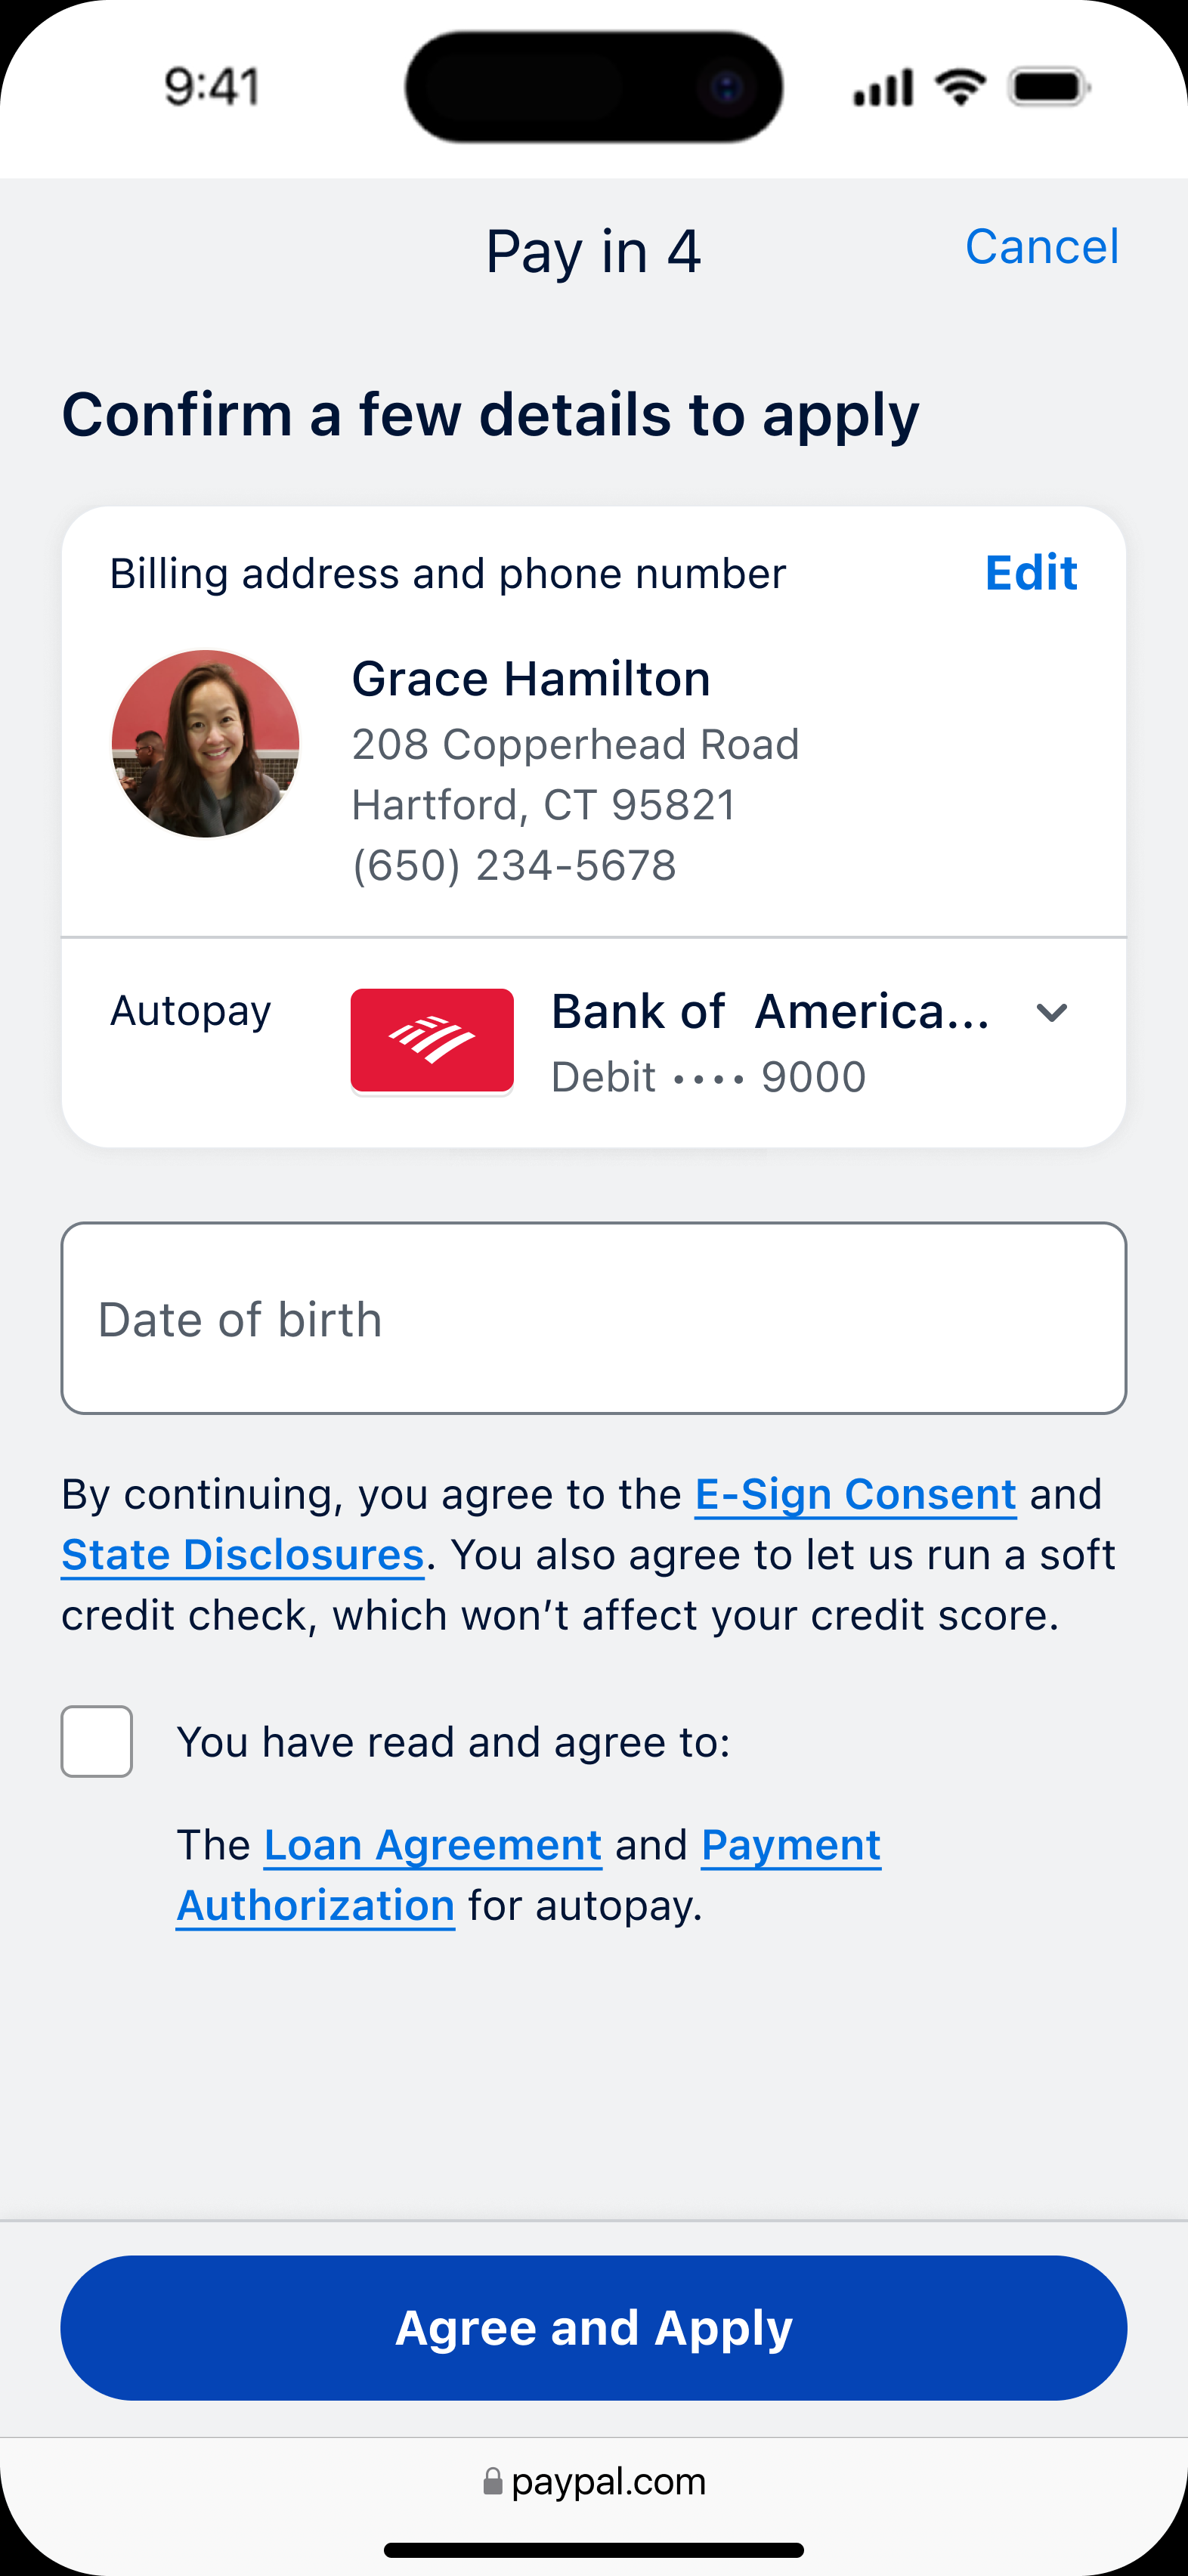
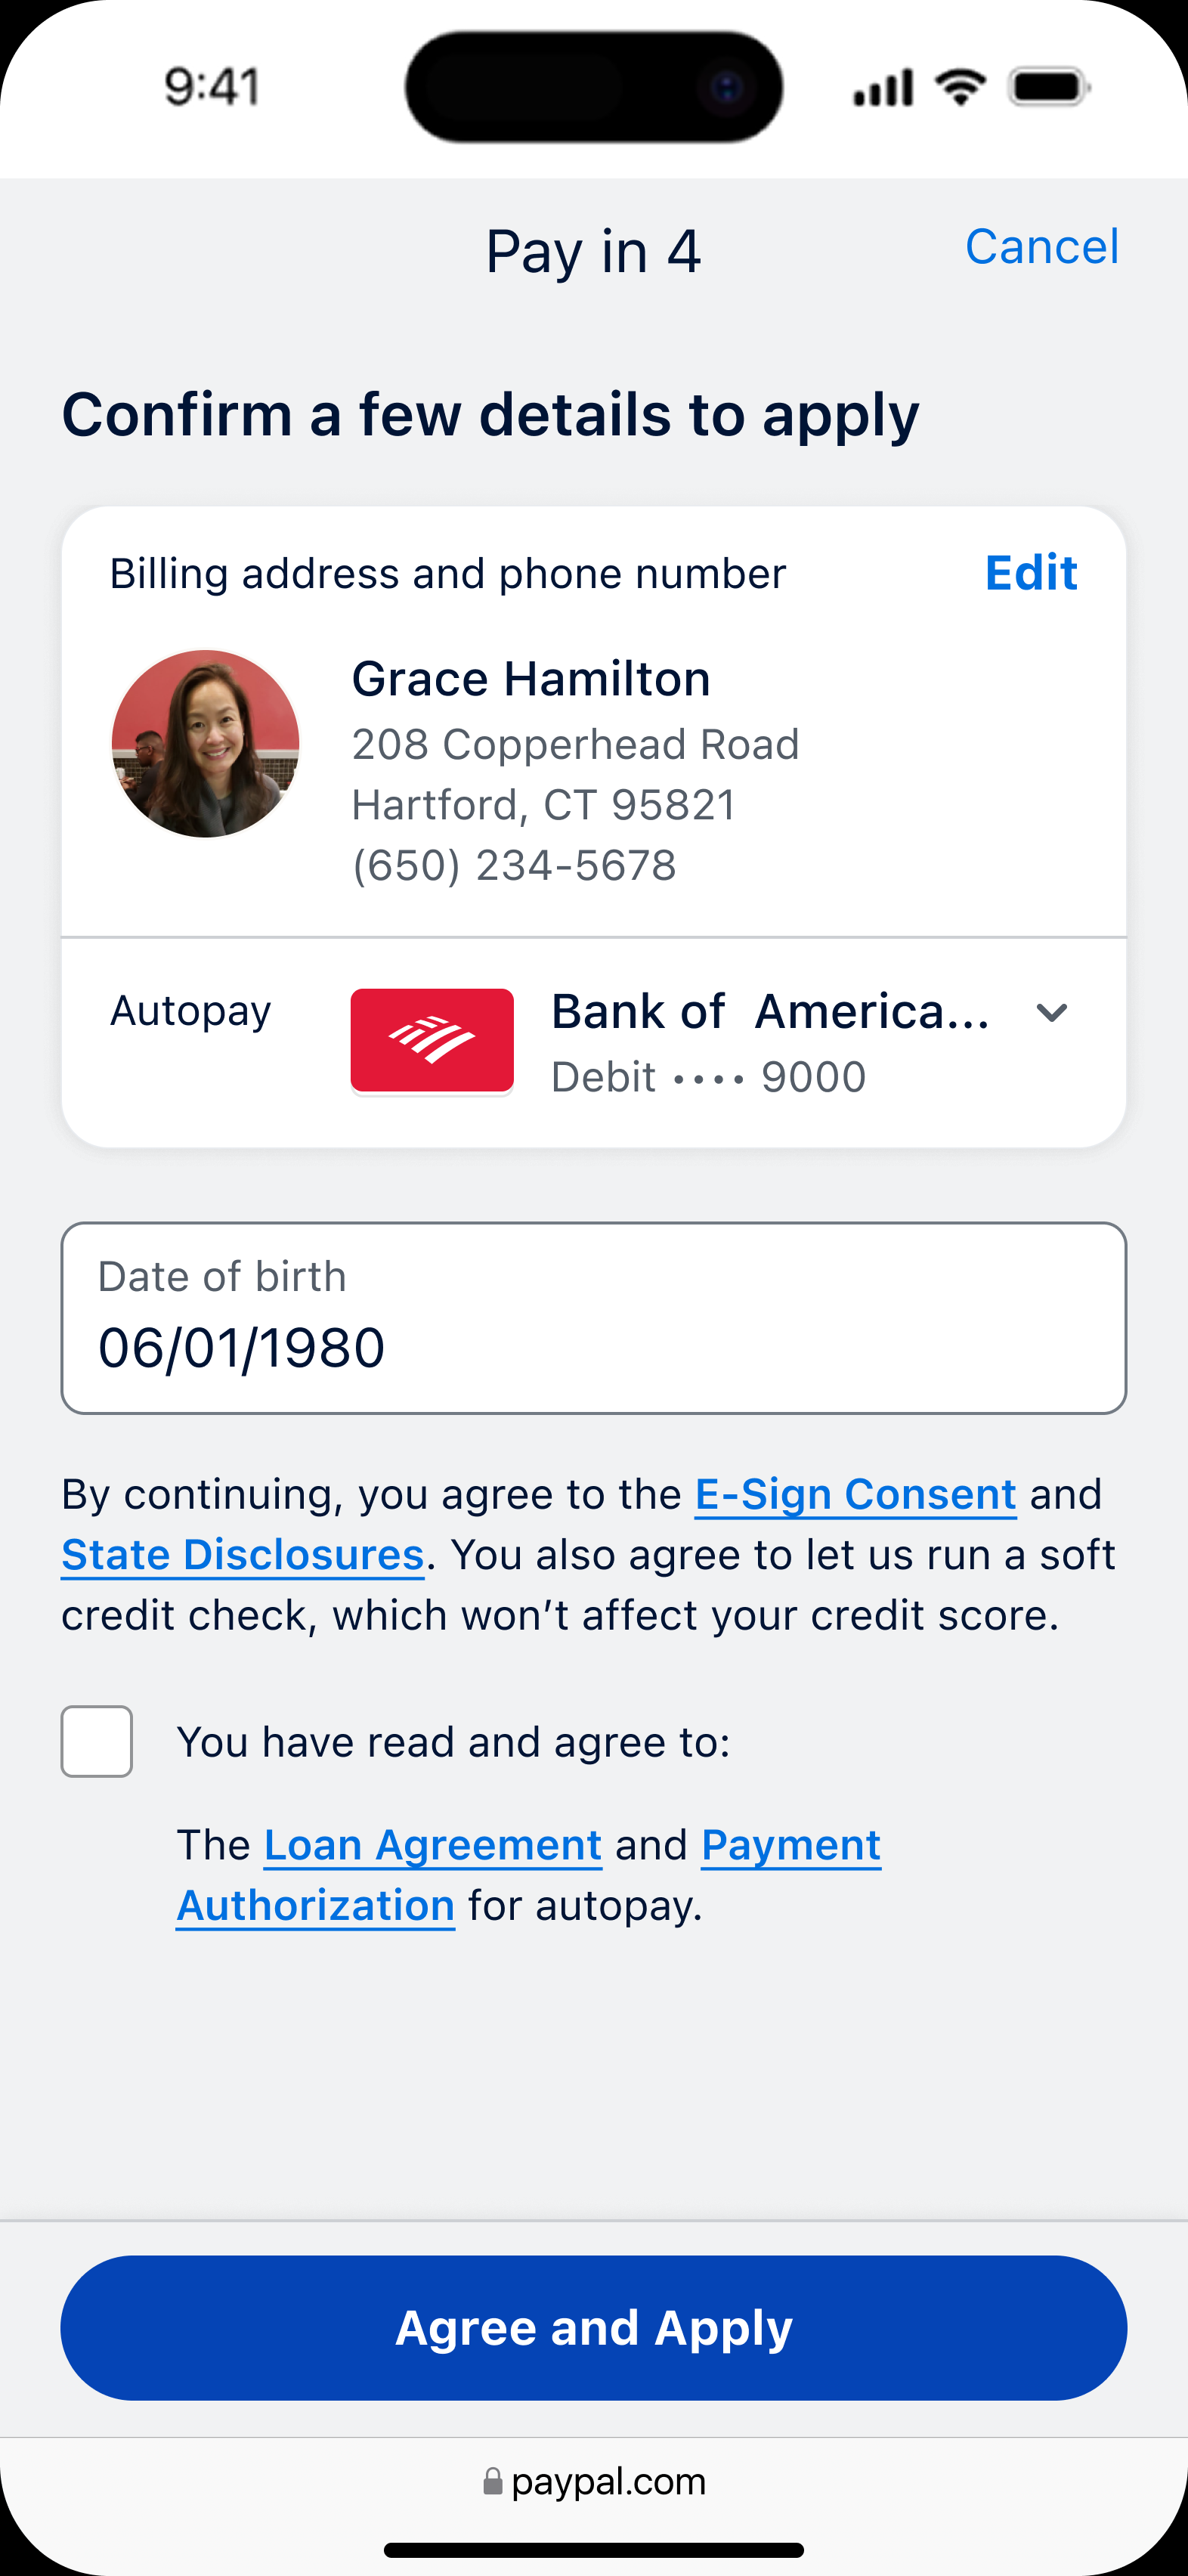
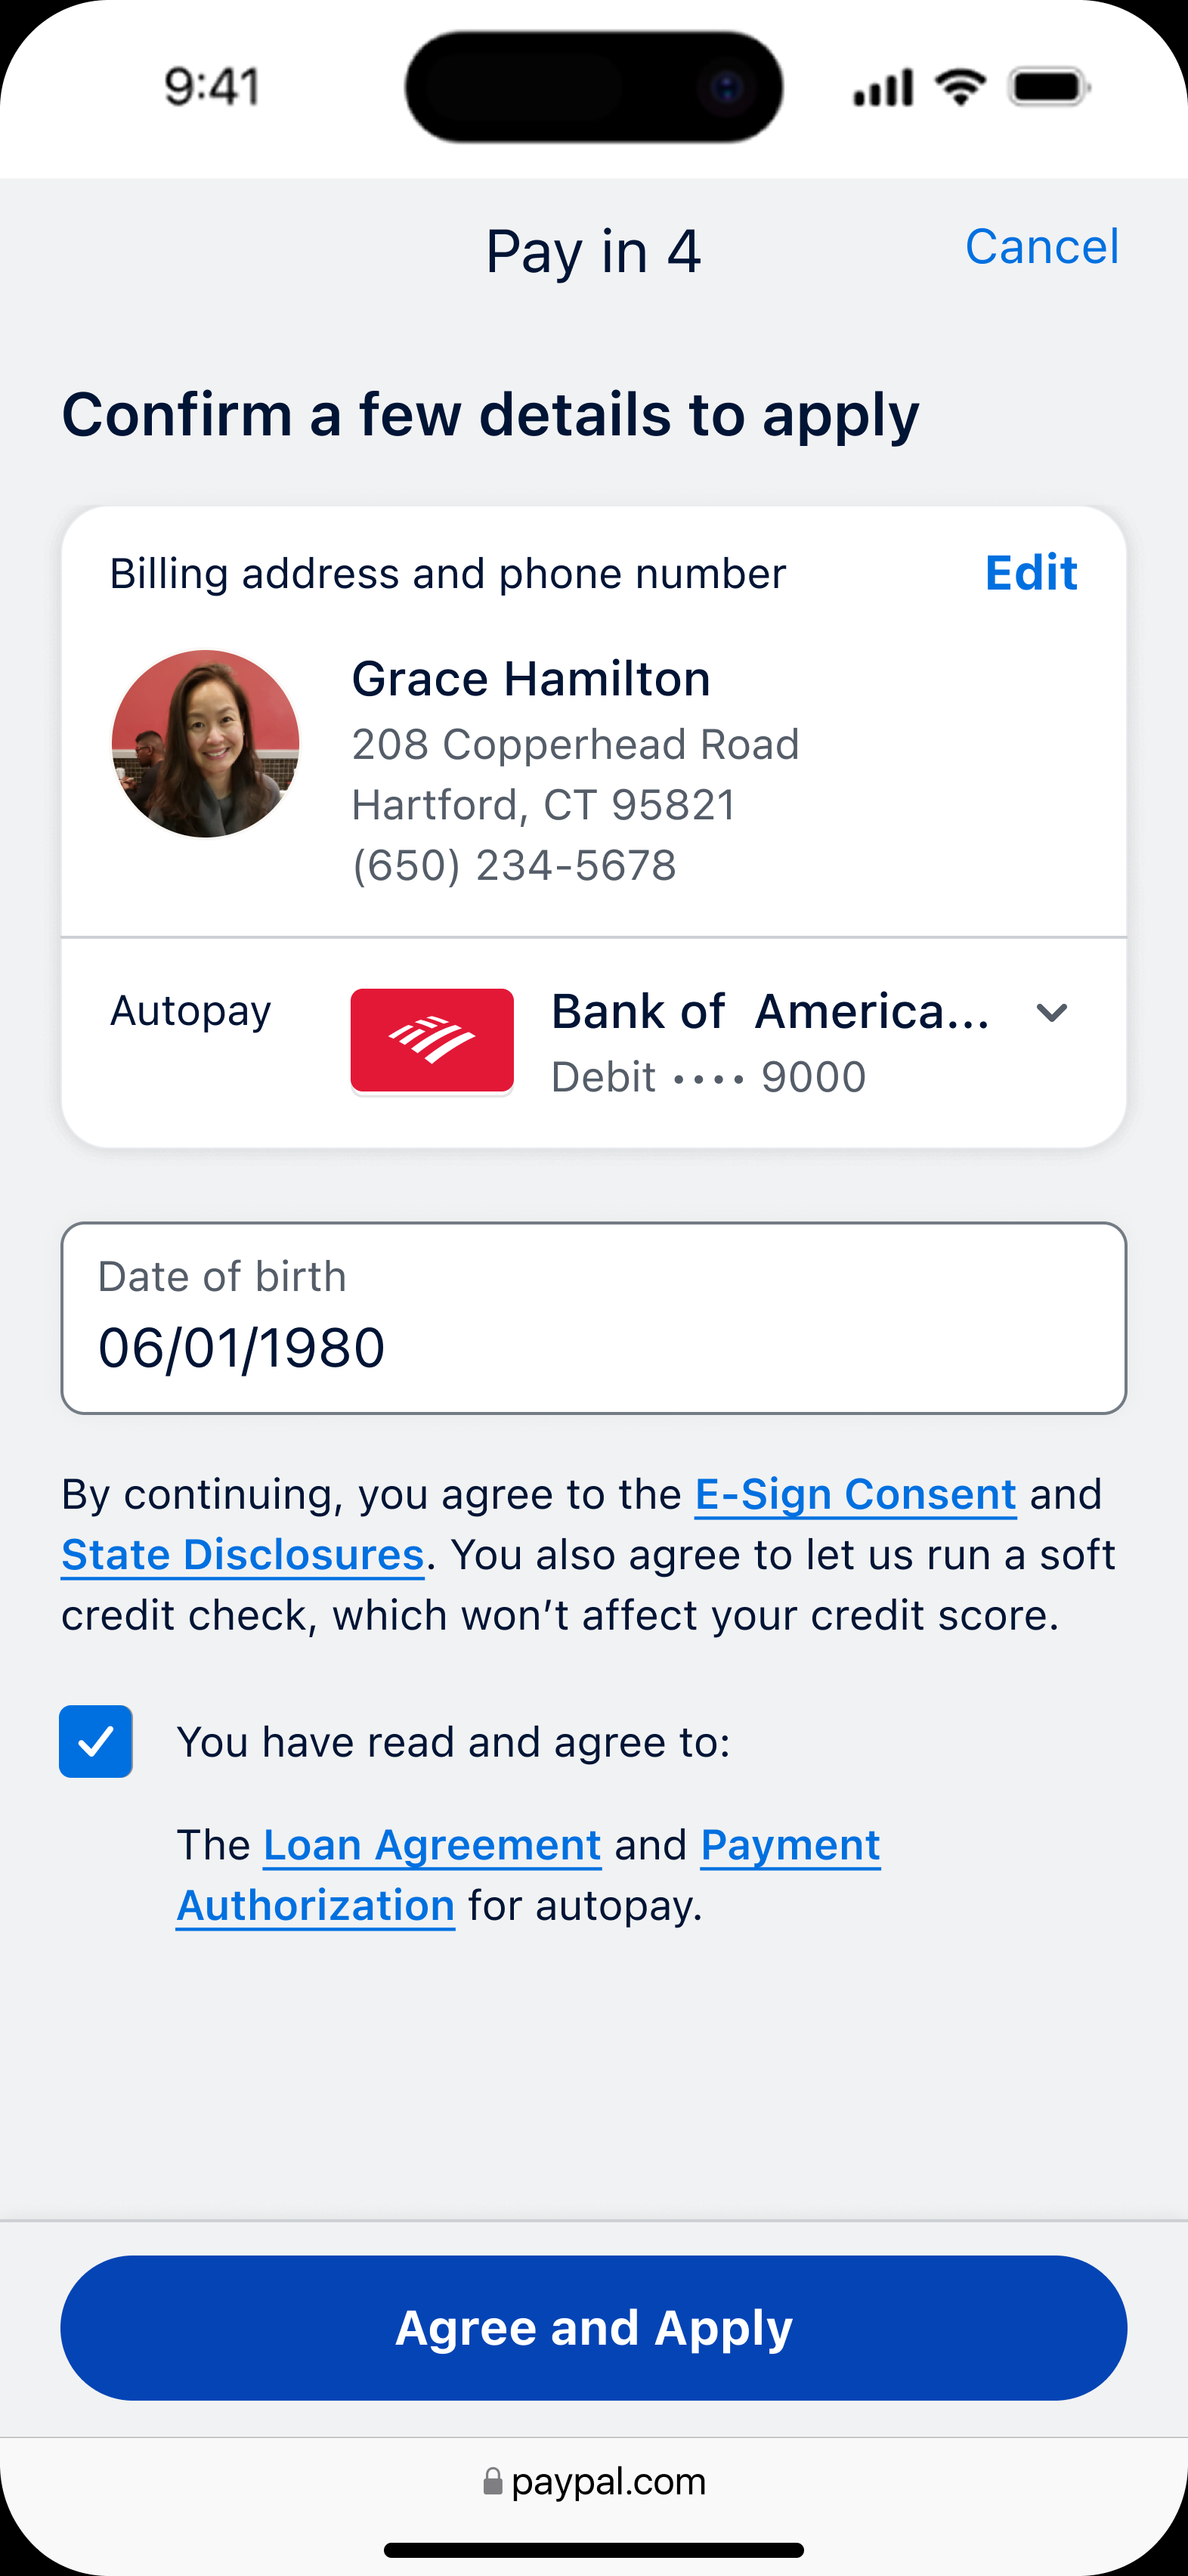
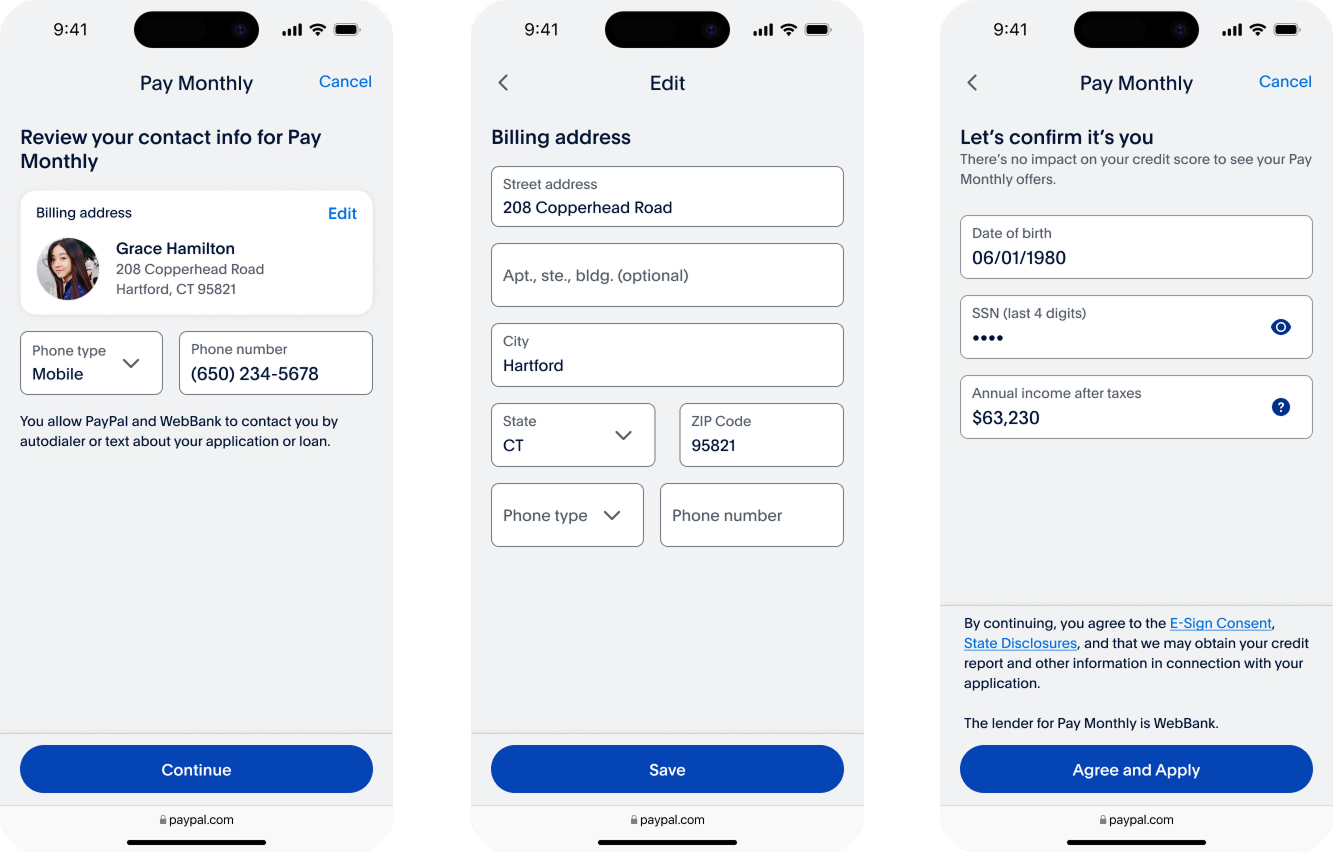
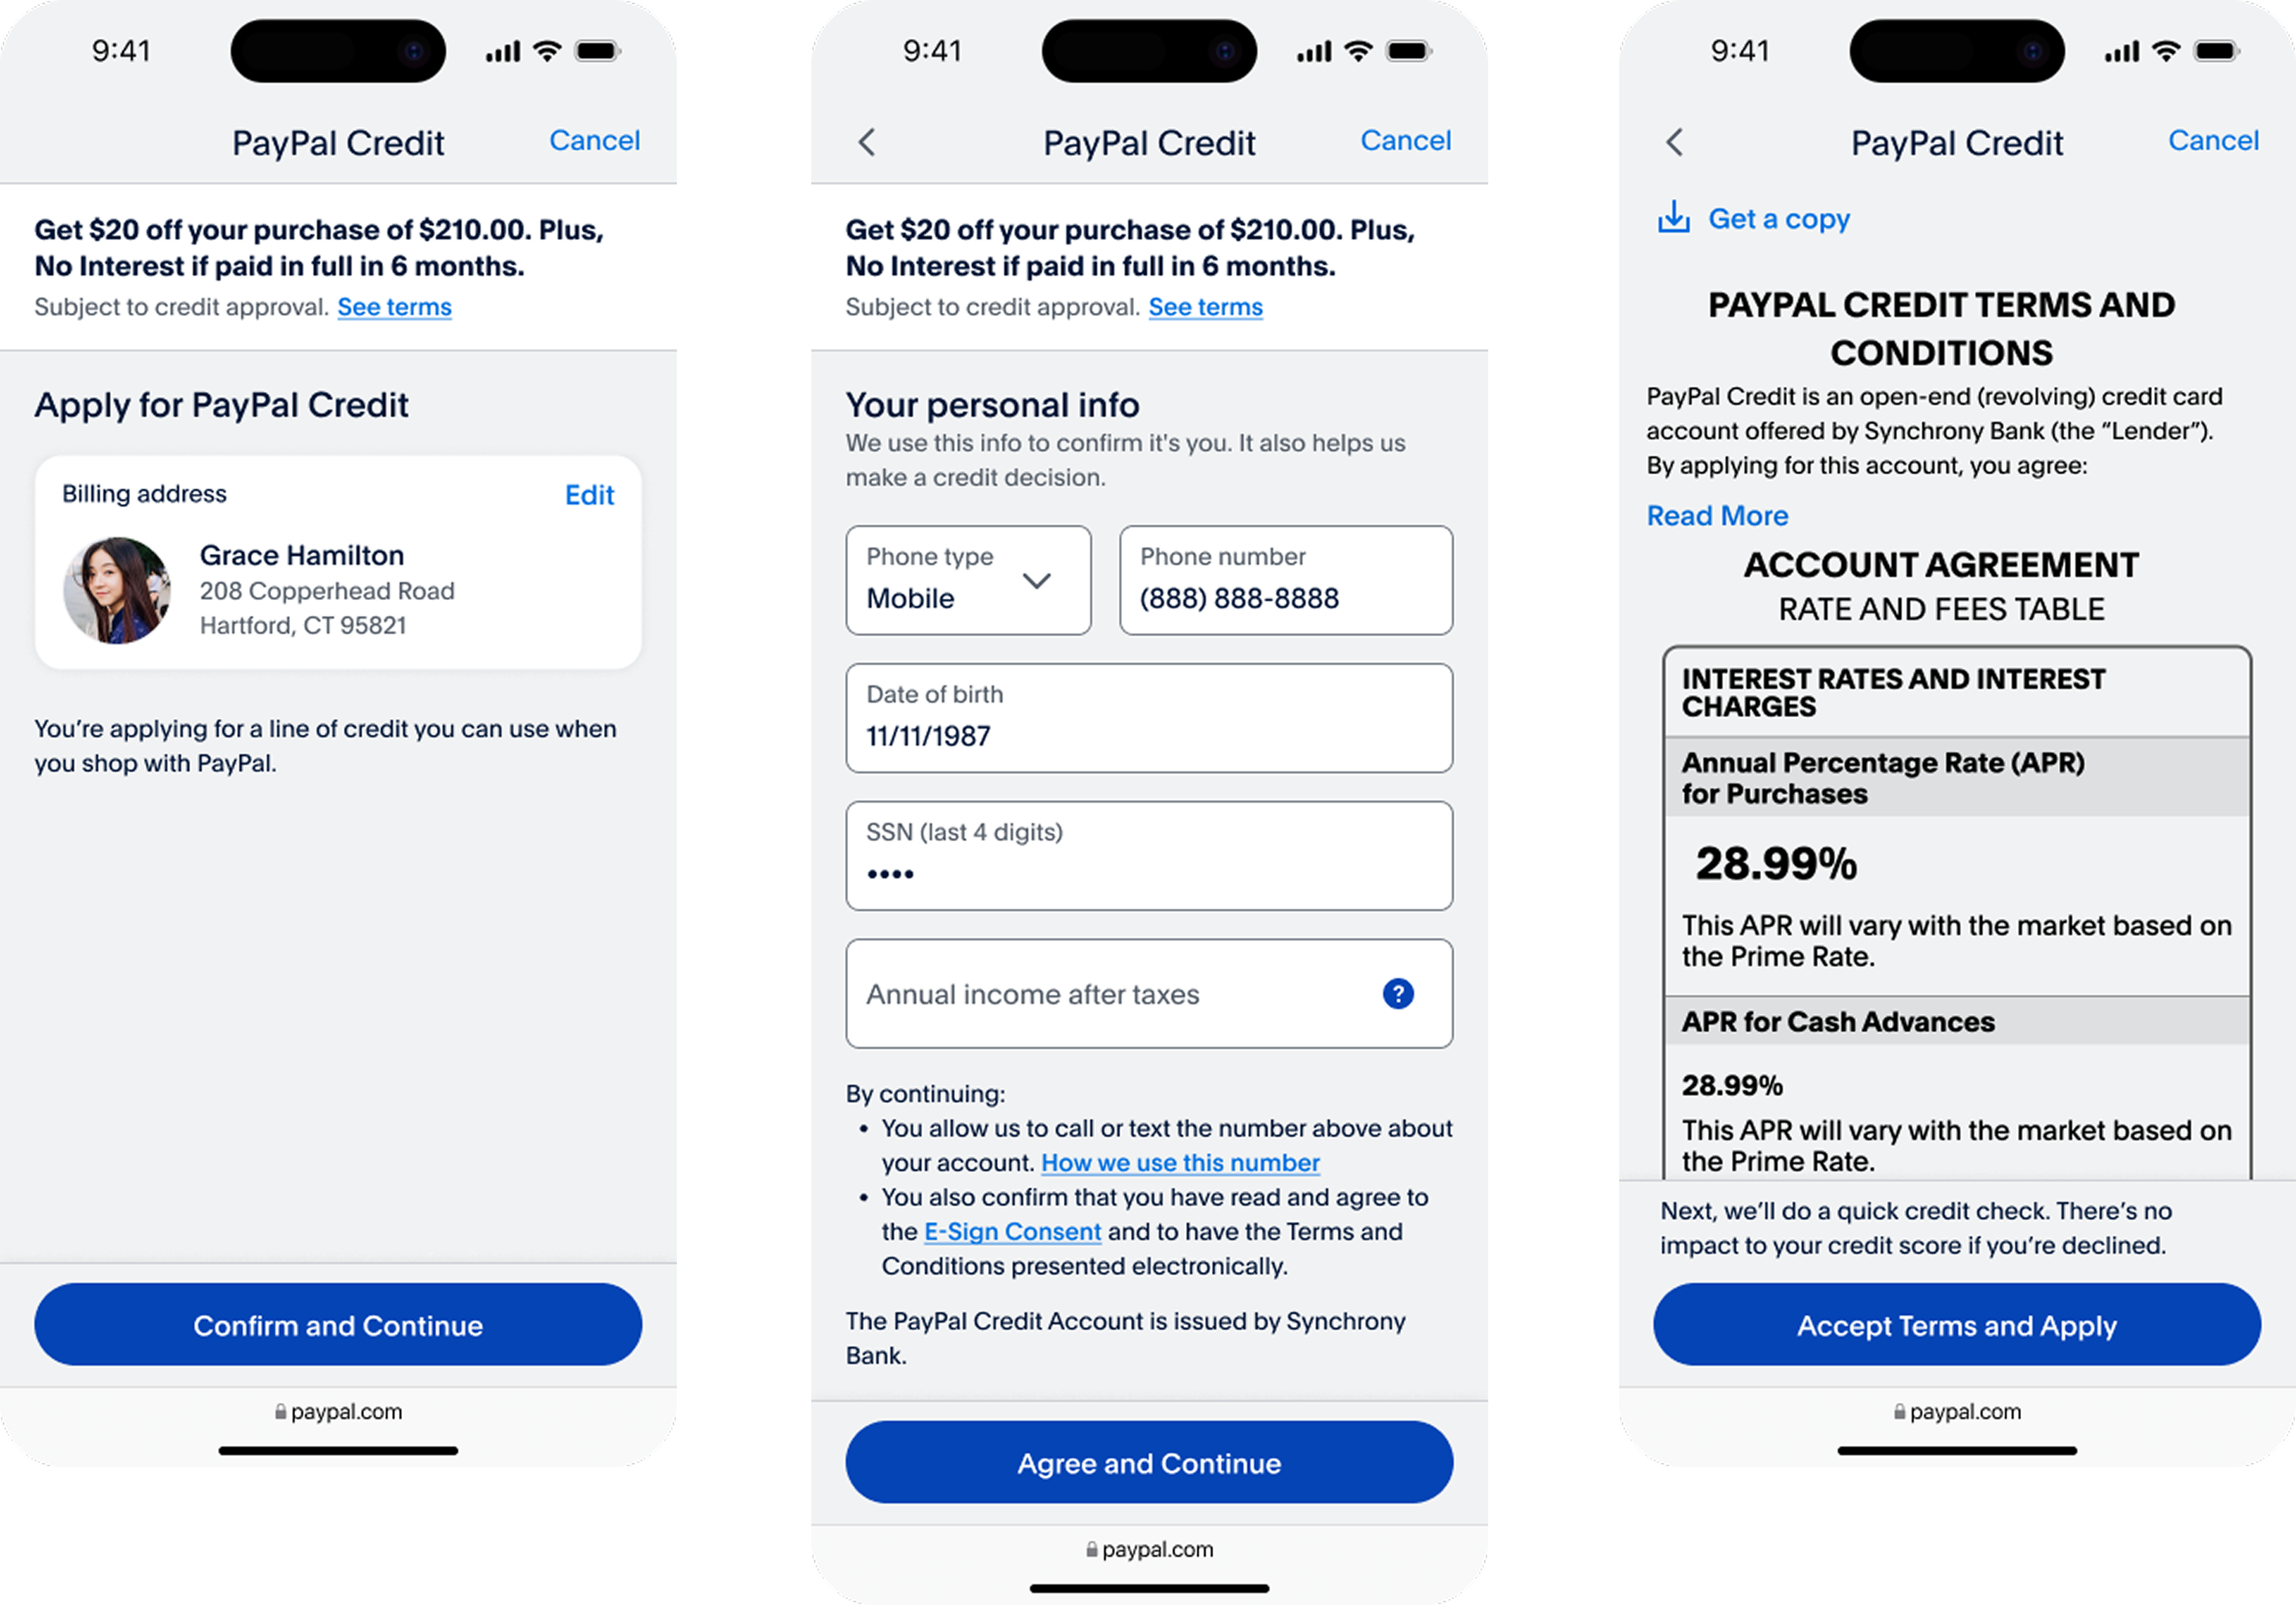
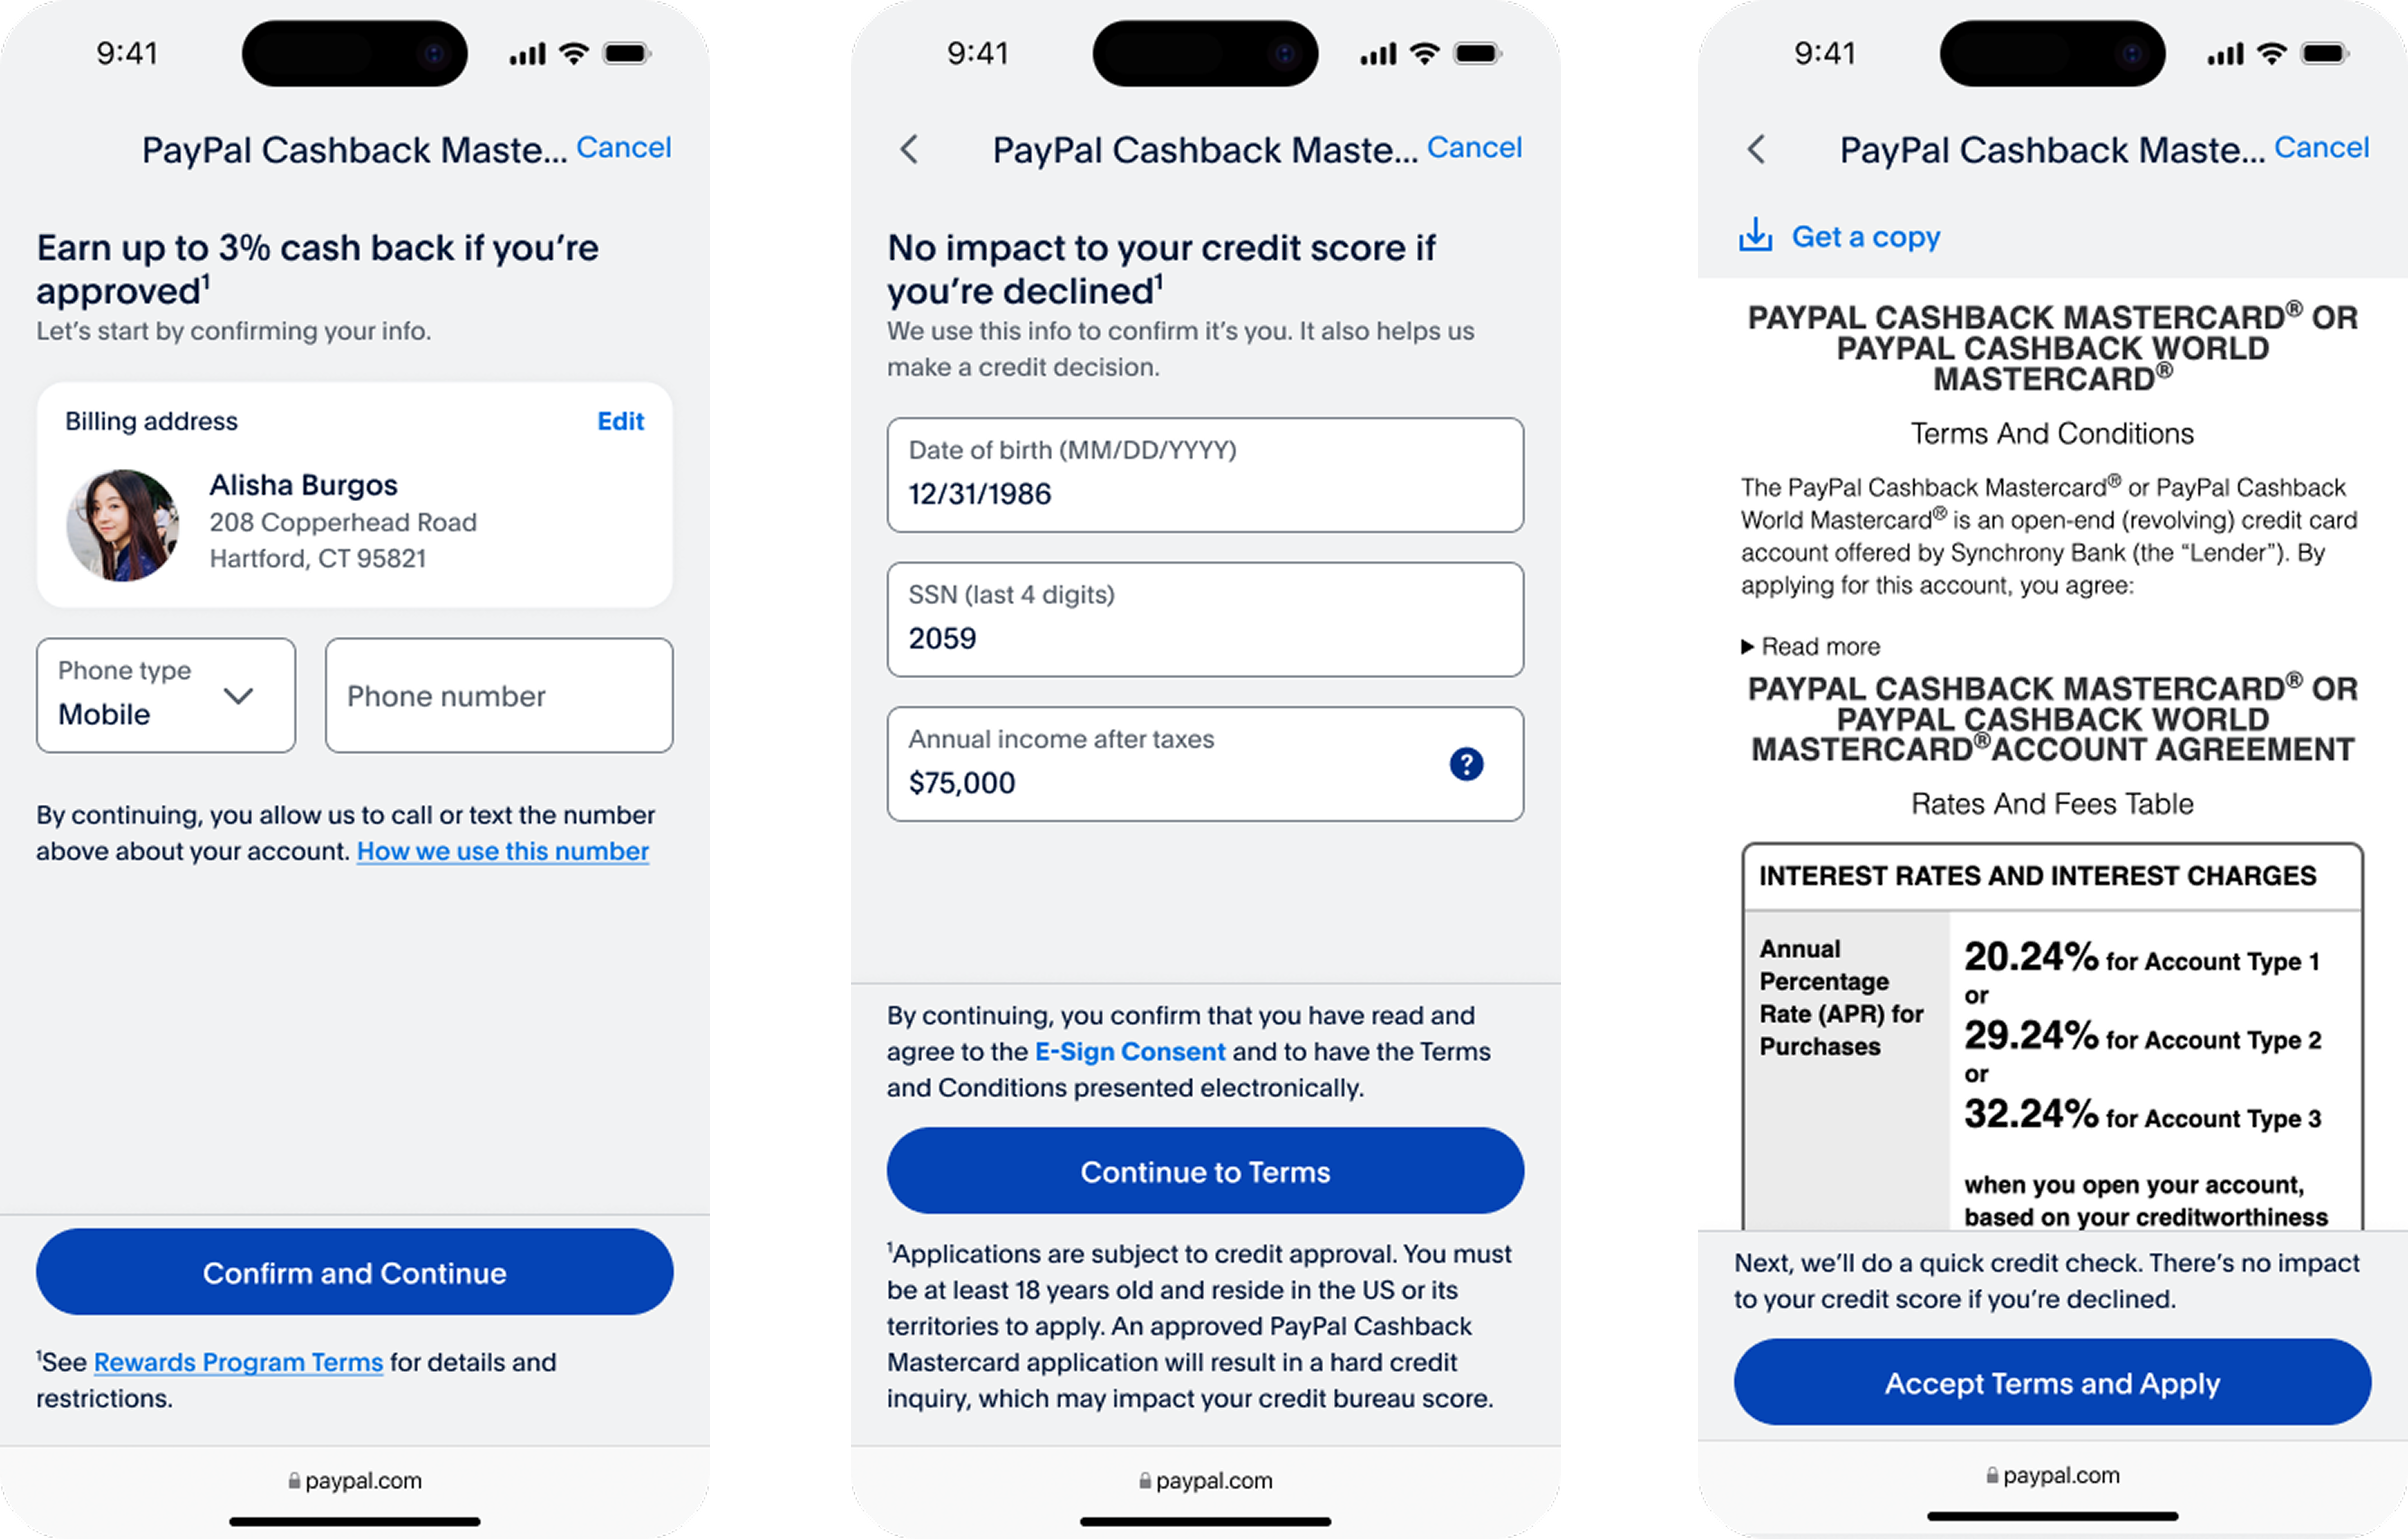
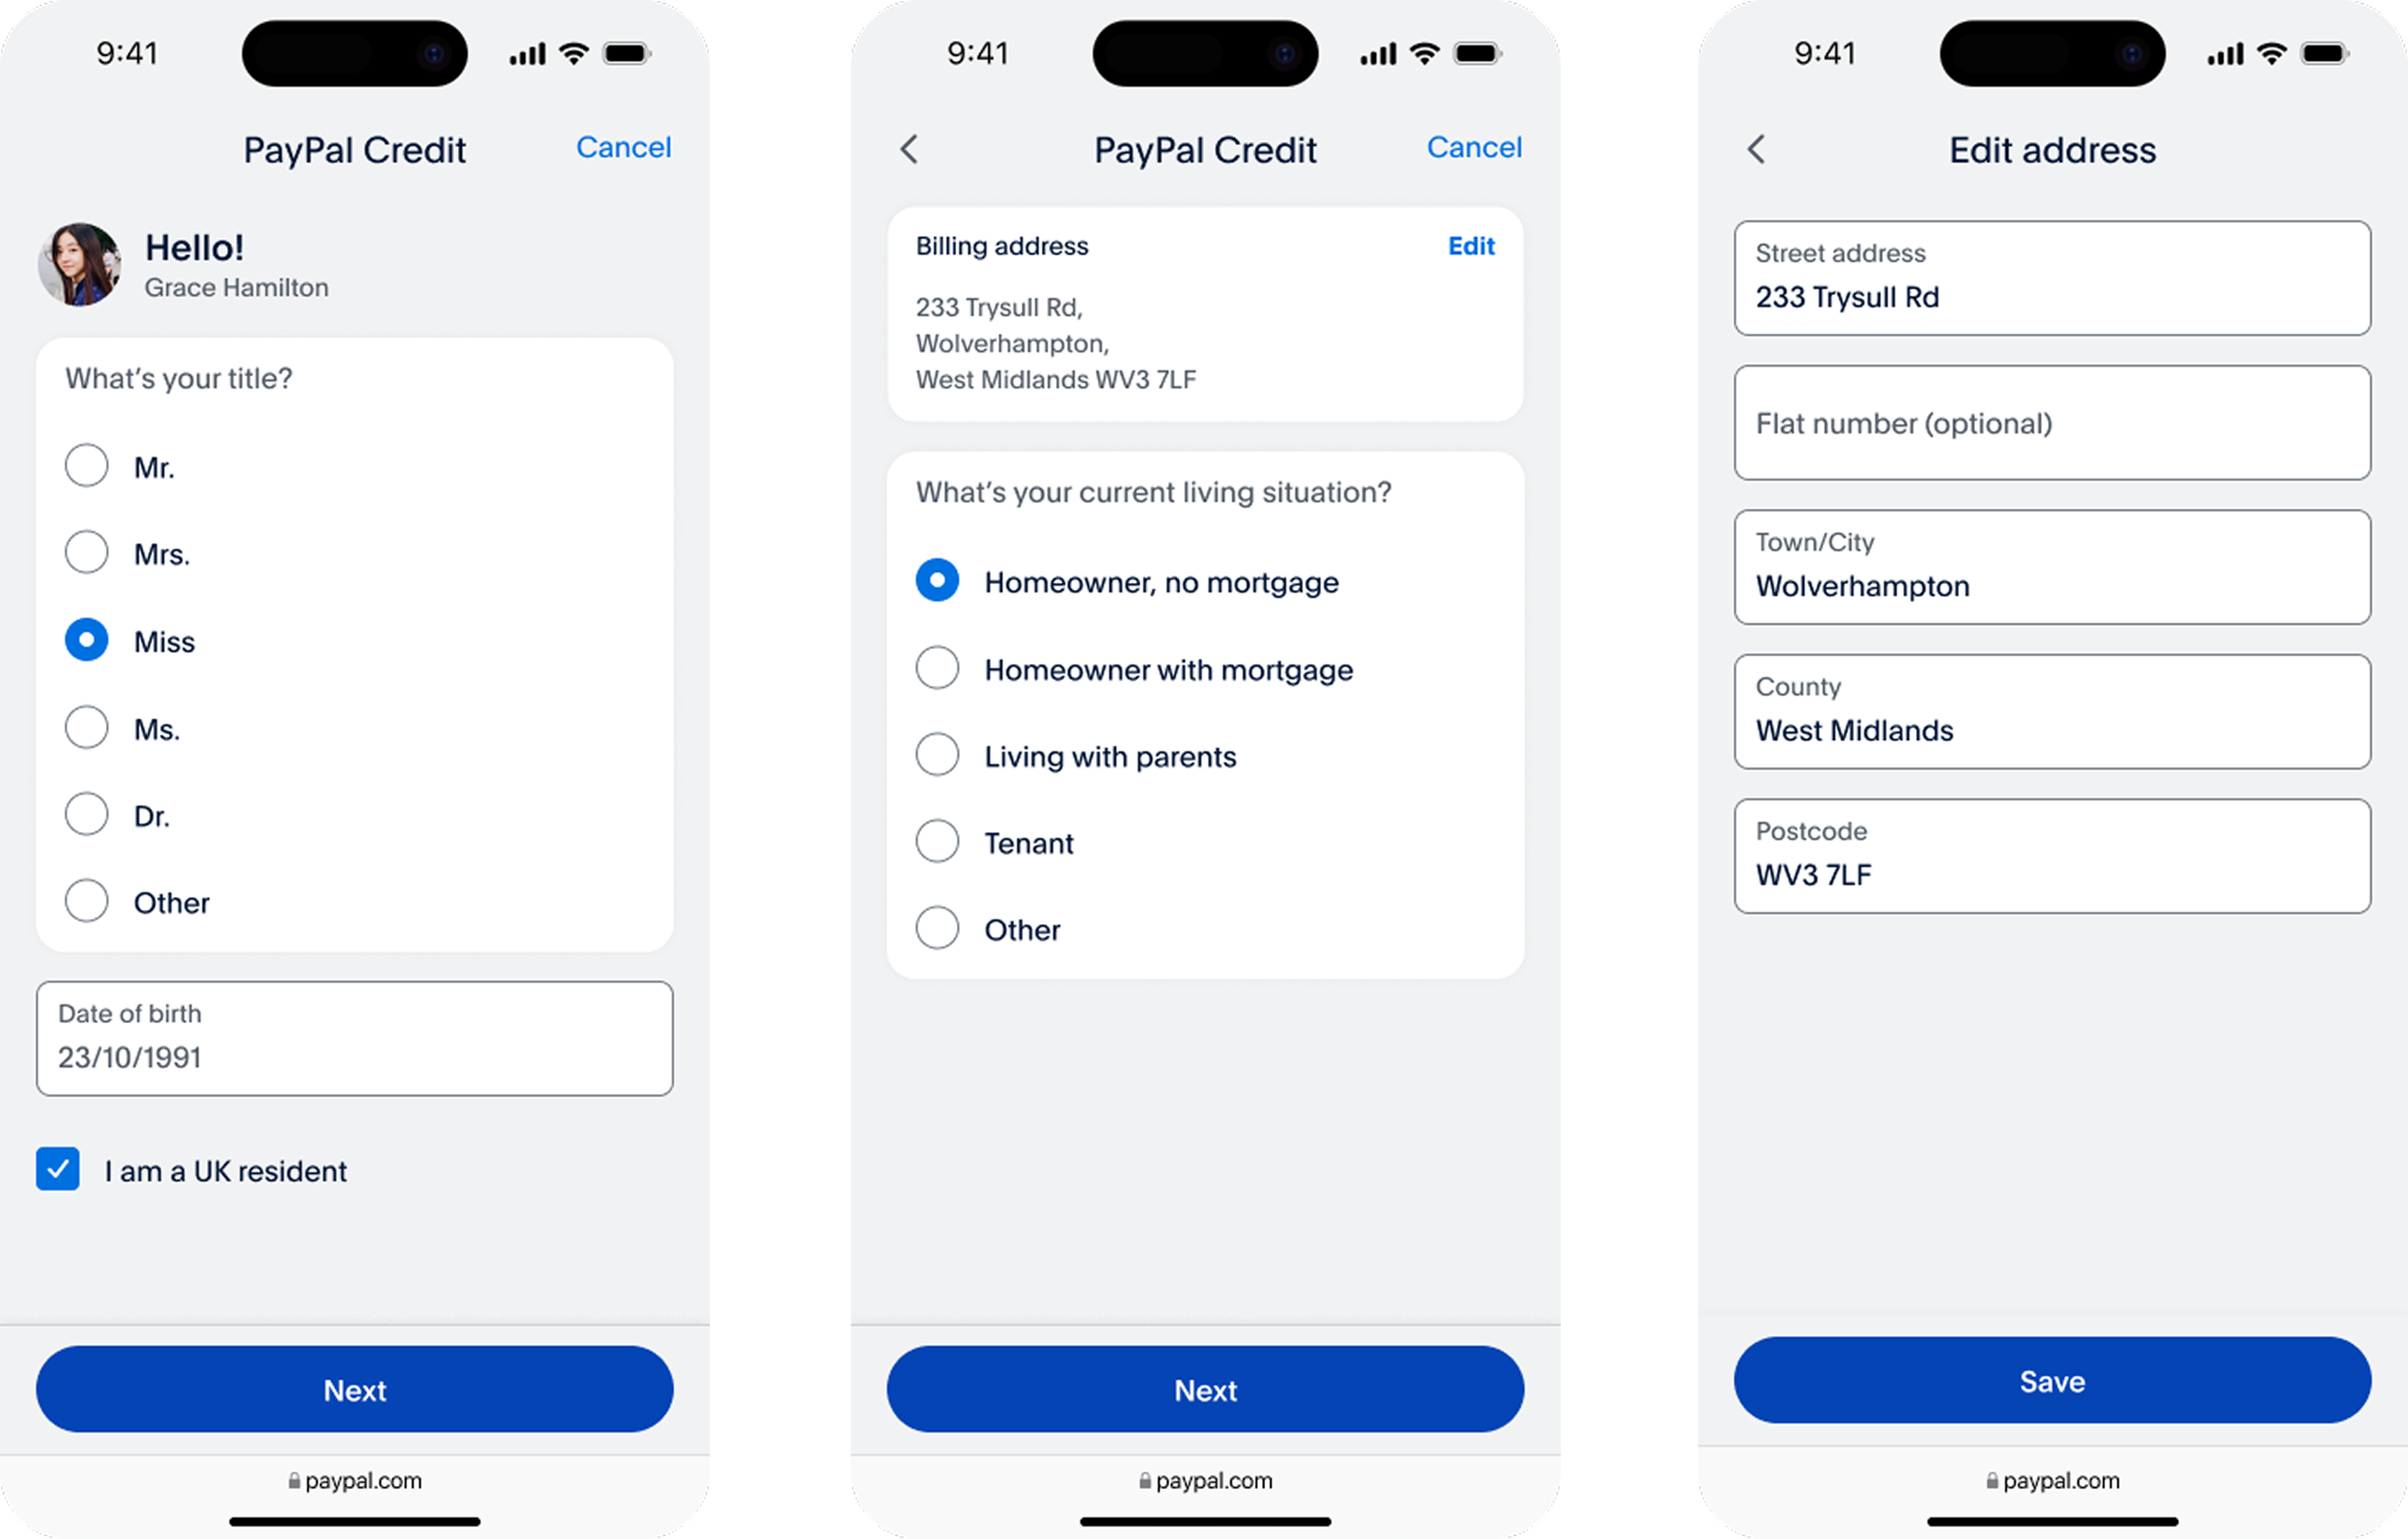
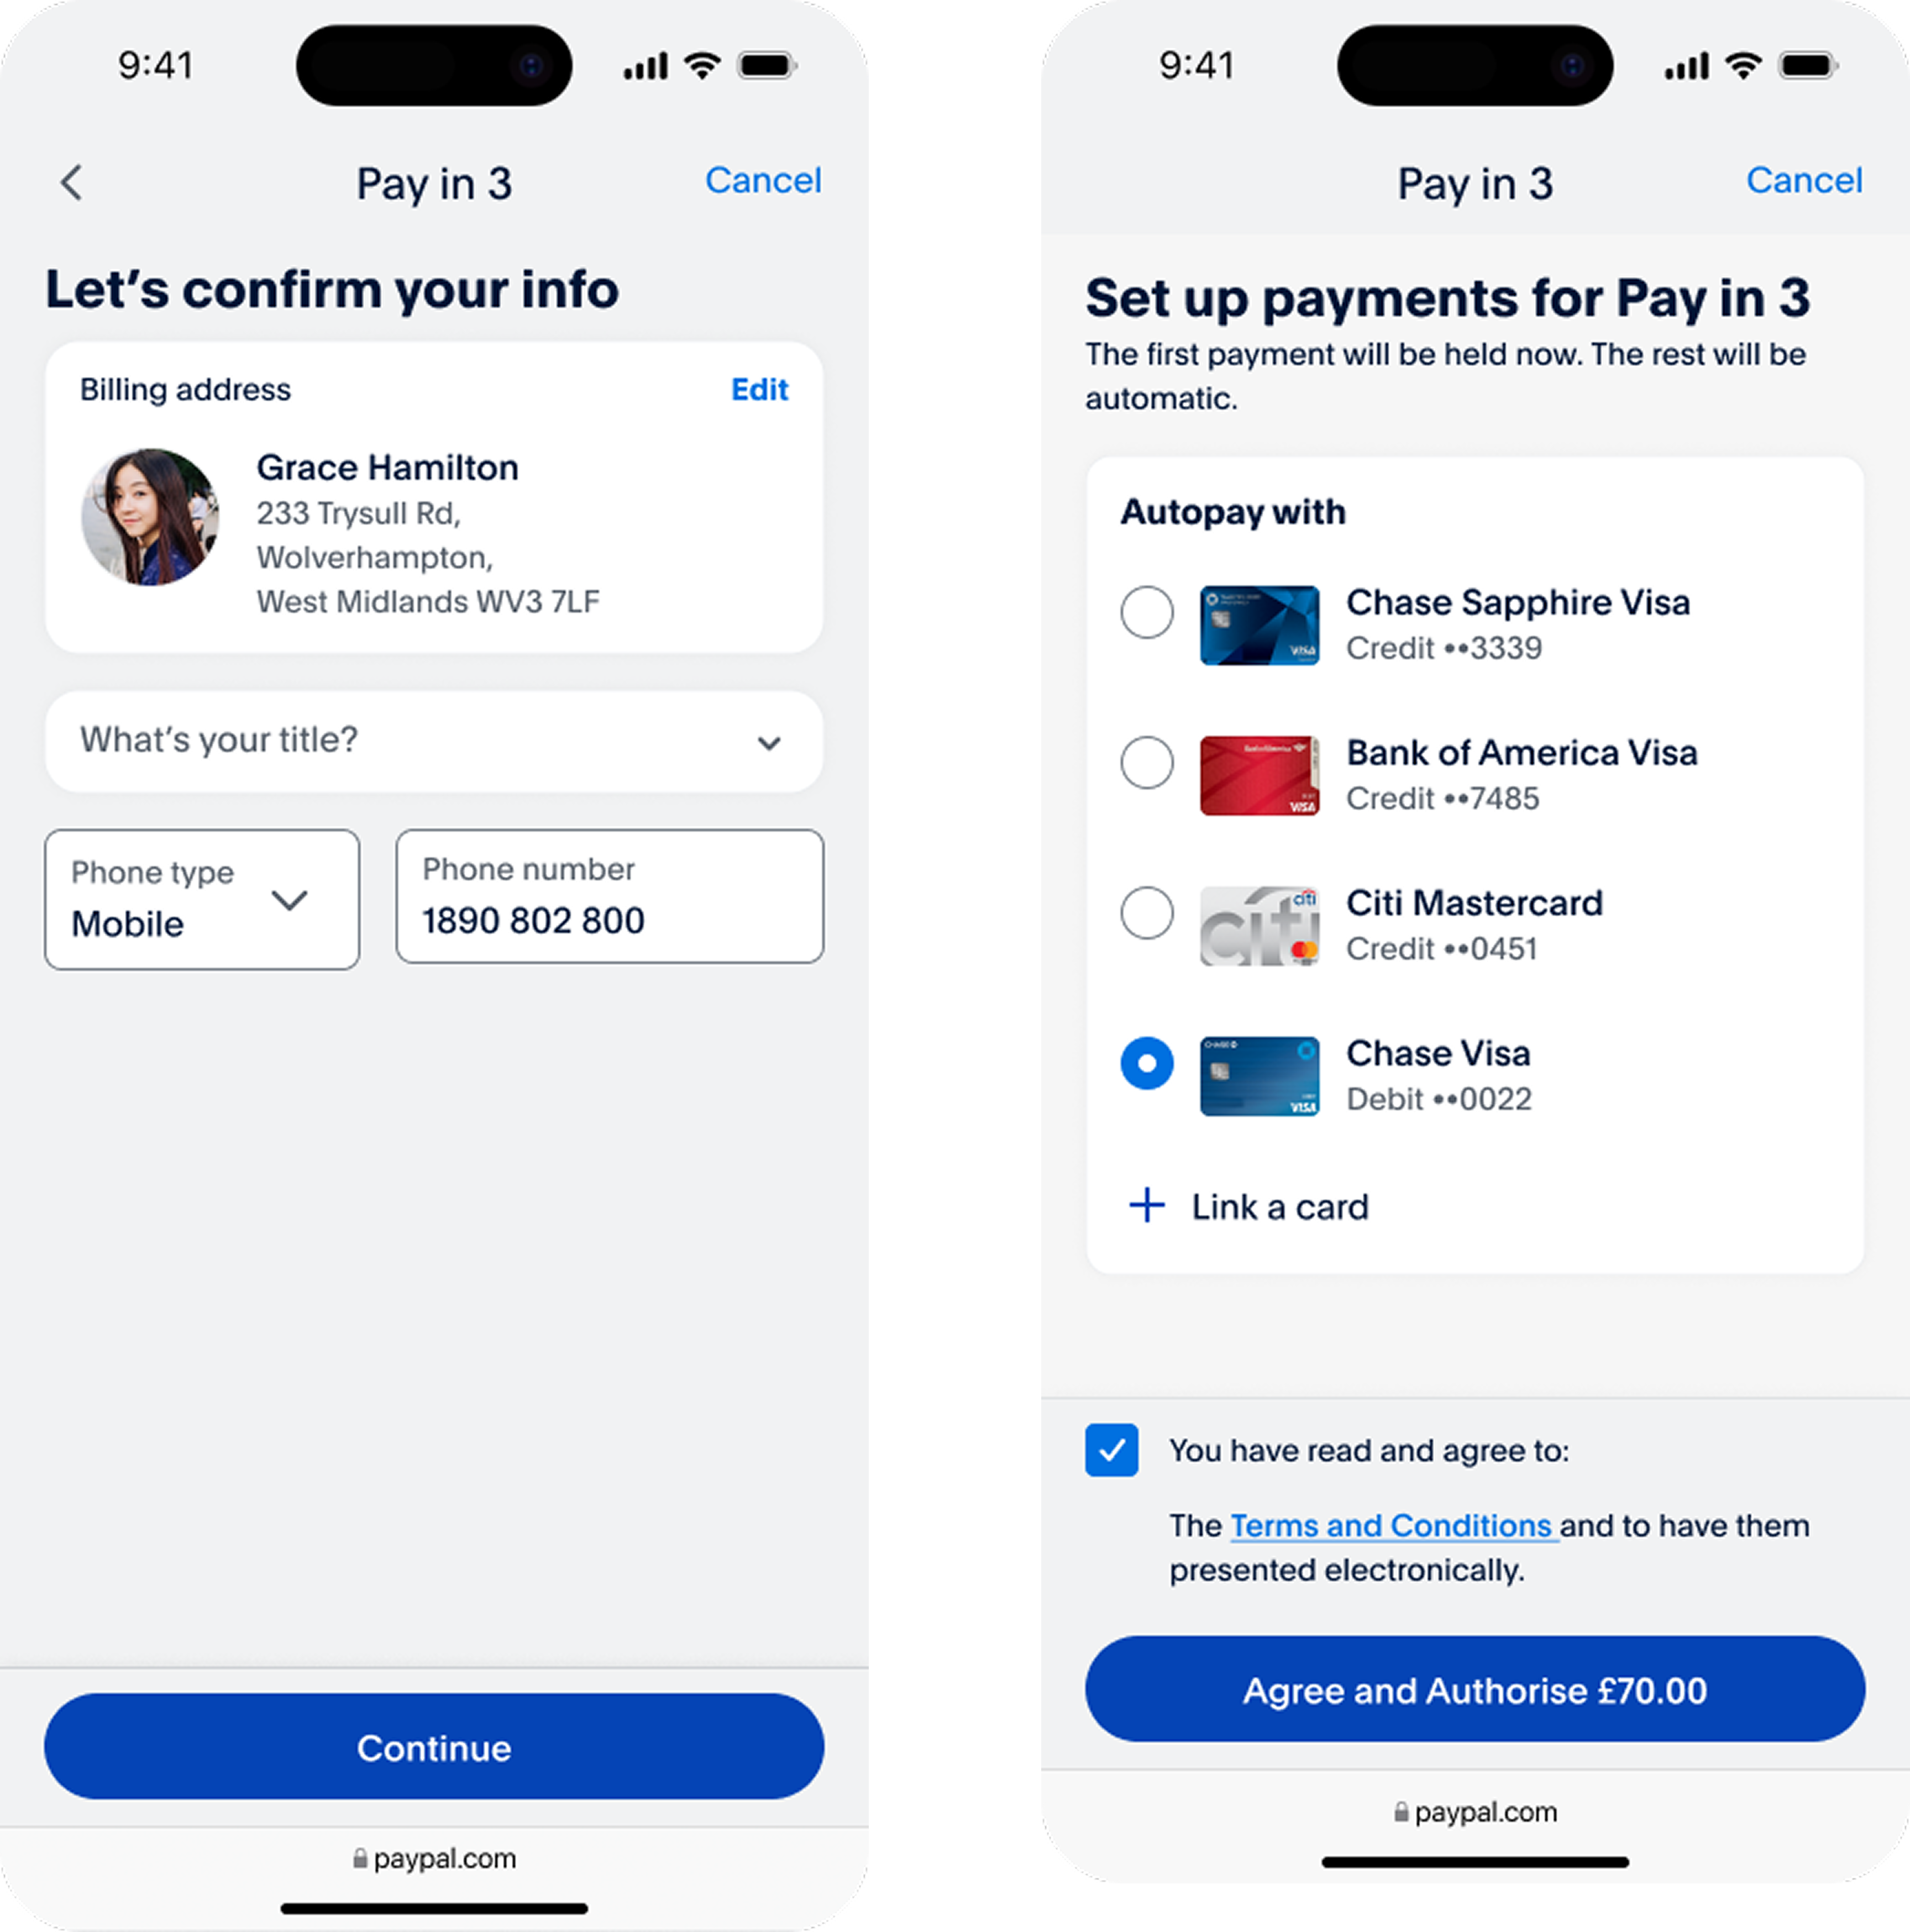
The redesign consolidated the journey into a single review-and-apply page: offer context, customer details, payment method, agreements, and the decision, then back to checkout.
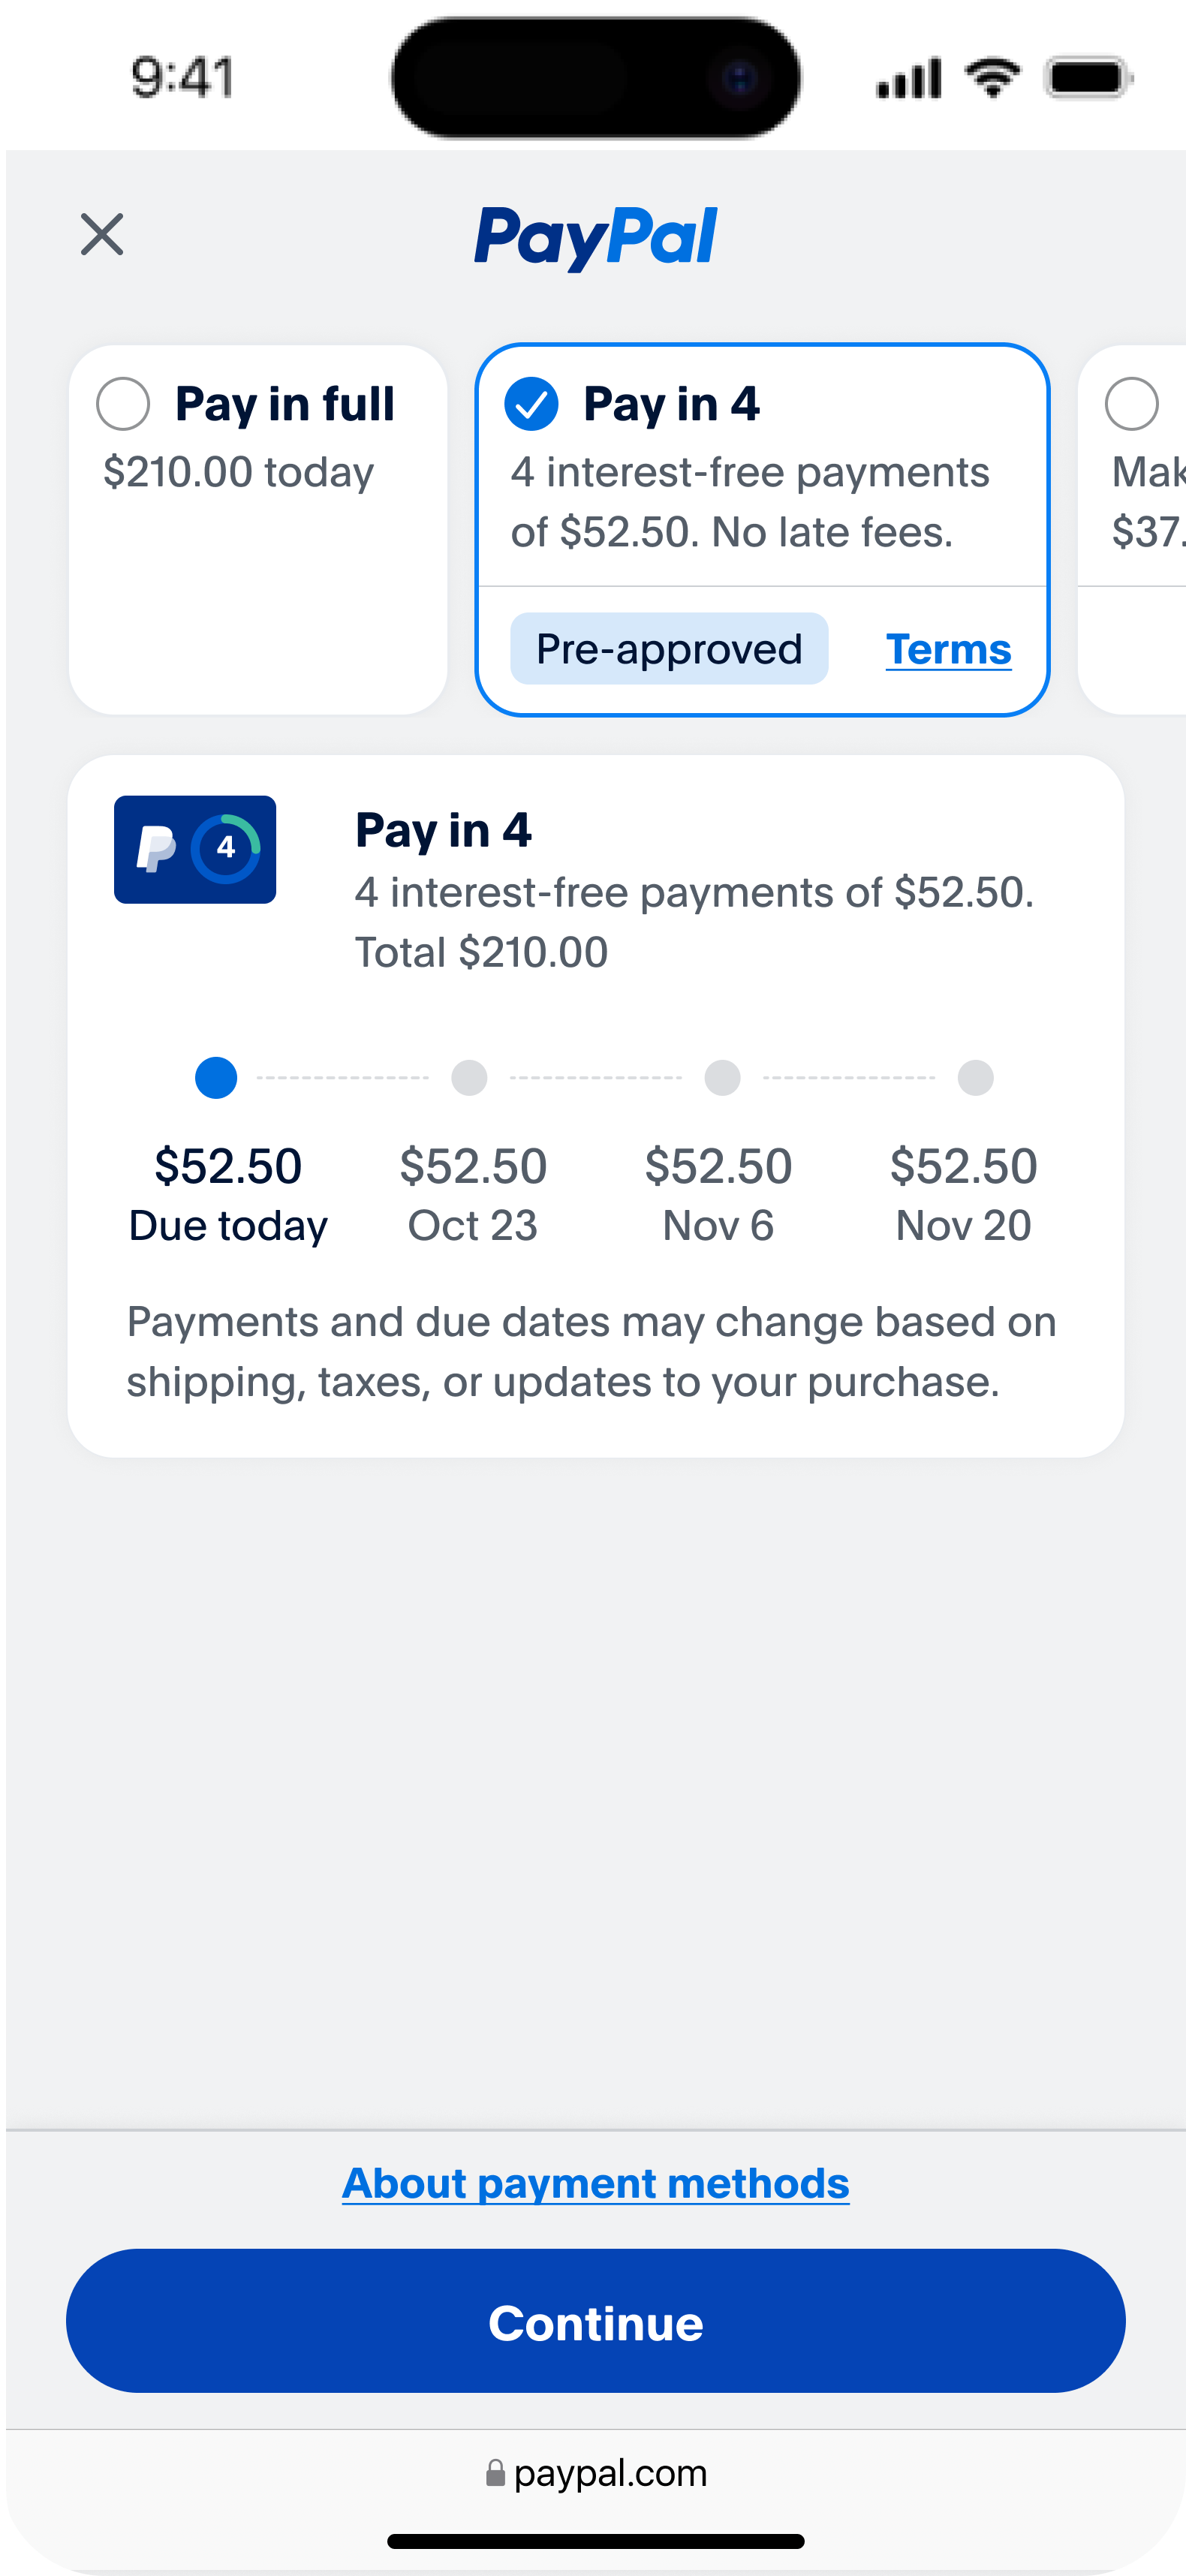
The three parts of the shared pattern
2.08×
Application completion
01 — Core flow
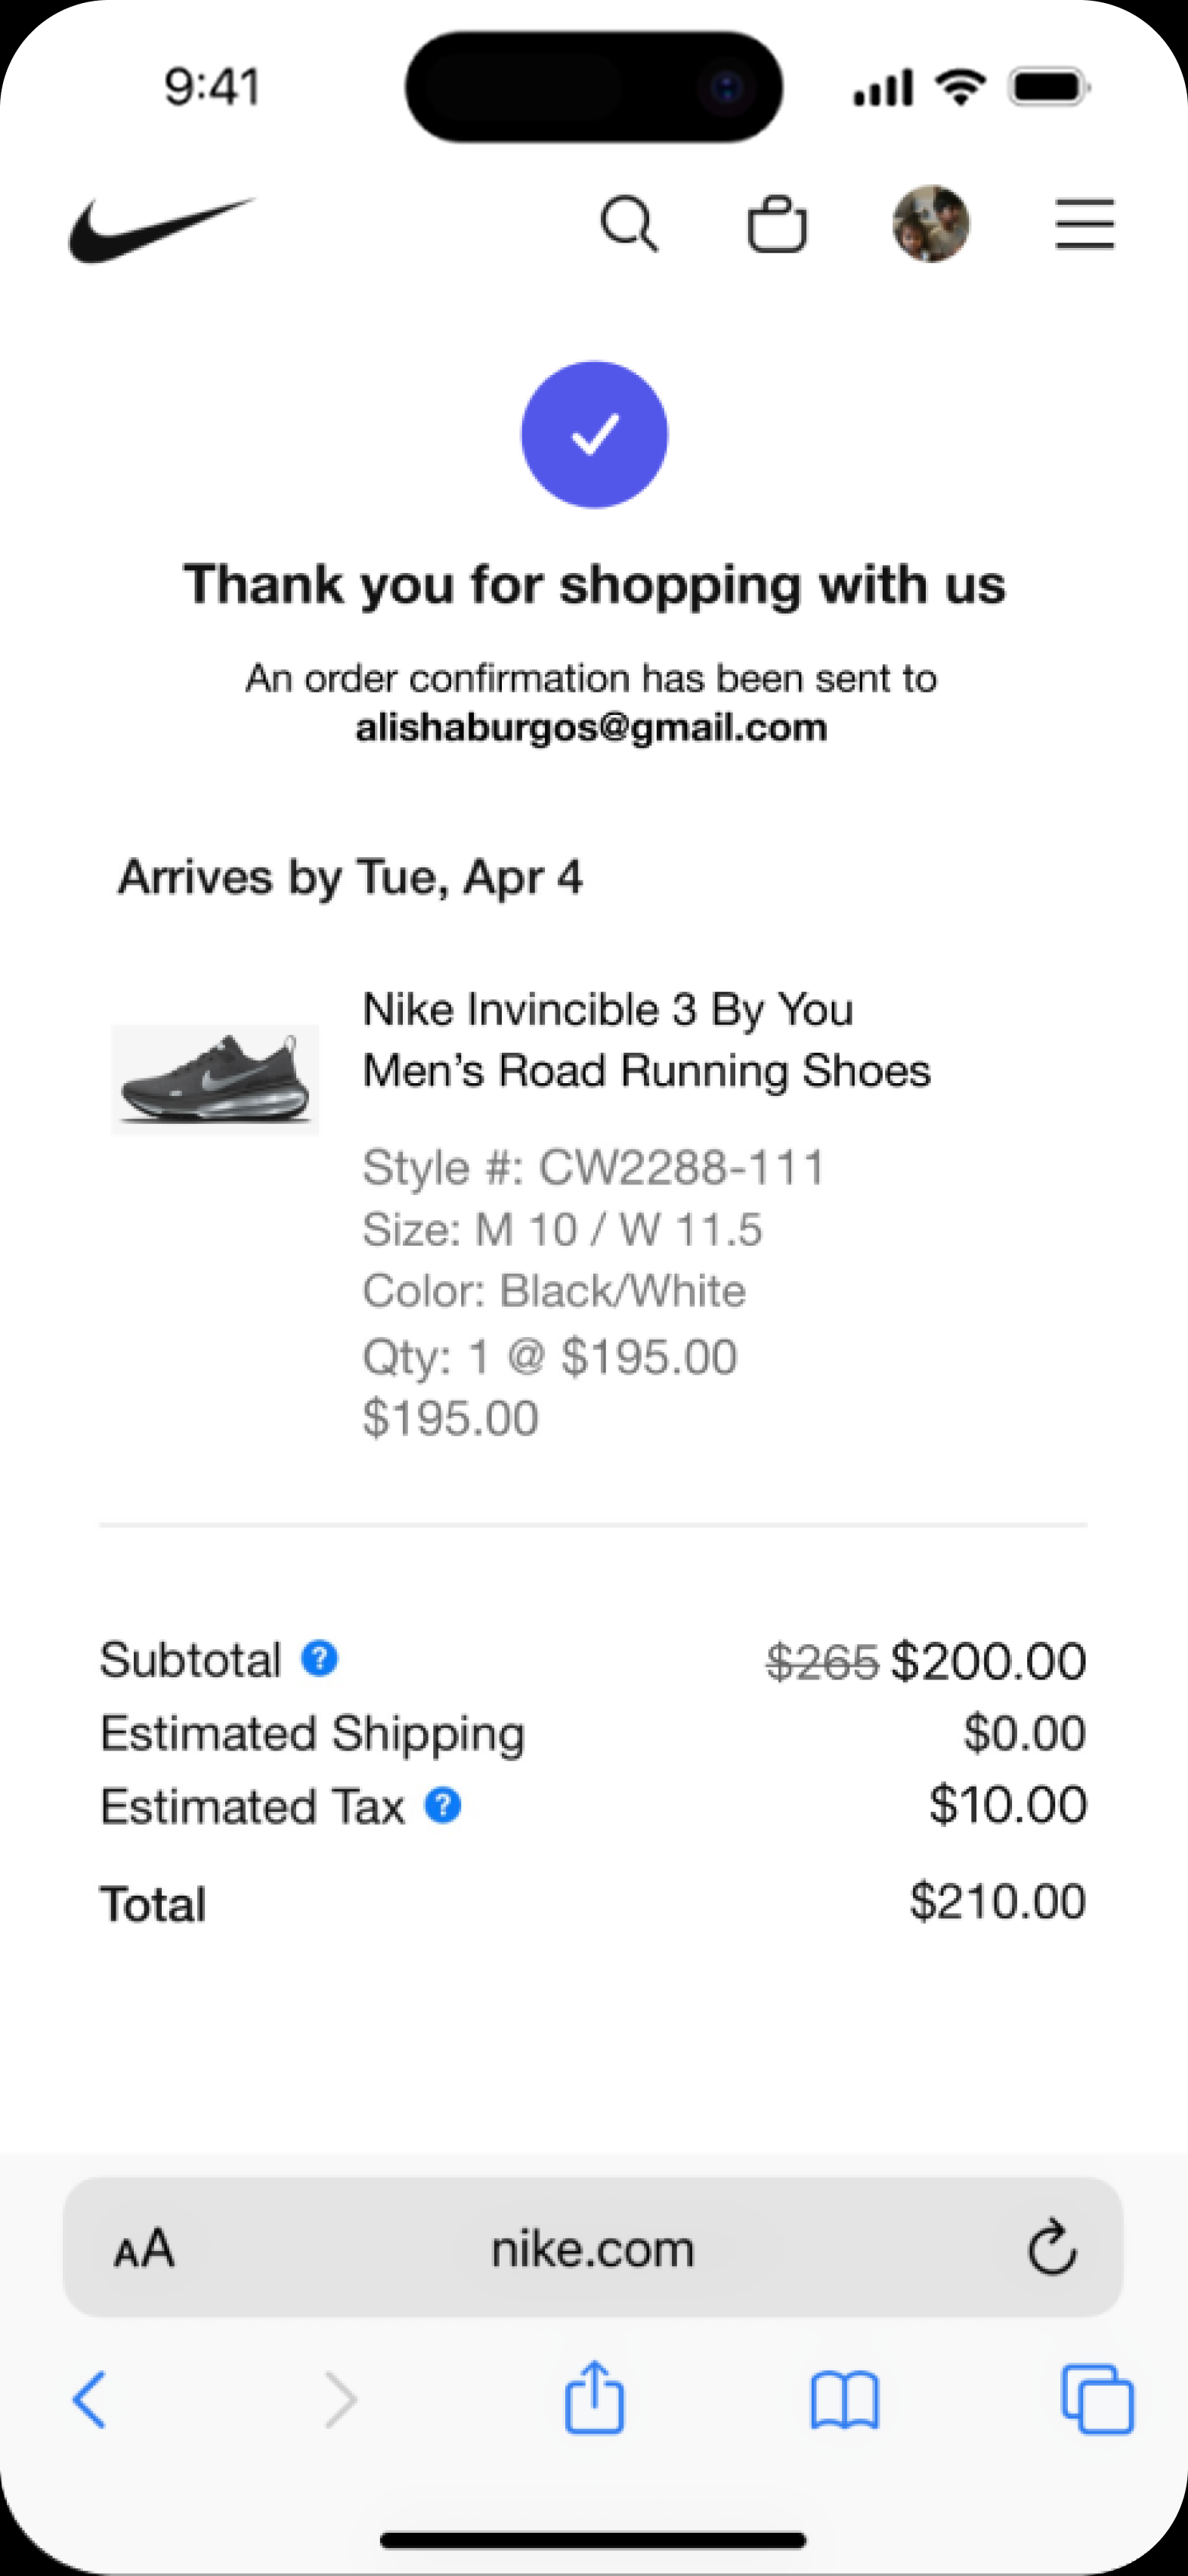
Checkout offer, one review-and-apply page, approval returned to checkout.
02 — Content rules
Value, payment schedule, editable customer details, payment method, and agreements sit above one Agree and Apply action.
03 — Controlled variants
The flow holds while product fields, underwriting requirements, and US or UK disclosures change inside it.
One product proved the pattern. Six products demonstrated its value.
Pay Monthly
2.3%
Increase in conversion
5.45%
Increase in annual iRev
PayPal Credit US
6.3%
Increase in conversion
10.32%
Increase in annual iRev
PayPal Mastercard
3.1%
Increase in conversion
7.61%
Increase in annual iRev
PayPal Credit UK
5.3%
Increase in conversion
2.22%
Increase in annual iRev
Pay in 3 UK
78%
Increase in conversion
37%
Increase in average monthly TPV
US Credit
Pay in 4
0%
TPV
Pay Monthly
0.00%
iRev
PayPal Credit
0.00%
iRev
PayPal Mastercard
0.00%
iRev
UK Credit
Pay in 3
0%
TPV
PayPal Credit
0.00%
iRev
Every product figure is a change against that product’s preceding annual baseline — independent results, not shares of a portfolio total. iRev is annual incremental revenue; TPV is payment volume. The portfolio rows below measure the 2023 baseline against H1 2024.
2023
H1 2024
Credit portfolio utilization
Credit portfolio conversion
51% to 79%, an increase of 28 percentage points
Behind the Work
How the work ran: one shared pattern, recurring cross-functional review, six-product delivery
One shared application pattern governed the work. It fixed the core flow, named the variants each product was allowed, and carried the US and UK legal exceptions. Recurring product, legal, design, and leadership reviews held all six teams to it, from requirements through development and measurement.
Design System Gap → Build Plan
Synthesized six product teams’ funnels, success metrics, and US–UK regulatory constraints into one model in ChatGPT. It carried 40+ iterations through stakeholder review.